


Trade wrangling between major economies, cautious central banks and jumpy energy prices are reshaping where risk really sits in global markets right now. For investors, that mix can punish some holdings while quietly rewarding others that are more closely linked to supply routes and fuel flows. This article explains how those cross-currents affect three specific stocks from our Global Energy Infrastructure and Producers screener that screens as positively exposed to the latest news shock.
The three stocks below are just a small sample of what rises to the surface, and the full Global Energy Infrastructure and Producers screen flags 14 more companies with equally compelling stories that are not covered here.
If you want to go beyond this snapshot and quickly identify which oil, gas, pipeline and shipping plays best fit your own thesis, head straight into the Global Energy Infrastructure and Producers screener to filter, analyze and focus on your highest conviction ideas.
Journey Energy (TSX:JOY)
Journey Energy is a Calgary based oil and gas producer that fits the Global Energy Infrastructure and Producers theme by offering direct exposure to crude and natural gas pricing in Canada. The business earns about CA$180 million from Canadian operations and carries a market value of roughly CA$414 million.
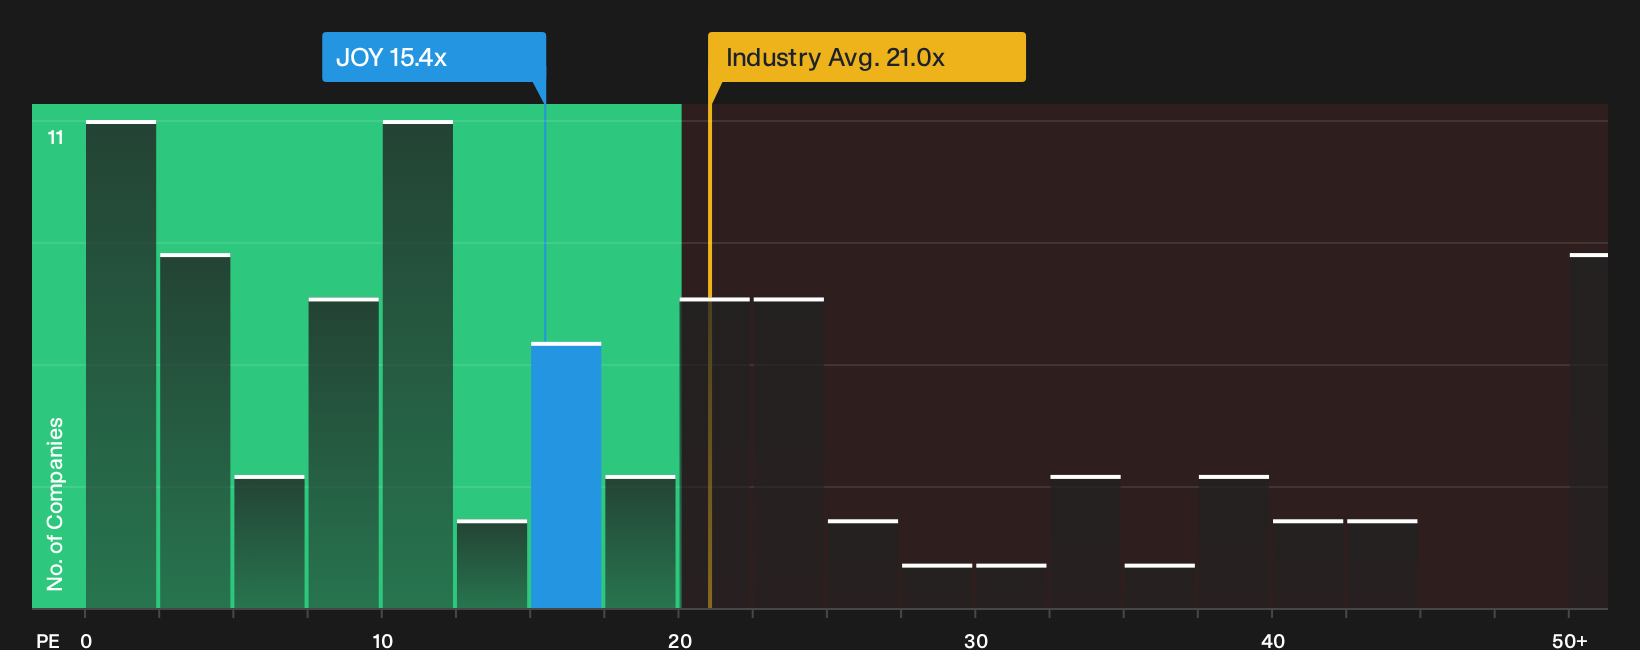
Journey Energy ties directly into energy price swings through its Canadian oil and gas production, which now leans 65% toward crude and liquids based on 2026 guidance. Earnings growth, a 14.9% net margin and a below industry P/E all hinge on what happens when that commodity sensitive mix meets one unresolved cost of capital pressure.
That cost of capital pressure makes it worth reading the 4 key rewards and 1 important warning sign before deciding how Journey Energy fits your portfolio thesis.
Ensign Energy Services (TSX:ESI)
Ensign Energy Services plugs directly into the Global Energy Infrastructure and Producers theme by supplying drilling and well servicing that rise and fall with oil and gas activity, generating about CA$1.6 billion from oilfield services and carrying a market value near CA$713 million.
Growing reliance on high spec triples and deeper wells in North America pushes Ensign to operate closer to equipment limits, which can increase maintenance intensity and downtime risk and put pressure on net margins.
What really matters now is how one less visible cost pressure shapes future pricing power and the path back to healthier margins.
That hidden cost pressure is only the start, and the full narrative for Ensign Energy Services explores how Ensign Energy Services could manage equipment strain in ways that support pricing power and a cleaner earnings story.

Transocean (RIG)
Transocean plugs directly into the Global Energy Infrastructure and Producers theme as a pure offshore contract driller, earning about US$4.1b from contract drilling services and carrying a roughly US$6.3b market cap that rises and falls with deepwater project demand and rig utilization.
If oil falls hard and operators push their 2027 projects to the right, the debt does not go away and the stock goes nowhere for a long time.
What happens to Transocean’s margins and balance sheet now largely hinges on how one crowded corner of the offshore rig market clears or stalls.
That inflection point is exactly where the full narrative for Transocean shows how Transocean could turn rig tightness and debt overhang into accelerating leverage to any sustained offshore cycle.

Seeking Alternatives Before The Crowd
Fresh opportunities move fast. Some are breaking out, others quietly building momentum while attention is elsewhere. Spot them under the radar for now and act before pricing gets caught up to get in early.
- Spot income workhorses that aim to keep paying even when markets wobble by scanning the 2 dividend fortresses curated for durability and yield focus.
- Track early movers riding real commercial demand in AI by using the hand picked 74 profitable AI stocks that aren't just burning cash before enthusiasm sends valuations higher.
- Identify potential inflation hedges and metal producers with real projects by reviewing the carefully filtered 35 elite gold producer stocks while these ideas are still dropping under most radars.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com