


- Rhythm Pharmaceuticals and collaborators presented six new data sets at the 64th ESPE Meeting in Marseille, covering real-world and Phase 3 results for setmelanotide in paediatric acquired hypothalamic obesity, including BMI changes, hunger scores and cardiometabolic risk indices.
- The breadth of BMI and composite metabolic index readouts in a rare, paediatric hypothalamic obesity population gives Rhythm Pharmaceuticals additional clinical depth behind its MC4R pathway franchise, which matters for reimbursement discussions and future indication expansion.
- We will now look at how Rhythm Pharmaceuticals' investment narrative could shift given these paediatric BMI and metabolic risk data.
Rhythm Pharmaceuticals Investment Narrative Recap
To own Rhythm Pharmaceuticals, you need to believe that setmelanotide can support a durable rare disease franchise and that management can scale beyond a single-asset story. The latest ESPE data add clinical depth in paediatric hypothalamic obesity but do not change the near term reality of a company still reporting losses with heavy R&D and SG&A spending.
In the short term, the key swing factor remains regulatory and reimbursement progress for new setmelanotide indications like acquired hypothalamic obesity. The biggest risk is still concentration in one drug, combined with the possibility that continued cash burn leads to future capital raises that dilute shareholders if revenue traction lags expectations.
The most relevant update is the real world French early access analysis in paediatric acquired hypothalamic obesity. Over up to 18 months of setmelanotide therapy, 30 children showed mean BMI reductions in the low double digits, with more than 88% achieving at least a 0.2 point BMI z score improvement and 100% reaching that threshold at 12 and 18 months.
Those outcomes, together with Phase 3 data showing larger composite metabolic index shifts versus placebo, strengthen Rhythm Pharmaceuticals’ operational story as it seeks approvals, payer backing and broader guideline inclusion. The data also speak directly to payer questions around cardiometabolic risk, which sits alongside execution on international launches as a practical catalyst for the business.
Rhythm Pharmaceuticals' current analyst narrative points to revenues of US$971.3 million and earnings of US$263.4 million by 2029. That profile sits alongside an assumed 64.8% yearly revenue growth rate and an earnings swing of about US$471.2 million from today’s loss of US$207.8 million to the 2029 consensus figure.
Uncover how Rhythm Pharmaceuticals' fair value indicates a 33% potential upside to its current price that may not last much longer.
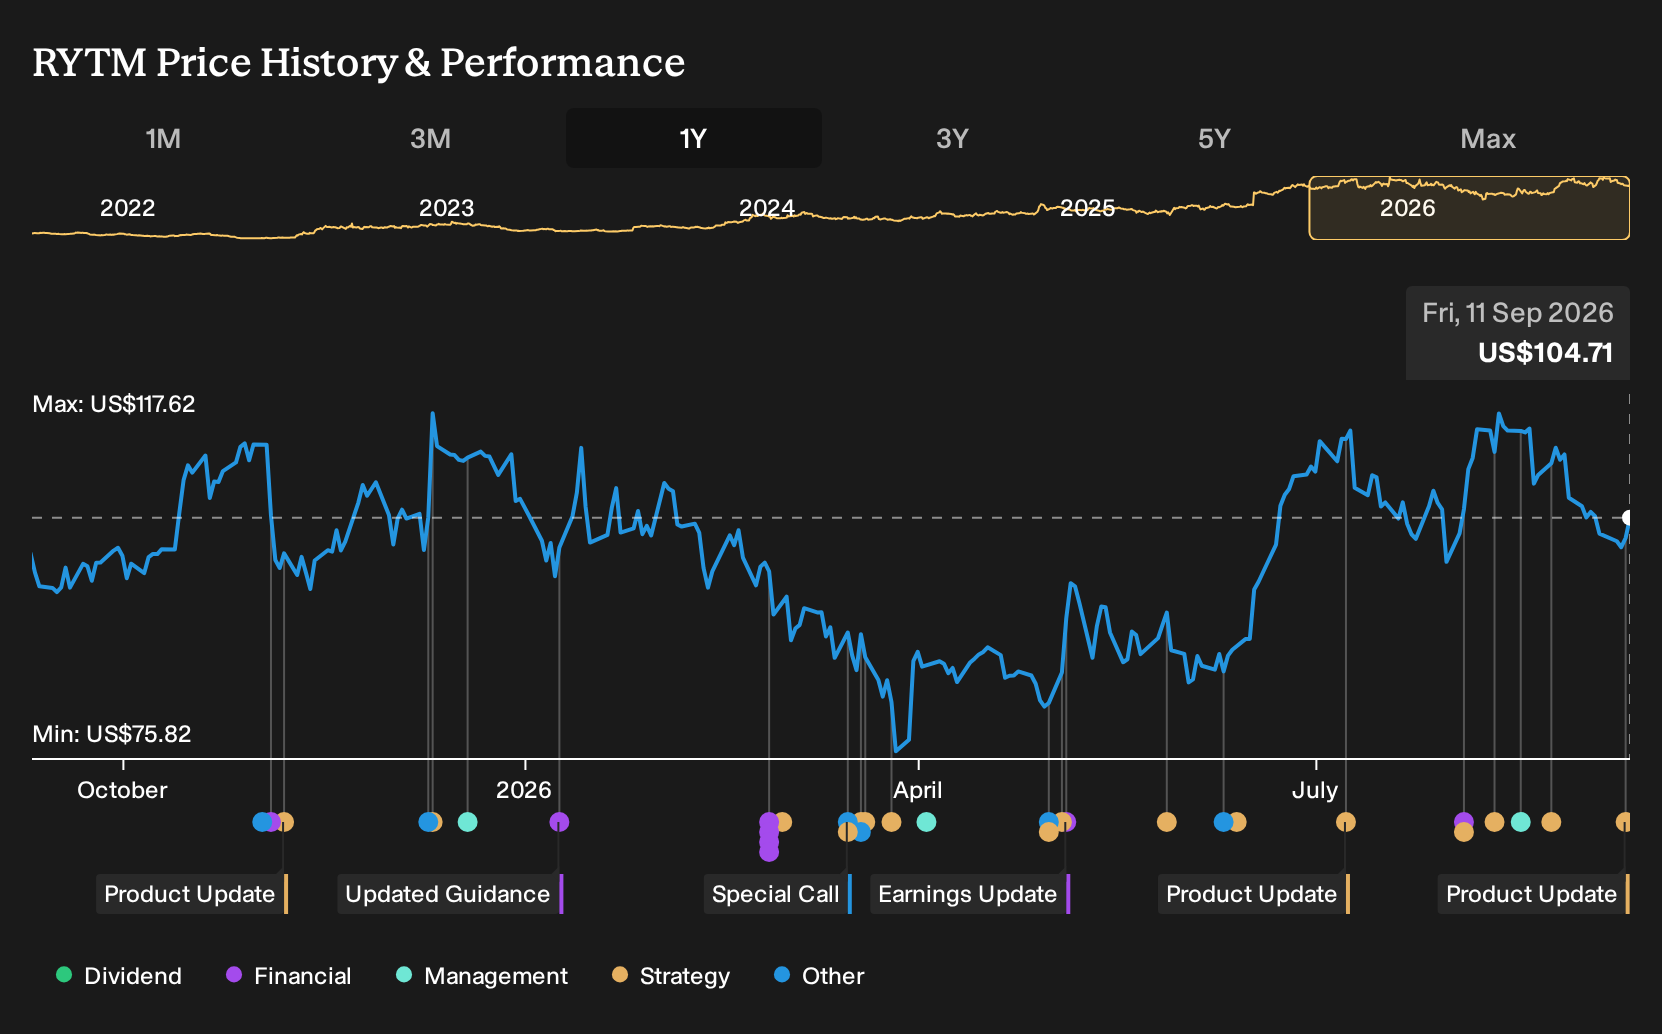
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span a wide range, from US$134 to about US$470, which already shows how far opinions on Rhythm Pharmaceuticals can spread. Those views do not yet factor in the recent ESPE data or future regulatory calls. Use them as starting points and compare several alternative takes before deciding how this story fits your own risk tolerance.
Explore 2 other Rhythm Pharmaceuticals fair value estimates, including one that suggests as much as 348% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Rhythm Pharmaceuticals research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Rhythm Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rhythm Pharmaceuticals' overall financial health at a glance.
Looking For More Investment Ideas Beyond Rhythm Pharmaceuticals?
If Rhythm Pharmaceuticals has sharpened your interest in focused, data heavy stories, it can be useful to line it up against other opportunities that fit your risk profile and income goals. The Simply Wall St Screener lets you do that in a structured way, filtering for quality, balance sheet strength, or income potential so you are not relying on a single ticker to carry your thesis.
- If you want resilience first and performance second, consider scanning a curated list of 11 resilient stocks with low risk scores that aim to keep downside in check while still leaving room for upside.
- For investors hunting for quality at a sensible entry point, sift through 32 high quality undervalued stocks that combine solid fundamentals with prices that may not fully reflect their underlying metrics.
- Income focused readers who care about regular cash returns can review 6 dividend fortresses that pair higher yields with an emphasis on sustainability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com