


Elemental Royalty (TSX:ELE) just secured a spot in the MVIS Global Junior Gold Miners Index, the benchmark tracked by the VanEck Junior Gold Miners ETF, which puts the royalty company directly on more institutional radars.
Recent trading has been supportive, with Elemental Royalty’s 90-day share price return of 26.91% and year to date share price gain of 37.10% pointing to building momentum. The 3-year total shareholder return of 150.57% reflects a strong longer term payoff for investors who stayed invested.
Spot 35 elite gold producer stocks that could see a similar visibility boost if index inclusion or renewed attention starts to channel more institutional money into junior producers.Elemental Royalty’s rally and index debut have pulled the share price closer to analyst targets, yet a gap remains to some fair value estimates. How much of that upside is already in the CA$29.71 print?
Preferred Price-to-Sales of 19.4x: Is it justified?
Elemental Royalty now trades at a P/S ratio of 19.4x, which appears high relative to its CA$29.71 share price when compared with peers and broader industry norms.
The P/S metric compares the company’s market value to its revenue. For a royalty-focused miner like Elemental Royalty, investors often look at this ratio to gauge how much they are paying for each dollar of current sales when earnings can be noisy due to one off items or deal activity.
In this case, the stock carries a much richer P/S level than both the Canadian Metals and Mining industry average of 5.6x and the peer group average of 6.7x. It also sits above an estimated fair P/S ratio of 15.1x. This points to a valuation that could have room to compress if sentiment or growth expectations cool.
Explore the SWS fair ratio for Elemental Royalty.
Result: Price-to-Sales of 19.4x (OVERVALUED)
Still, Elemental Royalty’s rich P/S and fair value discount could unwind quickly if revenue momentum stalls or if sentiment in the gold sector turns against junior royalty stocks.
Find out about the key risks to this Elemental Royalty narrative.
Another View on Elemental Royalty’s Value
The SWS DCF model presents a very different perspective on Elemental Royalty. At a CA$29.71 share price, the stock is highlighted as trading about 78.6% below an estimated fair value of CA$139. This indicates a substantial gap between the model’s cash flow assumptions and the price the market is willing to pay today.
Look into how the SWS DCF model arrives at its fair value.
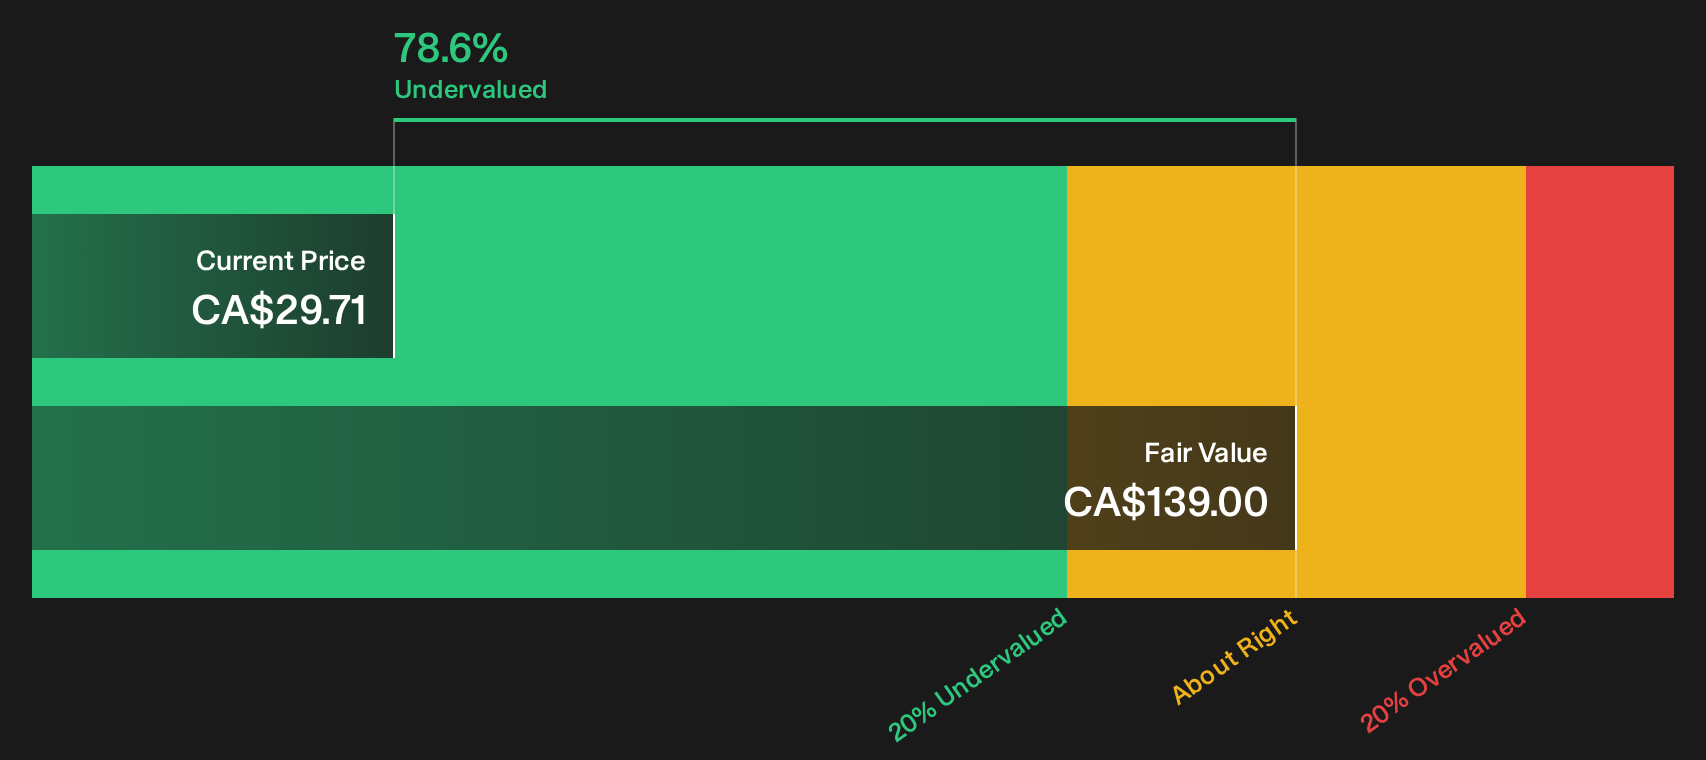
This raises a key question for anyone tracking Elemental Royalty. Is the market appropriately skeptical of those cash flow forecasts, or is short term enthusiasm around the index inclusion still underestimating the longer term royalty stream potential?
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Elemental Royalty for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Elemental Royalty’s valuation and risk profile can feel confusing at first glance, so move quickly, check the underlying numbers yourself, then weigh the 2 key rewards and 3 important warning signs.
Looking for more Elemental Royalty style investment ideas?
If Elemental Royalty has sharpened your focus on quality and price, do not stop here. Use the Simply Wall St screener to quickly surface other ideas that fit clear, disciplined criteria before the crowd turns its attention there.
- Target potential mispricing by scanning a curated 5 high quality undervalued stocks that combine quality fundamentals with what may be discounted market expectations.
- Strengthen portfolio resilience by focusing on businesses with robust finances through a list of solid balance sheet and fundamentals (7 results) that helps you avoid weak capital structures.
- Review a 9 high quality undiscovered gems that screens for quality metrics before wider attention builds.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com