


Oil just became the story again, as drone attacks on Saudi infrastructure, shipment risks around key sea lanes and already tight production stirred fresh anxiety about supply and inflation. That kind of shock can quickly reshuffle winners and laggards across global integrated oil and gas producers. This article unpacks that shift and walks through 3 stocks exposed to this news, to help you decide which deserve a closer look.
The three integrated oil and gas producers highlighted below are only a sample, since the full screen surfaced 13 more companies with equally compelling narratives that are not covered in this article. To identify and analyze those additional candidates with the highest conviction potential among large integrated energy players, head straight to the Global Integrated Oil & Gas Producers screener.
China Aviation Oil (Singapore) (SGX:G92)
China Aviation Oil (Singapore) is a jet fuel trader and supplier linked to global integrated energy flows, with about $14.0b from Middle Distillates and $1.7b from Other Oil Products, and a market value of roughly S$1.2b.
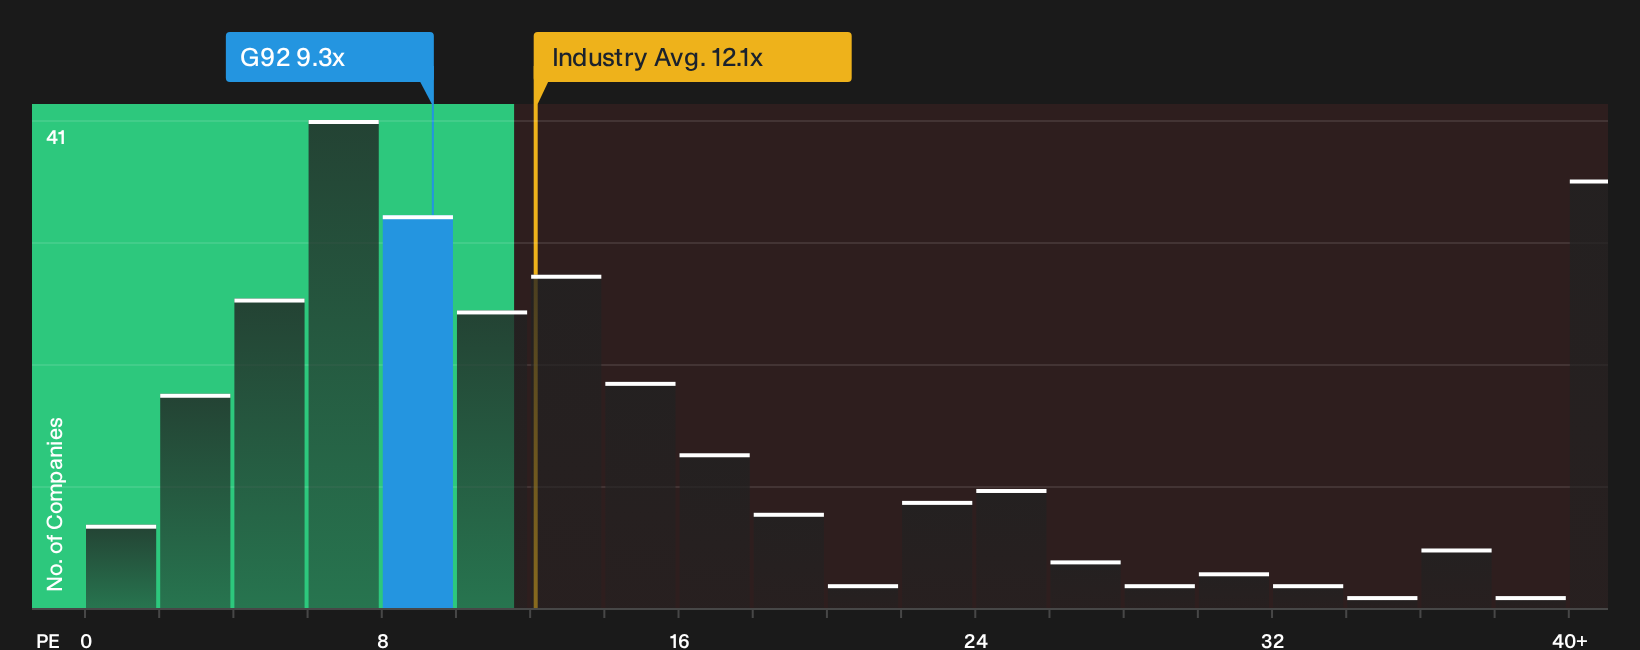
China Aviation Oil (Singapore) provides focused exposure to aviation fuel within a large-cap energy universe, combining a P/E of about 9.3x and net margins around 0.6% with exposure to global jet fuel pricing. One key issue ahead is how aviation demand will interact with an unresolved pressure on fuel spreads.
To see how those fuel spreads feed into valuation and risk, review the 5 key rewards and 1 important warning sign to understand what might be masking the next inflection.
Tidewater Renewables (TSX:LCFS)
Tidewater Renewables focuses on low carbon fuel production within a broader integrated energy value chain, turning policy driven demand for cleaner transport fuels into a different earnings engine than traditional crude producers.
Tidewater Renewables generates about CA$370.9 million from renewable energy products, including renewable diesel and hydrogen from its Prince George complex, and has a market value near CA$706 million.
When oil supply shocks push up conventional fuel margins and raise inflation risks, Tidewater Renewables gives you exposure to a cleaner side of the energy system that still plugs into refinery economics and compliance markets.
"The rapidly tightening global carbon credit markets, highlighted by unexpectedly strong LCFS and CFR credit prices into 2026 and beyond, as mentioned by management, set the stage for multiple years of potential windfall high-margin compliance credit revenue, creating major upside to net earnings not properly captured by current models."
What happens to Tidewater Renewables if a single pressure point in that policy driven revenue mix shifts direction faster than expected.
If that pressure point is what you are watching, the full narrative for Tidewater Renewables shows where Tidewater Renewables could accelerate or stall as policy, credits and projects shift.

Hess Midstream (HESM)
Hess Midstream taps into the Global Integrated Oil & Gas Producers theme through its role as a large US midstream operator, earning about $858 million from Gathering, $614 million from Processing and Storage, and $142 million from Terminaling and Export, on a roughly $8.2b market cap.
In a world where oil flows and shipping routes suddenly look less predictable, Hess Midstream provides exposure to the pipes, plants and terminals that keep barrels moving, with the core appeal centered on the visibility of its cash flows.
"Multi-year minimum volume contracts with Hess Corp (now under Chevron), providing highly predictable, inflation-resistant fee-based revenue streams through the late 2030s, which supports stable adjusted EBITDA and consistent dividend/distribution growth."
What ultimately matters is how one quiet shift in the balance between payout ambitions and balance sheet pressure shapes those future distributions.
That balance can shift faster than it looks, and the full narrative for Hess Midstream reveals how Hess Midstream’s payout ambitions, contracts and capital plans could be accelerating or quietly stalling.

Seeking Alternatives Before The Crowd
Fresh opportunities often move from quiet to crowded in a single news cycle. Spot the next breakout or quietly dropping laggard while it still matters and act now.
- Track where resilient balance sheets meet real momentum by scanning the curated list of solid balance sheet and fundamentals (194 results) before those stories stop flying under the radar.
- Hunt for cash generating AI leaders with real businesses, not just hype, using the focused 74 profitable AI stocks that aren't just burning cash while sentiment remains under the radar for now.
- Consider potential income opportunities by checking the high yield 162 dividend fortresses before any change in demand affects today’s entry yields.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com