


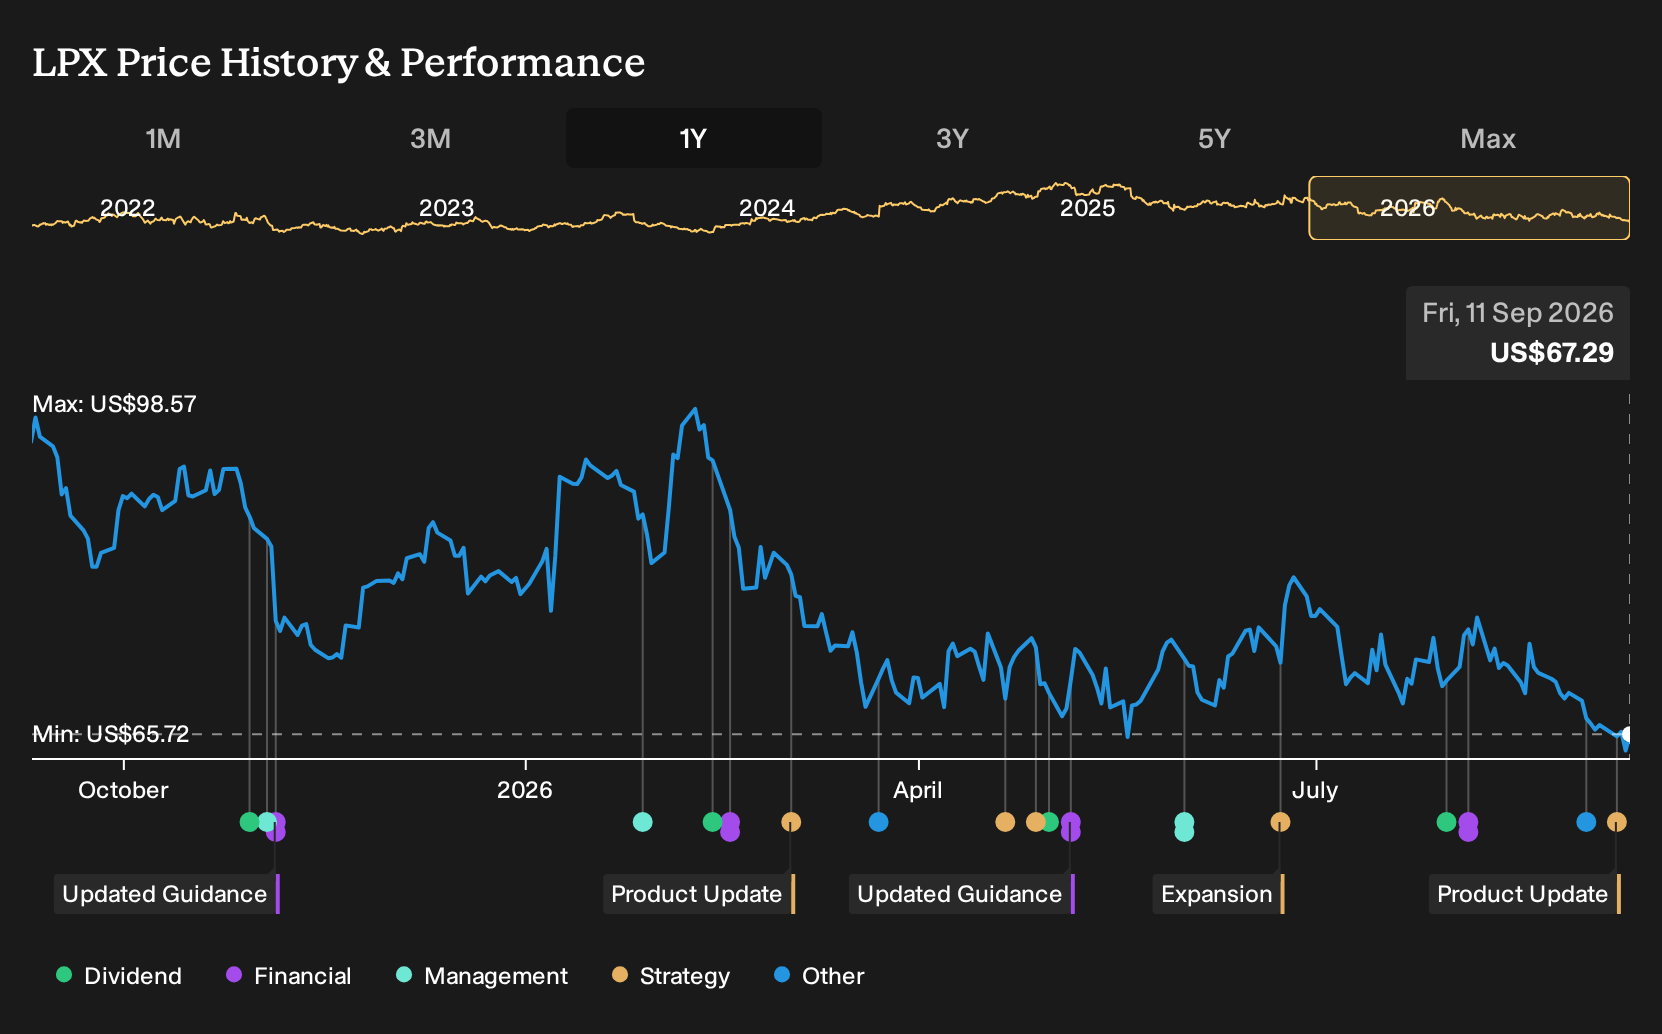
- Louisiana-Pacific recently broadened its LP SmartSide Trim & Siding line with a new 8-inch brushed smooth shake lap product and separately decided to indefinitely curtail OSB production at its Jasper, Texas mill from October 2026 in response to soft demand.
- This combination of adding higher value siding options while idling a 475 million square foot OSB facility highlights how management is actively shifting its footprint toward areas of steadier demand and potentially different margin profiles.
- Next, the focus turns to how Louisiana-Pacific's push into refined siding profiles alongside the Jasper OSB curtailment could influence the investment narrative.
Louisiana-Pacific Investment Narrative Recap
Owning Louisiana-Pacific means believing that demand for engineered wood siding and related building solutions remains a durable theme across new construction and remodeling, despite swings in housing activity. The recent SmartSide product expansion and the planned Jasper OSB curtailment together point to a business leaning harder into siding while keeping a tight grip on capacity where pricing is weaker.
For the near term, the key swing factor is how quickly higher margin siding can offset earnings pressure from low OSB profitability and softer volumes. The biggest watchpoint is still end market demand for single-family housing and repair and remodel activity. These announcements do not materially change that core risk, but they do shape how Louisiana-Pacific is exposed to it.
The clearest operational hinge today is the decision to indefinitely curtail OSB output at Jasper starting October 2026. A 475 million square foot mill stepping back reduces exposure to structurally weak OSB pricing that has already pushed that segment into negative EBITDA, while keeping the option to restart if conditions improve.
For catalysts, investors are likely to track whether this tighter OSB footprint, combined with steady SmartSide portfolio expansion, helps stabilize margins and smooth earnings volatility over time. Execution will come down to how efficiently Louisiana-Pacific reallocates capital and overhead away from curtailed capacity and into siding, where product breadth, mix, and penetration into repair, remodel, and manufactured housing remain central to the story.
Louisiana-Pacific's current analyst blueprint points to revenues of US$3.1b and earnings of US$462.5m by 2029, based on an assumed 6.2% yearly increase in sales and an earnings rise of about US$380.5m from US$82.0m today.
Uncover why Louisiana-Pacific's fair value indicates a 36% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Louisiana-Pacific leans hard into climate and regulation risk. Those analysts were already pencilling in about US$2.9b of revenue and US$412.2m of earnings by 2029, yet still set a lower US$78.81 fair value. You can read that as a warning that new siding launches and the Jasper decision might later force sharper narrative revisions.
Explore 2 other Louisiana-Pacific fair value estimates, including one that suggests as much as 77% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Louisiana-Pacific research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Louisiana-Pacific. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Louisiana-Pacific's overall financial health at a glance.
Looking For More Investment Ideas Beyond Louisiana-Pacific?
If the Louisiana-Pacific story has you thinking about where else capital could work hard for you, the Simply Wall St Screener can help you quickly surface other listed businesses with very different risk and reward profiles.
- For investors who want quality at a reasonable entry point, start by reviewing a 32 high quality undervalued stocks that combine solid fundamentals with prices that analysts view as below intrinsic value.
- If reliability and capital preservation matter most to you, scan a 11 resilient stocks with low risk scores that score well on financial strength and business stability.
- For those hunting for future leaders before the crowd pays attention, sift through a 15 high quality undiscovered gems that pair strong underlying metrics with relatively low visibility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com