


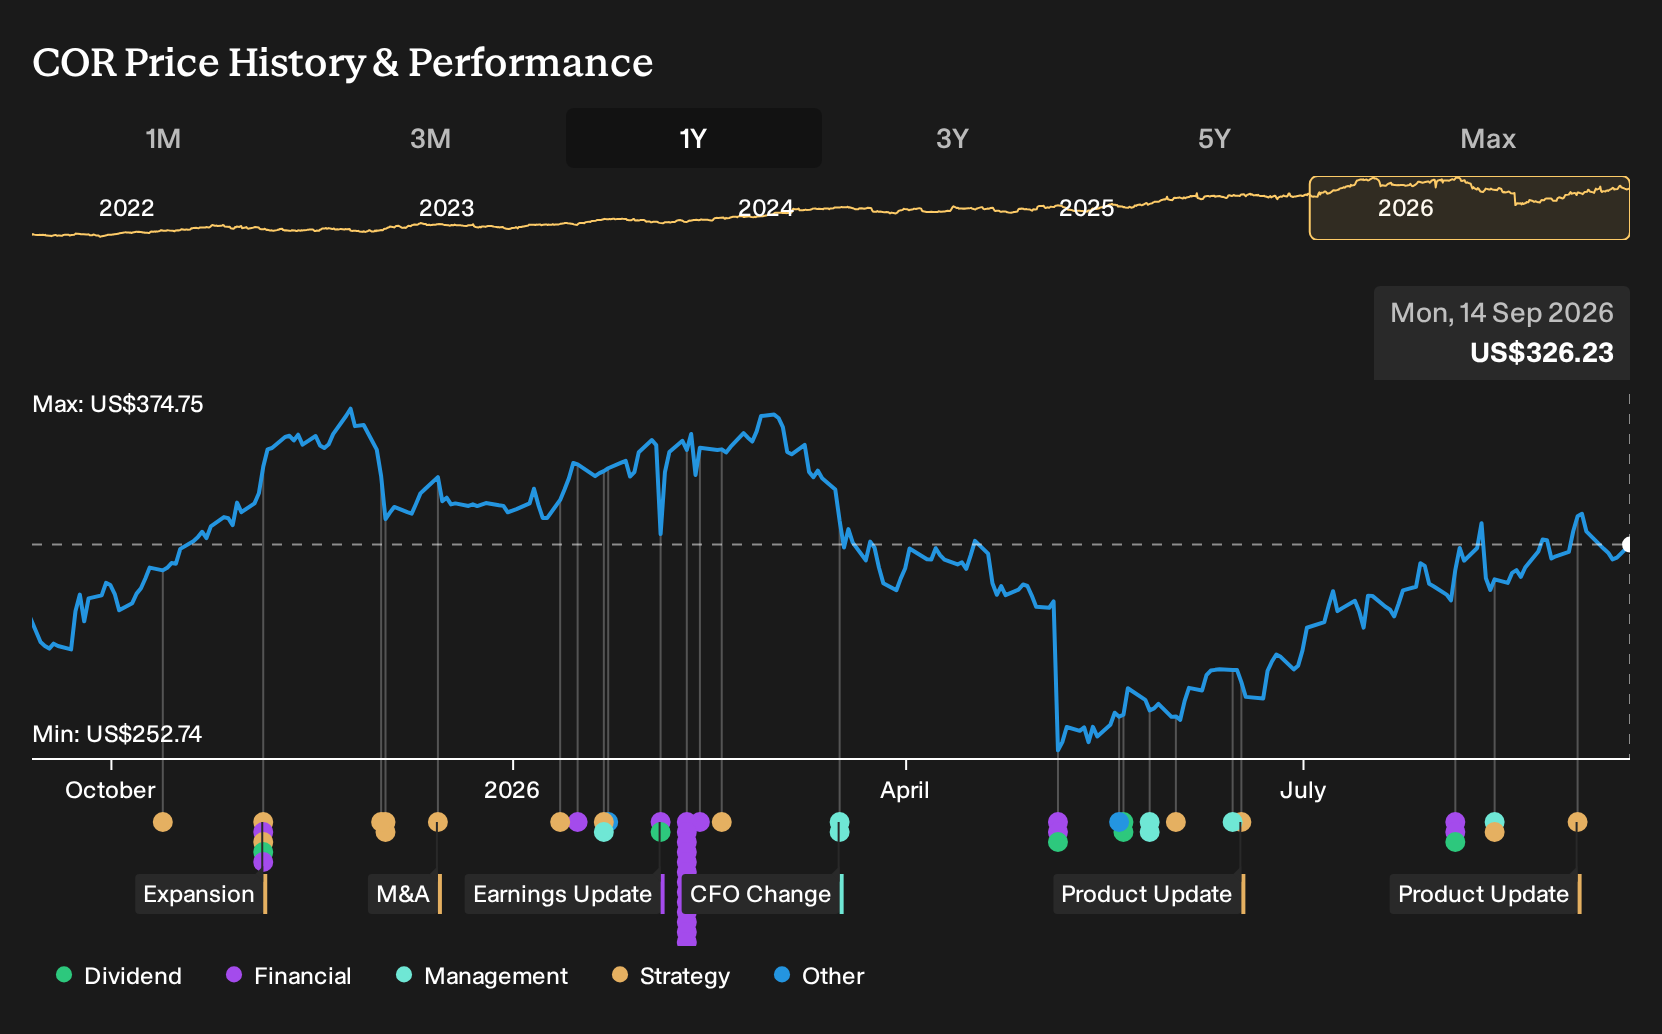
- Cencora, through its Accelerate Pharmacy Solutions unit, recently introduced a Cell and Gene Therapy Enablement service to help health systems assess, build and scale programs for advanced therapies, covering financial planning, operational readiness and scalable growth support.
- The launch targets a clear operational gap, as only 4% of surveyed health system pharmacy leaders reported full readiness for cell and gene therapies despite more than 35 FDA approved CGTs and over 1,700 clinical trials worldwide.
- This development could influence how investors view Cencora's positioning in higher value pharmacy services.
Cencora Investment Narrative Recap
To be comfortable as a Cencora shareholder, you need to believe the company can keep tilting its huge drug distribution engine toward higher margin specialty and services. The cell and gene therapy enablement launch fits that direction, but on its own does not look big enough to move near term earnings. The more immediate swing factor remains execution on specialty services while generics and biosimilars keep squeezing fees.
The biggest current risk is that mix shift does not move fast enough to offset modest forecast revenue growth of about 5% a year and pressure from lower fee categories and international softness. Any signal that specialty logistics or consulting stays weak could matter more in the short run than this one new offering.
The cell and gene therapy enablement service is the clearest recent announcement to focus on. It plugs directly into Cencora’s higher value services push, using Accelerate Pharmacy Solutions to advise on finance, operations and repeatable workflows. That ties back to the long term margin story investors are watching.
For catalysts, investors will likely listen closely to the Wells Fargo healthcare conference on September 8, 2026 for early signs of demand, pricing and uptake around this service. Concrete metrics on contracted health systems, scope of engagements or cross selling into Cencora’s specialty distribution stack would help gauge whether this is a needle mover or mainly reputational for now.
Cencora's current narrative points to revenues of US$394.5b and earnings of US$3.4b by 2029, built on analyst assumptions of 5.8% yearly revenue growth and an earnings increase of about US$0.8b from US$2.6b today.
Uncover why Cencora's fair value indicates a 14% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the lowest Cencora forecasts lean hard into execution risk around complex therapies. Those analysts were penciling in only 3.8% annual revenue growth to about US$372.4b and earnings of roughly US$3.3b by 2029. You can read this as a more cautious story that might shift after the cell and gene launch and the upcoming Wells Fargo appearance.
Explore 2 other Cencora fair value estimates, including one that suggests it could be worth just $370.92.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Cencora research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Cencora. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cencora's overall financial health at a glance.
Looking For More Investment Ideas Beyond Cencora?
If the Cencora story has you thinking about portfolio upgrades, it can help to scan a wider field of financially solid opportunities using the Simply Wall St Screener.
- For investors who want income that can potentially keep up with inflation, consider shortlisting companies with reliable payouts by reviewing 6 dividend fortresses.
- If capital preservation and steadier returns matter most to you, narrow your search to businesses with stronger balance sheets and lower risk scores through 11 resilient stocks with low risk scores.
- When you want quality at a price that still looks reasonable on fundamentals like cash flows and balance strength, start with a focused set of 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com