


DPC Holdings shares have retreated in recent weeks, which puts a fresh spotlight on whether the current valuation still lines up with what the business generates in sales. With the stock under pressure, the key issue for you is how much revenue the market is choosing to pay for.
- The share price is down 20.2% over the past month, which puts more weight on the question of whether the price you see today is supported by the company’s sales base.
- The recent debt refinancing that introduced a US$325m unsecured senior revolving credit facility may support liquidity and could ease interest costs, which can influence how investors think about the value of each dollar of revenue.
- The analysts covering DPC Holdings have run their own numbers. See what analysts think DPC Holdings's shares could be worth.
The issue now is whether the multiple of sales implied by the current DPC Holdings share price looks sensible when set against the industry average.
If you want to test the same sales-based valuation question across a broader set of companies, take a look at 35 high quality undervalued stocks
Is DPC Holdings Getting Expensive on Sales?
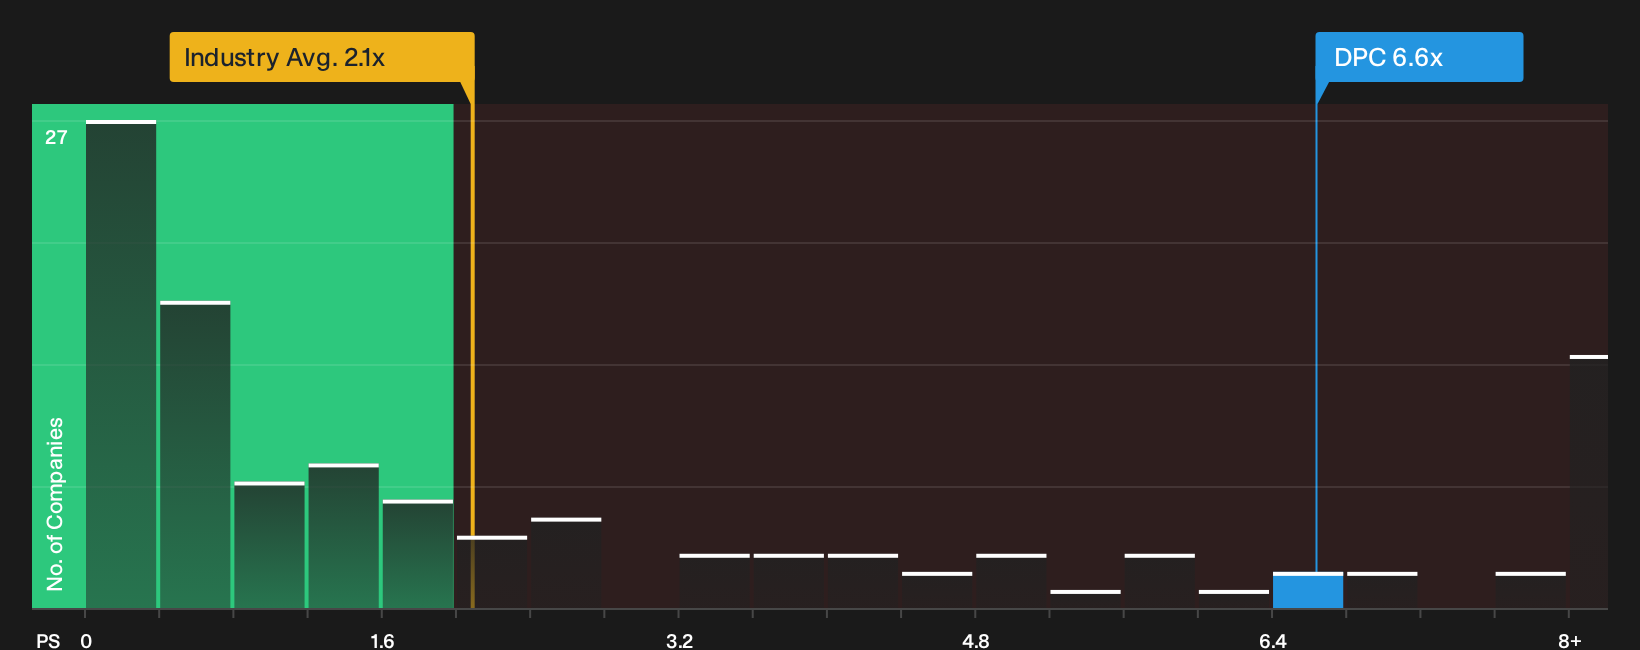
P/S works well for DPC Holdings because the business is being judged heavily on its ability to turn revenue into future cash flows rather than current earnings. On this measure, the stock trades on a P/S of 6.3x, against an Electrical industry average of 2.1x and a peer group around 10.8x. That puts DPC well above the broader sector on sales, even if it still comes in lower than some closer comparables.
The recent US$325m revolving credit facility gives the group more room to fund operations. Yet despite that balance sheet support, the share price still values each dollar of revenue at a steep premium to the wider industry. For you as a shareholder or potential buyer, that gap suggests the market is already paying up for DPC Holdings on a simple sales basis and leaves less room for error if growth or margins disappoint relative to what is currently implied. Explore the numbers behind DPC Holdings's P/S valuation.
The DPC Holdings Narrative: What Would Justify Today's Price?
DPC Holdings' valuation puzzle points straight to Simply Wall St Narratives, which sit on the Community page and spell out what kind of growth, margins and earnings profile would need to hold for the stock to trade meaningfully above or below today's price. Each one treats fair value as a thesis about the business that can be tracked over time rather than as a one-off snapshot, so you can see how that story holds up as fresh information arrives.
One of the top community narratives on DPC Holdings: 34% undervalued
"Multi year customer partnerships with major aerospace and IGT OEMs, including four long term agreements representing an estimated US$200 million plus potential annual revenue…"
Discover why this Narrative puts DPC Holdings at 34% undervalued.
DPC Holdings’ valuation still leaves one powerful lever in the background
Big numbers only tell part of the story, because the people steering DPC Holdings and the way they are rewarded can tilt the risk and reward profile in a very different direction. See who runs DPC Holdings and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com