


Unusual Machines has seen its stock swing sharply over the past year, which puts fresh focus on a simple question for investors. Is the current share price grounded in what the business is generating in sales today, especially as it pushes further into AI driven unmanned systems?
- Over the past 12 months the stock has gained 106.9%, which puts a lot of weight on whether that move is supported by the revenue base the company is building.
- The US$20 million follow on investment in XTEND AI Robotics and the work with Altana on supply chain intelligence can shape how quickly Unusual Machines converts its drone ambitions into sales and how capital hungry that journey might be.
- The analysts covering Unusual Machines have run their own numbers. See what analysts think Unusual Machines's shares could be worth.
The issue now is whether Unusual Machines' current share price can be justified by its sales when lined up against the Fair Ratio benchmark.
If you want to test this same sales based valuation question across a wider set of AI focused names, scan through the 32 AI small caps.
Has Unusual Machines Run Too Far on Sales?
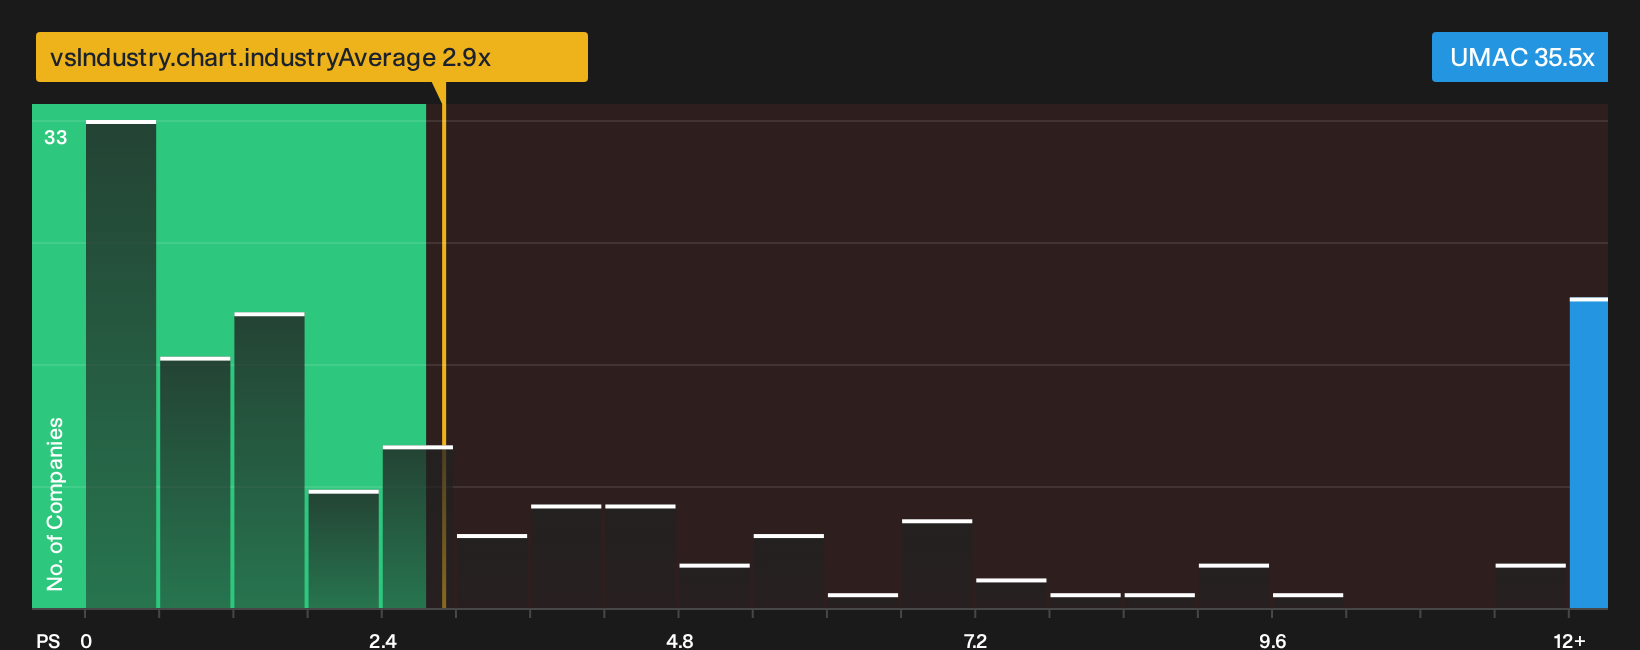
P/S tends to matter most for a business like Unusual Machines that is still building towards consistent profits. In this context, the stock trades on a P/S of 35.5x, which is far above the Electronic industry average of 2.9x and well ahead of the peer group on 19.4x. That is a rich revenue tag for any early stage AI and unmanned systems player, so investors need to be confident that the current sales base is only a small fraction of what management can eventually deliver.
The Fair Ratio framework, which adjusts the P/S multiple for Unusual Machines' growth profile, margins, size and risk, flags the current valuation as overvalued and with a very wide gap to what the model views as reasonable. The model is heavily marking down the stock because of its loss making free cash flow and risk profile, so this reading is better seen as a warning that the shares screen very expensive on sales rather than a precise target. Despite the extra US$20 million going into XTEND AI Robotics and the Altana partnership lifting interest in the story, the present P/S still assumes a lot from future revenue delivery. Explore the numbers behind Unusual Machines's P/S valuation.
The Unusual Machines Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for Unusual Machines' P/S leaves off by explaining what would need to happen to growth, margins and earnings for the stock to be worth materially more or less than today's price, and they sit on the platform's Community page. Each narrative turns that fair value view into a thesis about the business that you can watch over time rather than treating it as a one off snapshot.
Community views on Unusual Machines are sharply split, with one camp seeing material upside and the other flagging extreme optimism in the current pricing.
Bull case: 42% undervalued
"A strengthened balance sheet, with over $80 million in cash and no debt, allows Unusual Machines to aggressively pursue strategic acquisitions…"
Discover why this Narrative puts Unusual Machines at 42% undervalued.
Bear case: 1334% overvalued
"Historically, UMAC’s stock has been highly sensitive to news flow, surging on major contract disclosures and facing declines when earnings or meetings encountered issues…"
Explore why this Narrative puts Unusual Machines at 1334% overvalued.
One more angle on Unusual Machines that deserves a closer look
There is a separate set of checks on Unusual Machines that highlights potential pressure points for the business, and those signals are worth weighing alongside any view on price. Take a closer look at 3 warning signs (2 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com