


Why Williams Companies’ new bond deal matters for equity investors
Williams Companies (WMB) just closed a multi tranche bond sale totaling US$2.75b in senior unsecured notes. That fresh debt financing is the starting point for thinking about the stock today.
Recent trading has cooled a bit, with the share price down 4.3% over the past month and 3% over the last week, even as Williams Companies still shows an 18.2% year to date share price gain and a 26.9% total shareholder return over twelve months. This points to strong longer term momentum despite near term consolidation around the new bond issuance.
Scan how Williams Companies’ bond move compares with peers by lining up other energy infrastructure stocks that pass our 11 resilient stocks with low risk scores filter for balance sheet strength and resilience.
The bond sale has reset the debate around Williams Companies at US$71.95 a share. Is this pullback already the better entry, or does patience still offer more value on the table?
Most Popular Narrative: 16% Undervalued
Williams Companies is trading at $71.95 against a widely followed fair value estimate of $85.25. This frames the new bond deal as part of a bigger equity story built around power and data center demand.
The U.S. is continuing its rise as a global LNG export leader; Williams' direct connectivity to LNG export terminals and scheduled capacity expansions position it to capture a disproportionate share of throughput gains in this segment, boosting long-term EBITDA and cash flow stability through fully contracted projects. Widespread electrification (AI/data centers, power generation switching to gas), paired with underinvestment and delays in new competing infrastructure, is causing system constraints and peak demand across Williams' existing assets. This supports higher pipeline utilization, pricing power, and margin improvement.
See why 26 investors see Williams Companies as 16% undervalued.
Result: Fair Value of $85.25 (UNDERVALUED)
Still, the Williams Companies story can be knocked off course if decarbonization policies curb long term gas demand, or if permitting and construction delays drag on major projects.
Find out about the key risks to this Williams Companies narrative.
Another View on Williams Companies’ valuation
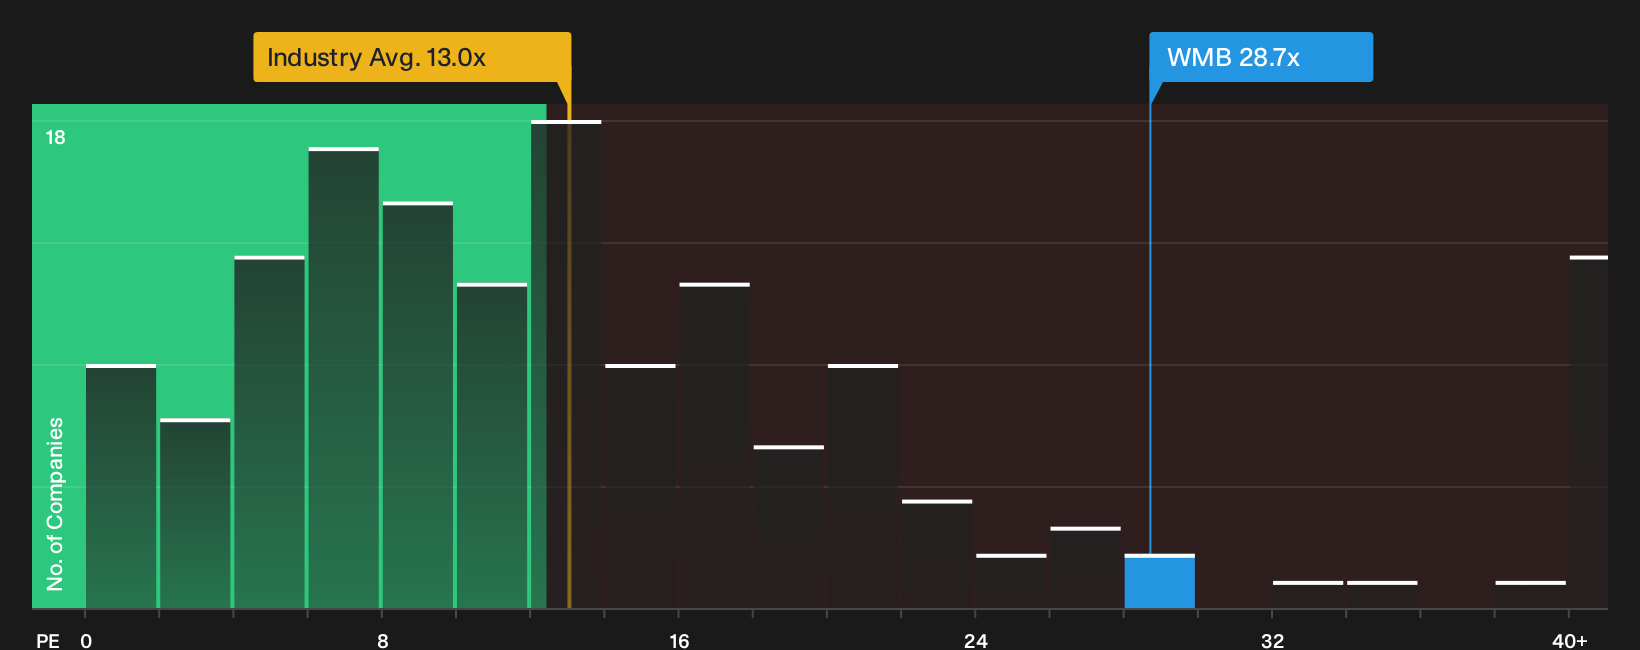
The underpriced narrative around Williams Companies looks very different once the focus shifts to earnings multiples. The stock trades on a P/E of 28.7x, which is far above both the US Oil and Gas industry average of 13.0x and the peer average of 15.2x.
Simply Wall St’s fair ratio work suggests a P/E of 26.7x as a level the market could move towards, so current pricing implies investors are already paying extra for the story. That premium can reward patience if the upbeat scenario plays out, but it can also magnify disappointment if growth or returns come in softer than expected.
For anyone weighing the bond fueled upside case against this richer multiple, the key consideration is how much P/E compression risk feels acceptable at $71.95 a share.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this Williams Companies story points in opposite directions, with fresh debt on one side and valuation debate on the other, so move quickly and pressure test the narrative against the numbers that matter most to you. To balance the optimism and the concerns before you act, start by weighing the 3 key rewards and 3 important warning signs.
Looking for more ideas beyond Williams Companies?
If Williams Companies has you thinking harder about risk, return, and timing, this can be a good moment to widen your watchlist before the next move in the market.
- Target potential mispricing opportunities by scanning companies that appear attractively valued on cash flow and quality screens with the 35 high quality undervalued stocks.
- Strengthen the income side of your portfolio by focusing on resilient payers using the 6 dividend fortresses.
- Upgrade portfolio resilience by filtering for businesses with strong finances and durable fundamentals through the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com