


- Match Group reported a product-led turnaround with adjusted EBITDA up 14% and net income up 36% year over year, supported by Hinge revenue growth of 22% and expansion across European markets.
- The business combined strong monetization and cost control with capital returns through buybacks and dividends, indicating that management is prioritizing both operational discipline and shareholder payouts.
- Next, the focus shifts to how Match Group's product-led turnaround and cash generation might reshape the existing investment narrative.
Scan beyond Match Group's turnaround and shortlist other cash generative, value driven opportunities using our curated 35 high quality undervalued stocks.
Match Group Investment Narrative Recap
An investor in Match Group needs to believe that product execution across Tinder, Hinge and the broader portfolio can stabilize user trends and keep payers engaged, while the group continues to convert that engagement into cash. The latest print, with higher adjusted EBITDA and net income, supports that operating case but does not remove the risk that Tinder metrics remain under pressure.
In the near term, the key catalyst still sits with visible traction from feature launches and international rollouts, especially at Tinder and Hinge. The biggest risk remains user fatigue and rising competition from free or AI-driven dating options, which could erode pricing power even if the current product-led turnaround stays on track.
The recent confirmation that Match Group remains highly cash generative, with strong free cash flow backing both buybacks and dividends, is the announcement that ties most directly to this turnaround story. It shows the business funding product work and shareholder distributions from operations rather than relying on new equity.
Regarding catalysts, that level of cash production gives management room to keep investing in AI features, trust and safety tools, and alternative payment channels, while still returning capital. The flip side is that high leverage and negative equity mean balance sheet risk does not disappear. Execution on new products and continued cash conversion need to stay tight for this setup to remain attractive.
Match Group's current analyst narrative points to US$4.0b in revenue and US$860.9m in earnings by 2029, based on an assumed 4.2% yearly uplift in revenue and an earnings increase of about US$153m from US$707.8m today.
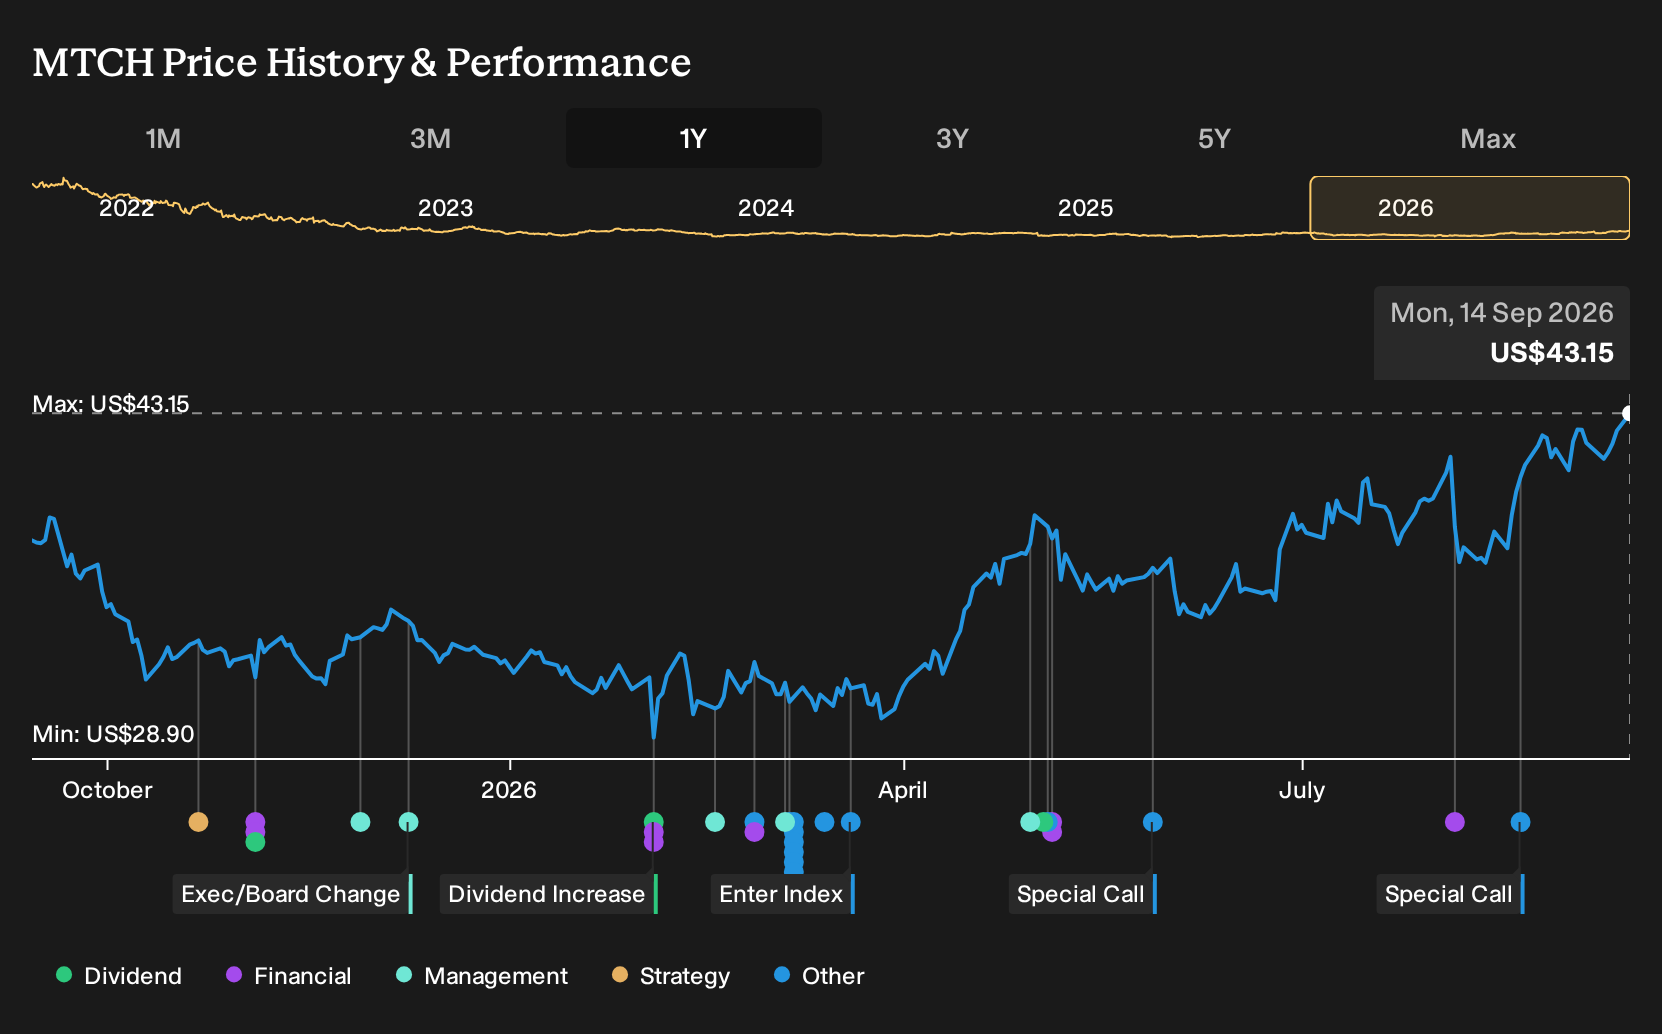
Uncover why Match Group's fair value points to a 3% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One alternate view on Match Group leans heavily on the risk that Tinder engagement keeps sliding. Those analysts were pencilling in slower revenue progress to about US$3.8b and earnings of roughly US$761.7m by 2029, well below consensus. That is a much harsher story. Use this earnings gap to test your own expectations, and watch how forecasts shift after this update.
Explore 4 other Match Group fair value estimates, including one that suggests the potential for as much as 20% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Match Group research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Match Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Match Group's overall financial health at a glance.
Looking For More Ideas Beyond Match Group?
If Match Group has sharpened your focus on cash generation and sensible pricing, it can be useful to line it up against other opportunities with similar or contrasting profiles. The Simply Wall St Screener helps you filter the wider market quickly so you can spend time on businesses that actually fit your approach.
- If you prefer quality at a reasonable price, with strong fundamentals underpinning the story rather than just a catchy narrative, then start with our list of solid balance sheet and fundamentals (23 results).
- If resilience and a smoother ride through market swings matter more to you than headline upside, narrow your search using the 11 resilient stocks with low risk scores.
- If you are looking for lesser known companies where strong financials are not yet broadly appreciated, and where the crowd is still catching up, screen for potential opportunities in the 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com