


MERLIN Properties SOCIMI (BME:MRL) continues to draw attention after recent share price pressure, with the stock closing at €12.38 as investors reassess the Spanish real estate group’s valuation and income profile.
The recent 1 month share price return is down 14.68% and the 3 month move is down 18.93%, which suggests some of the earlier momentum in MERLIN Properties SOCIMI is fading. This is occurring even though the year to date share price return is slightly positive and the 3 year total shareholder return of 74.18% and 5 year total shareholder return of 72.30% still point to a much stronger longer term outcome.
Scan how MERLIN Properties SOCIMI compares with other real estate and income-focused plays by reviewing a curated list of 161 dividend fortresses.
Bulls view MERLIN Properties SOCIMI’s recent pullback as a reset after strong multi year returns, while bears interpret it as the start of a longer rerating. Which side does the current valuation evidence support?
Price-to-Earnings of 9x: Is it justified?
On a simple earnings yardstick, MERLIN Properties SOCIMI trades on a P/E of 9x, which looks low beside the recent €12.38 share price and the pressure on the stock over the past few months.
The P/E ratio compares what investors pay today for each euro of current profit. For a real estate investment trust, this gauge helps you see whether the market is attaching a rich or modest tag to its earnings stream, which is especially relevant when the business leans on rent collection and asset management rather than rapid expansion.
Here, the current 9x P/E sits well below a peer average of 15.3x and the European REITs industry average of 13.8x. This signals that investors are pricing MERLIN Properties SOCIMI’s earnings at a clear discount to comparable property groups. Against an estimated fair P/E of 16.9x, the gap is even wider. This suggests that if sentiment were to move closer to that fair ratio level, the valuation could shift meaningfully.
Explore the SWS fair ratio for MERLIN Properties SOCIMI.
Result: Price-to-Earnings of 9x (UNDERVALUED)
Still, MERLIN Properties SOCIMI faces clear risks if sentiment toward European REITs sours further or if commercial tenants push harder on rents and occupancy.
Find out about the key risks to this MERLIN Properties SOCIMI narrative.
Another View on MERLIN Properties SOCIMI’s Value
The earnings multiple presents MERLIN Properties SOCIMI as inexpensive, while the SWS DCF model points to a different picture. On that framework, an estimated fair value of €29.42 compared with a €12.38 share price suggests the stock screens as deeply undervalued on projected cash flows.
That scale of gap raises a practical question for you as an investor: is the market correctly discounting future rental and asset risks, or is sentiment overshooting to the downside and creating a long term mispricing?
Look into how the SWS DCF model arrives at its fair value.
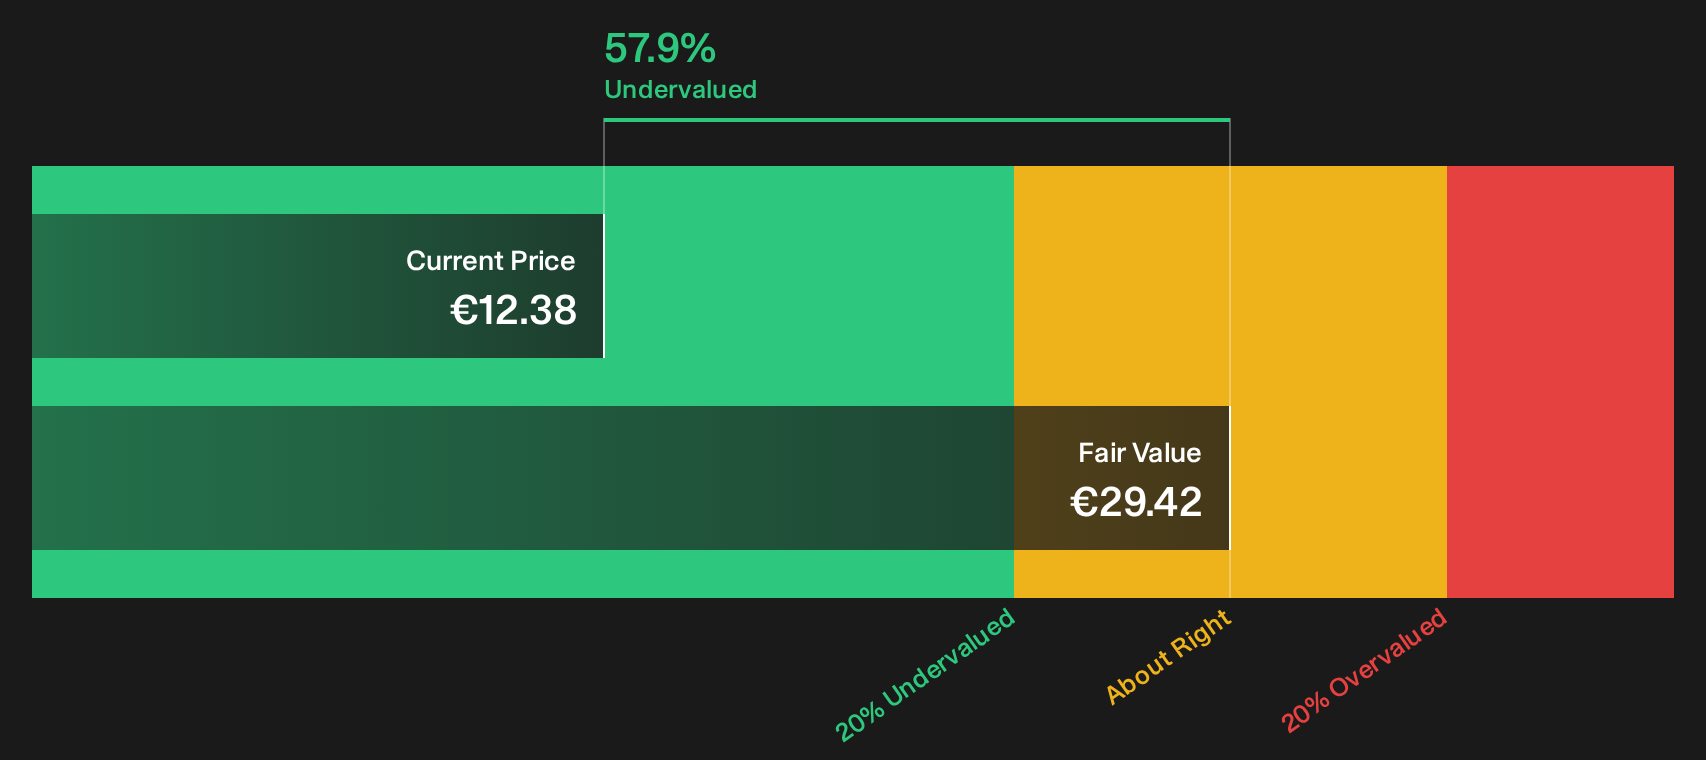
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out MERLIN Properties SOCIMI for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 190 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around MERLIN Properties SOCIMI is clearly mixed. If you care about the full picture, move fast and weigh the evidence yourself, starting with the 5 key rewards and 2 important warning signs.
Looking for more investment ideas beyond MERLIN Properties SOCIMI?
Do not stop with MERLIN Properties SOCIMI. Use this pullback as a prompt to refresh your wider watchlist and line up your next potential opportunities early.
- Target resilient balance sheets by scanning companies on the list of solid balance sheet and fundamentals (194 results) that pair financial strength with room for future decisions.
- Hunt for mispriced quality and use the 190 high quality undervalued stocks to focus on businesses where current pricing looks out of step with fundamentals.
- Spot potential future leaders by reviewing the 618 high quality undiscovered gems and see which quieter stocks already show robust underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com