


- Waste Management recently saw its shares move higher while the broader market dipped, as investors focused on forecasts for quarterly EPS of $2.18 and revenue of $26.35b for the full year.
- The projected 10.1% year over year increase in quarterly EPS, alongside expected 5.34% quarterly revenue growth, highlights how earnings power and underlying demand remain central to the Waste Management story.
- We will look at how Waste Management's investment narrative interacts with the projected 10.1% quarterly EPS uplift now in focus.
Scan how Waste Management's earnings setup compares with other companies showing resilient profitability and demand in our hand picked 35 high quality undervalued stocks.
Waste Management Investment Narrative Recap
For a shareholder in Waste Management, the belief is simple. You want a resilient waste and recycling operator that can keep earnings steady while it invests in technology, renewable energy and healthcare waste services. The latest move higher in the stock, alongside expectations for a 10.1% EPS uplift and 5.34% quarterly revenue growth, keeps that resilience narrative intact.
The key near term catalyst is execution on cost efficiency and integration work, especially after acquisitions like Stericycle and in WM Healthcare Solutions. The biggest risk remains pressure on margins from higher debt, regulation and potential changes to tax credits. The latest earnings expectations do not fundamentally change those swing factors.
With no fresh corporate announcements tied directly to this price move, the most relevant context is management’s ongoing push into technology, recycling and renewable energy projects. These areas already contribute through landfill gas to energy facilities, automated recycling plants and organic waste processing. All of these initiatives tie into the earnings and revenue expectations now in focus.
For catalysts, execution on these sustainability and automation projects is critical. Any delay, cost overrun or regulatory shift around renewable incentives or recycling rules would matter for cash flow and margins, especially given Waste Management’s higher leverage. The market’s reaction to the latest EPS and revenue forecasts reflects how closely investors track that execution risk and opportunity.
Waste Management Earnings Outlook And Valuation Setup
Waste Management's narrative projects revenues of $30.2b and earnings of $4.2b by 2029. This assumes 5.6% yearly revenue growth and an earnings increase of about $1.3b from current earnings of $2.9b.
Discover how Waste Management's fair value points to a 20% potential upside to its current price before the market closes that gap.
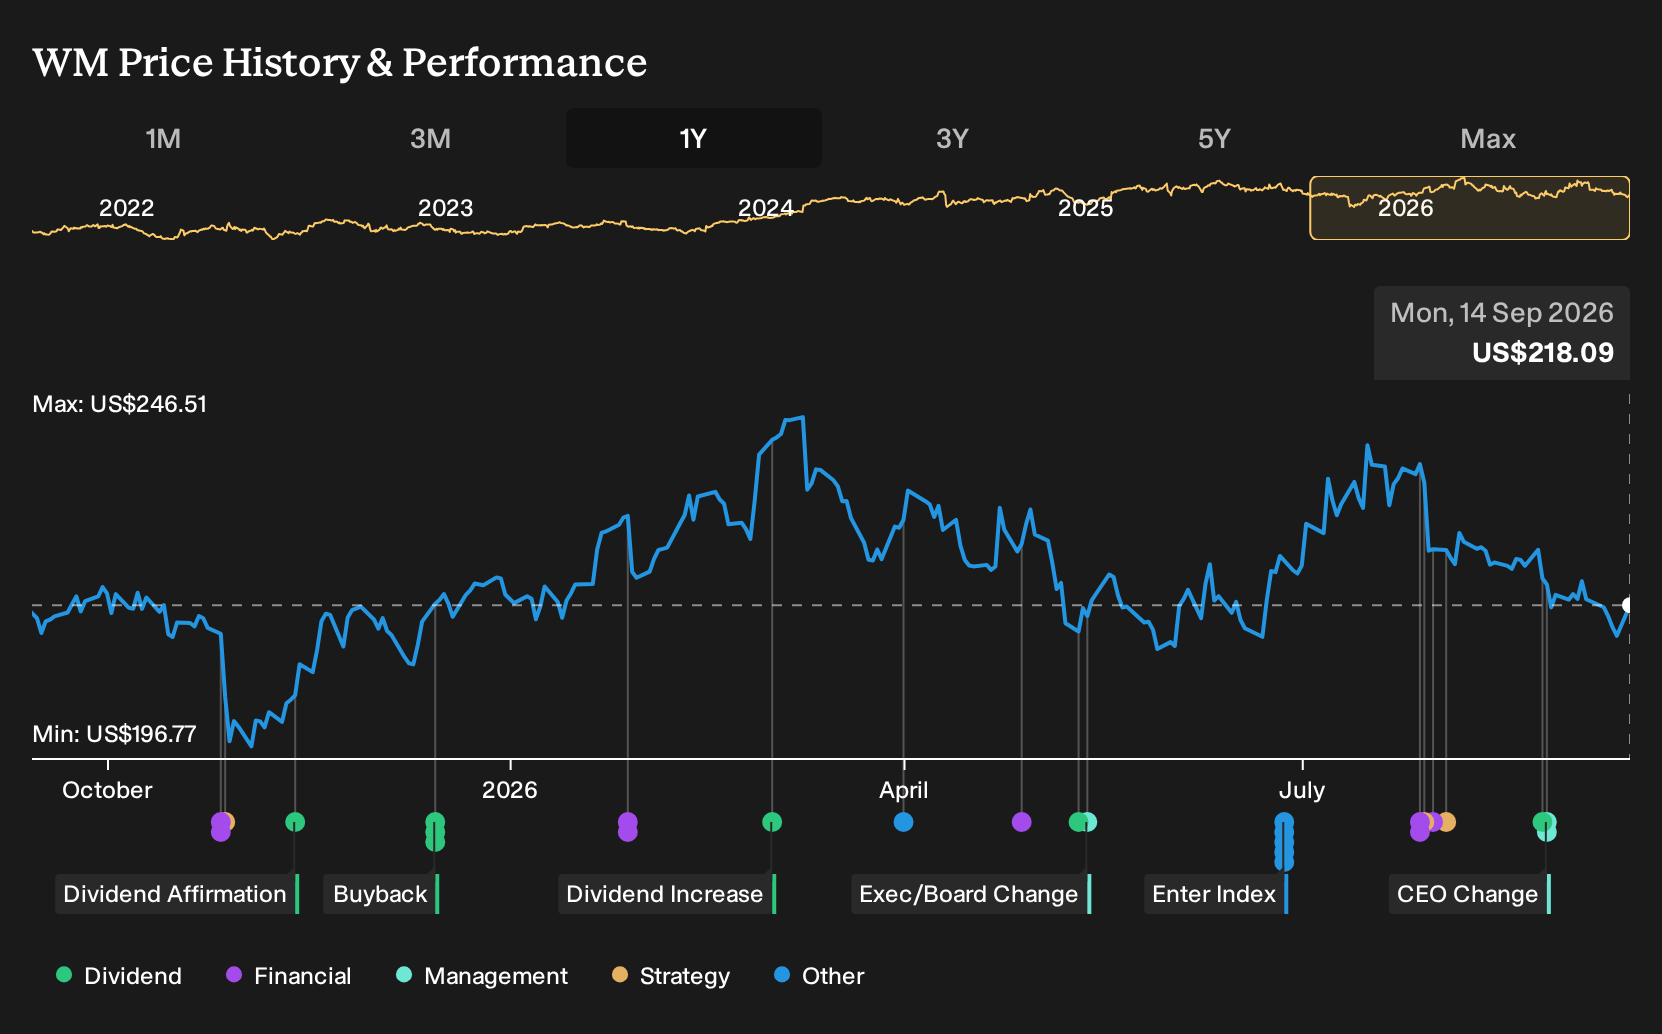
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster tightly between about $242.70 and $260.64 per share, which shows how even private investors can crowd around a relatively narrow band. Set those views against risks such as tax credit changes, leverage from the Stericycle deal, and weather disruption, and then weigh how Waste Management’s technology and sustainability projects might influence your own stance.
Explore 2 other Waste Management fair value estimates, including one that suggests potential upside of as much as 20% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so go with your instincts.
- A great starting point for your Waste Management research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Waste Management. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Waste Management's overall financial health at a glance.
Looking For More Investment Ideas Beyond Waste Management?
If the Waste Management story has sharpened your thinking on earnings quality and resilience, you can use that same lens to scan a wider field of opportunities using the Simply Wall St Screener. Structure your watchlist around the traits you care about most, whether that is undervaluation, balance sheet strength or a focus on durable cash flows.
- For investors who want potential value with quality fundamentals, you can start with this curated set of 35 high quality undervalued stocks that combine financial strength with pricing that may not fully reflect it.
- If balance sheet resilience is your priority, you can narrow your search using a list of solid balance sheet and fundamentals (23 results) that focuses on companies with stronger financial footing.
- When you want to cast a wider net for under-the-radar stories, you can turn to a 15 high quality undiscovered gems that highlights businesses with solid fundamentals but less attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com