


Positive analyst sentiment has put Allient (ALNT) on many investors’ screens, with a higher Zacks Rank and stronger earnings estimates helping to explain recent trading interest in the motion-control specialist.
Recent trading has cooled, with the share price down 8.22% over one day and 18.72% over 30 days. Even so, Allient still carries a 62.92% year to date share price return and a 94.51% total shareholder return over one year, which suggests that earlier optimism may now be getting repriced as analysts reassess growth potential and risk.
Scan beyond Allient and compare its recent swing in sentiment with hand picked industrial and motion control peers in the list of solid balance sheet and fundamentals (23 results)
Allient now sits between a sharp pullback and a still-strong one year run, which leaves one blunt issue for investors sizing it up today: Does the current price still offer enough upside potential to justify the recent swing in risk?
Most Popular Narrative: 23% Undervalued
The most widely followed narrative values Allient at $118 per share, which sits above the last close at $90.55 and frames today’s weakness as a potential valuation gap rather than a full change in story.
The analysts have a consensus price target of $118.0 for Allient based on their expectations of its future earnings growth, profit margins and other risk factors. In order for you to agree with the analysts, you would need to believe that by 2029, revenues will be $727.9 million, earnings will be $56.3 million, and it would be trading on a PE ratio of 47.5x, assuming you use a discount rate of 9.7%.
See why 8 investors see Allient as 23% undervalued.
Result: Fair Value of $118 (UNDERVALUED)
Still, the Allient story could shift quickly if its push into aerospace, defense and medical markets delivers firmer margins and makes recent automation worries appear overstated.
Find out about the key risks to this Allient narrative.
Another View On Allient’s Valuation
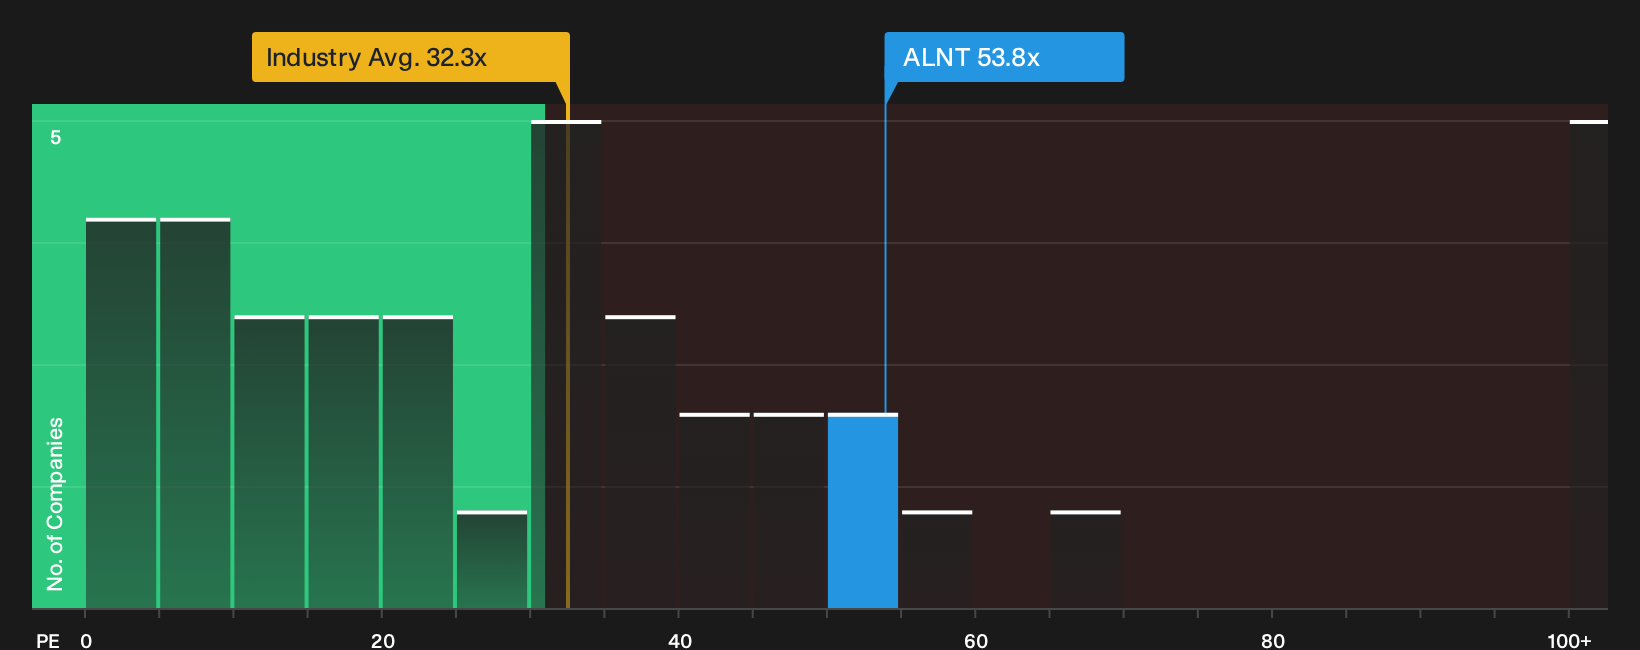
On the flip side, Allient screens as expensive on its current P/E of 53.8x. This is well above the US Electrical industry at 34.1x, the peer average at 24.3x, and a fair ratio of 25.4x that the market could move toward over time. If sentiment cools, how much P/E compression are you comfortable underwriting?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on Allient after all of that. If the push and pull between optimism and concern feels familiar, act while the data is fresh and weigh both sides using the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Allient?
Do not stop with Allient. Broaden your watchlist with a few focused hunting grounds that can surface very different types of opportunities.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (23 results).
- Hunt for quality at a discount by reviewing the 35 high quality undervalued stocks.
- Spot companies the crowd may be missing by checking the 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com