


Why Max Stock’s New Logistics Center Matters
Max Stock (TASE:MAXO) has signed a long term lease for a planned 45,000 sqm logistics center in Ofakim, a move tied directly to expanding its distribution backbone.
The facility is expected to be handed over around December 2028, with an initial 10 year lease that can roll for two extra 5 year periods if conditions in the agreement are met.
Management estimates about ₪20 million in fit out spending for the site. The center is intended to complement two existing logistics centers and reduce reliance on external suppliers.
Against that backdrop, Max Stock’s 1 month share price return of 7.17% and year to date share price gain of 42.46% suggest momentum has been building. The 1 year total shareholder return of 91.20% and 3 year total shareholder return of roughly 4.7x highlight how strongly long term holders have been rewarded despite a softer 90 day share price move.
Scan retailers that could benefit from similar supply chain upgrades and operational scaling to Max Stock by reviewing our curated list of list of solid balance sheet and fundamentals (194 results)
Bulls point to Max Stock’s expansion and past returns as evidence the current valuation still has room, while bears see exuberance. Which side do the numbers lean toward as the logistics spend comes into focus?
Preferred P/E of 34x for Max Stock: Is It Justified?
On simple valuation math, Max Stock trades on a P/E of 34x, which prices the ₪36.47 share price well above many multiline retail peers.
The P/E ratio compares the current share price with earnings per share. For a retailer like Max Stock, it reflects how much investors are willing to pay today for each unit of profit, and it often embeds expectations about future earnings resilience and store level economics.
Here the market is assigning a far richer multiple than both the Asian Multiline Retail industry average of 19.8x and the peer average of 20.5x. That gap is wide, so the current pricing looks expensive relative to similar businesses, even with high quality earnings, 35.9% earnings growth over the past year and a 57.3% Return on Equity.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 34x (OVERVALUED)
Still, the Max Stock story can sour quickly if the rich 34x P/E compresses, or if the sizeable logistics investment weighs on returns longer than investors expect.
Find out about the key risks to this Max Stock narrative.
Another View On Max Stock’s Valuation
The P/E screen paints Max Stock as expensive, and our DCF model reaches a similar conclusion. At ₪36.47, the share price sits above the SWS DCF estimate of future cash flow value at ₪25.47, which suggests the market already builds in a lot of optimism. What happens if expectations cool?
Look into how the SWS DCF model arrives at its fair value.
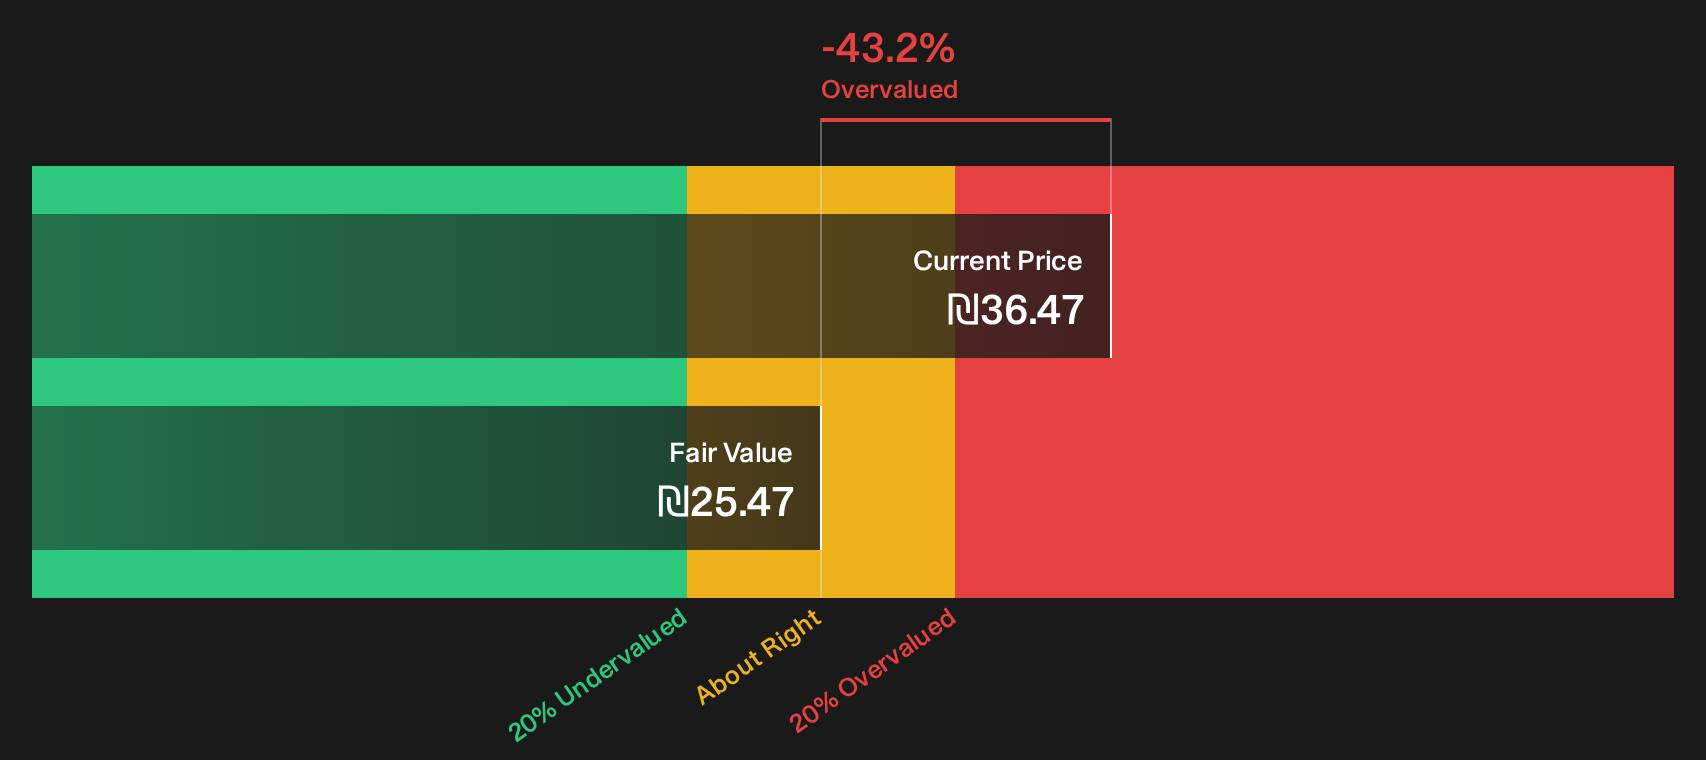
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Max Stock for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 190 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this Max Stock story appears finely balanced between optimism and caution, consider reviewing the details while they are fresh and pressure test the data yourself with the 1 key reward and 1 important warning sign
Looking for more Max Stock style ideas?
If Max Stock has sharpened your focus on valuation and quality, do not stop here. Broader opportunity sits with peers that match your risk and return preferences.
- Target potential upside in companies that combine quality fundamentals with compressed pricing through our curated list of 190 high quality undervalued stocks.
- Lock in income focused opportunities by reviewing yield heavy candidates in the 163 dividend fortresses.
- Reduce portfolio shocks by concentrating on resilient businesses screened for financial strength with the 103 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com