


Tariff refund sets up one off gain for Seiko Epson stock
Seiko Epson (TSE:6724) has flagged a one time financial boost after U.S. Customs and Border Protection approved refunds of previously paid tariffs following a U.S. Supreme Court ruling.
The business expects to record a refund of US$109 million, about ¥17,000 million, plus interest in the second quarter of the fiscal year ending March 2027. This gives investors a fresh data point to assess the stock.
The tariff refund lands at a time when Seiko Epson’s share price has climbed strongly over 2026, with a year-to-date share price return of 55.9% and a 1-year total shareholder return of 62.4%, pointing to firm positive momentum rather than a short burst of enthusiasm.
Scan how Seiko Epson’s refund-driven momentum compares with other hand-picked tech companies by reviewing our 18 high quality undervalued stocks with stronger cash flows and sturdier balance sheets.
After a 56% year to date climb and a one off US$109 million refund on the way, the real puzzle is where Seiko Epson’s fair value falls between the analyst target and intrinsic value estimates.
Price to earnings of 40.4x for Seiko Epson: Is it justified?
On simple multiples, Seiko Epson looks expensive. The shares last closed at ¥3,100 while trading on a P/E of 40.4x, against a JP Tech industry average of 11.5x and a peer average of 10.8x, which points to a rich earnings valuation relative to similar businesses.
The P/E ratio compares what investors are willing to pay today for each unit of current earnings. For a hardware focused technology group like Seiko Epson, that figure often reflects how convincingly the market expects profits to compound from here, especially when earnings are affected by one off items and cyclical swings.
Forecast data suggests profits are expected to rise 21% per year over the next three years, faster than the 8.8% forecast for the broader JP market, while revenue is only projected to improve 2.6% each year, slower than the 6.3% market growth rate. That mix hints at margin rebuild as a key assumption behind the high P/E, particularly given current net profit margins of 1.7% compared with 3.2% last year and the presence of large one off items in recent results.
Set against peers, the contrast is sharp. A P/E of 40.4x is materially higher than both the 11.5x JP Tech average and the 10.8x peer group. It also sits well above the estimated fair P/E of 21.9x that the fair ratio model suggests the market could gravitate toward over time if sentiment cools or earnings do not rise as quickly as implied.
Explore the SWS fair ratio for Seiko Epson.
Result: Price-to-earnings of 40.4x (OVERVALUED)
Still, Seiko Epson’s premium P/E and reliance on a one off tariff refund leave the story exposed if earnings quality or cash generation disappoint relative to expectations.
Find out about the key risks to this Seiko Epson narrative.
Another view on Seiko Epson’s value
While the P/E of 40.4x paints Seiko Epson as expensive against the JP Tech sector, the SWS DCF model tells a different story. On that framework, an estimated fair value of ¥4,828 per share versus a ¥3,100 price suggests the stock screens as undervalued. Which signal do you trust more for the long haul?
Look into how the SWS DCF model arrives at its fair value.
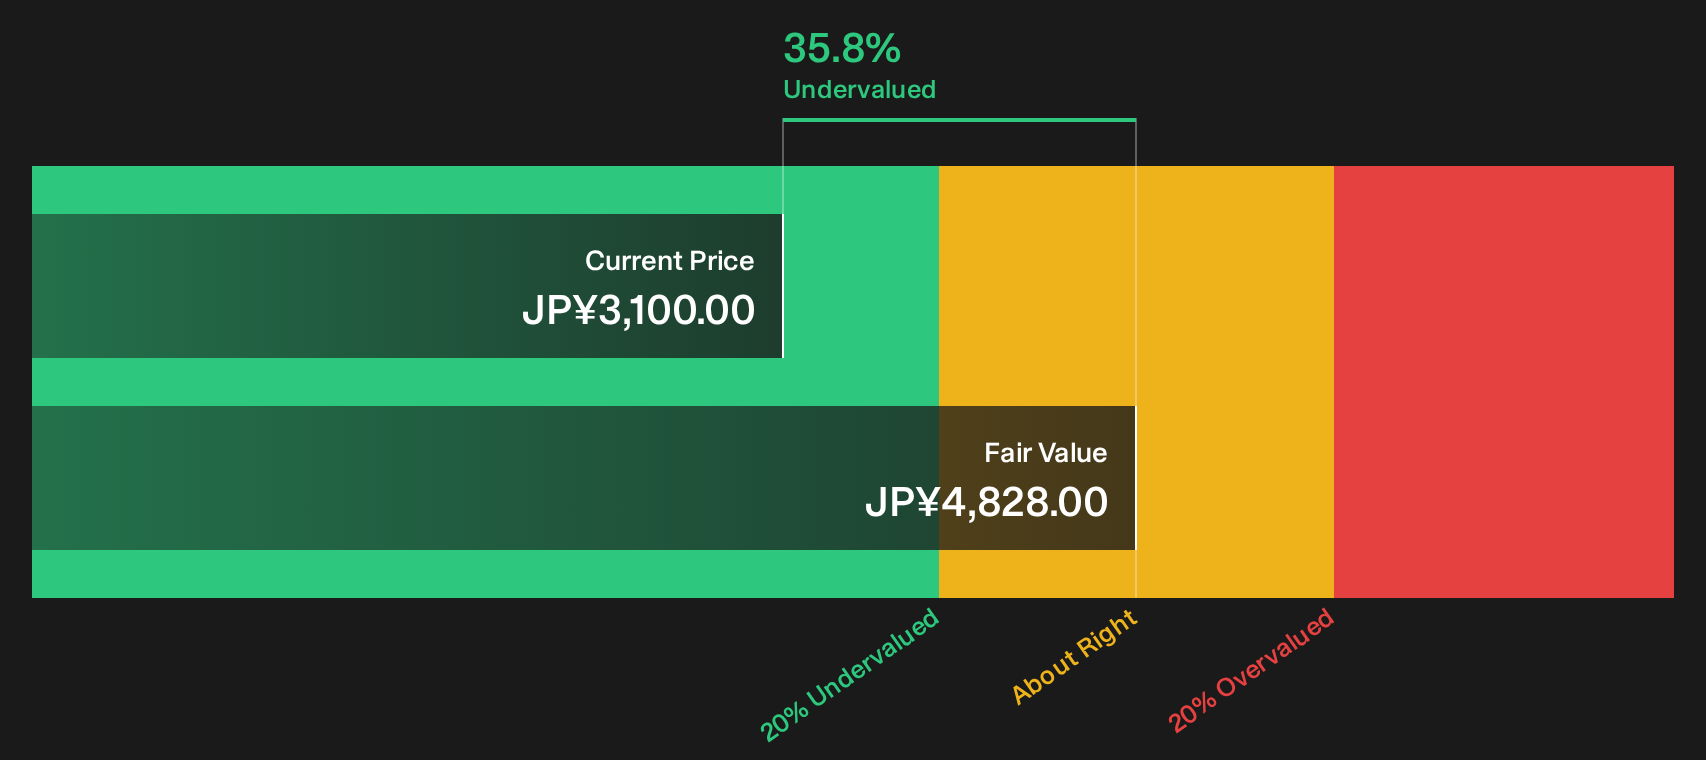
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Seiko Epson for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Seiko Epson’s premium valuation and tariff windfall can feel hard to read, so move quickly, review the underlying numbers, and decide where you land by weighing its 2 key rewards and 3 important warning signs
Looking for more Seiko Epson investment ideas?
If Seiko Epson’s setup has sharpened your curiosity, do not stop here. Use the screener to surface other opportunities before the crowd notices them.
- Target stability first by scanning a 12 resilient stocks with low risk scores that already filters for resilience so you are not guessing on risk alone.
- Hunt for value by checking a 74 high quality undiscovered gems that highlights quality fundamentals before they attract wider attention.
- Prioritise financial strength by reviewing a list of solid balance sheet and fundamentals (19 results) that spotlights companies with sturdy foundations backing their future plans.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com