


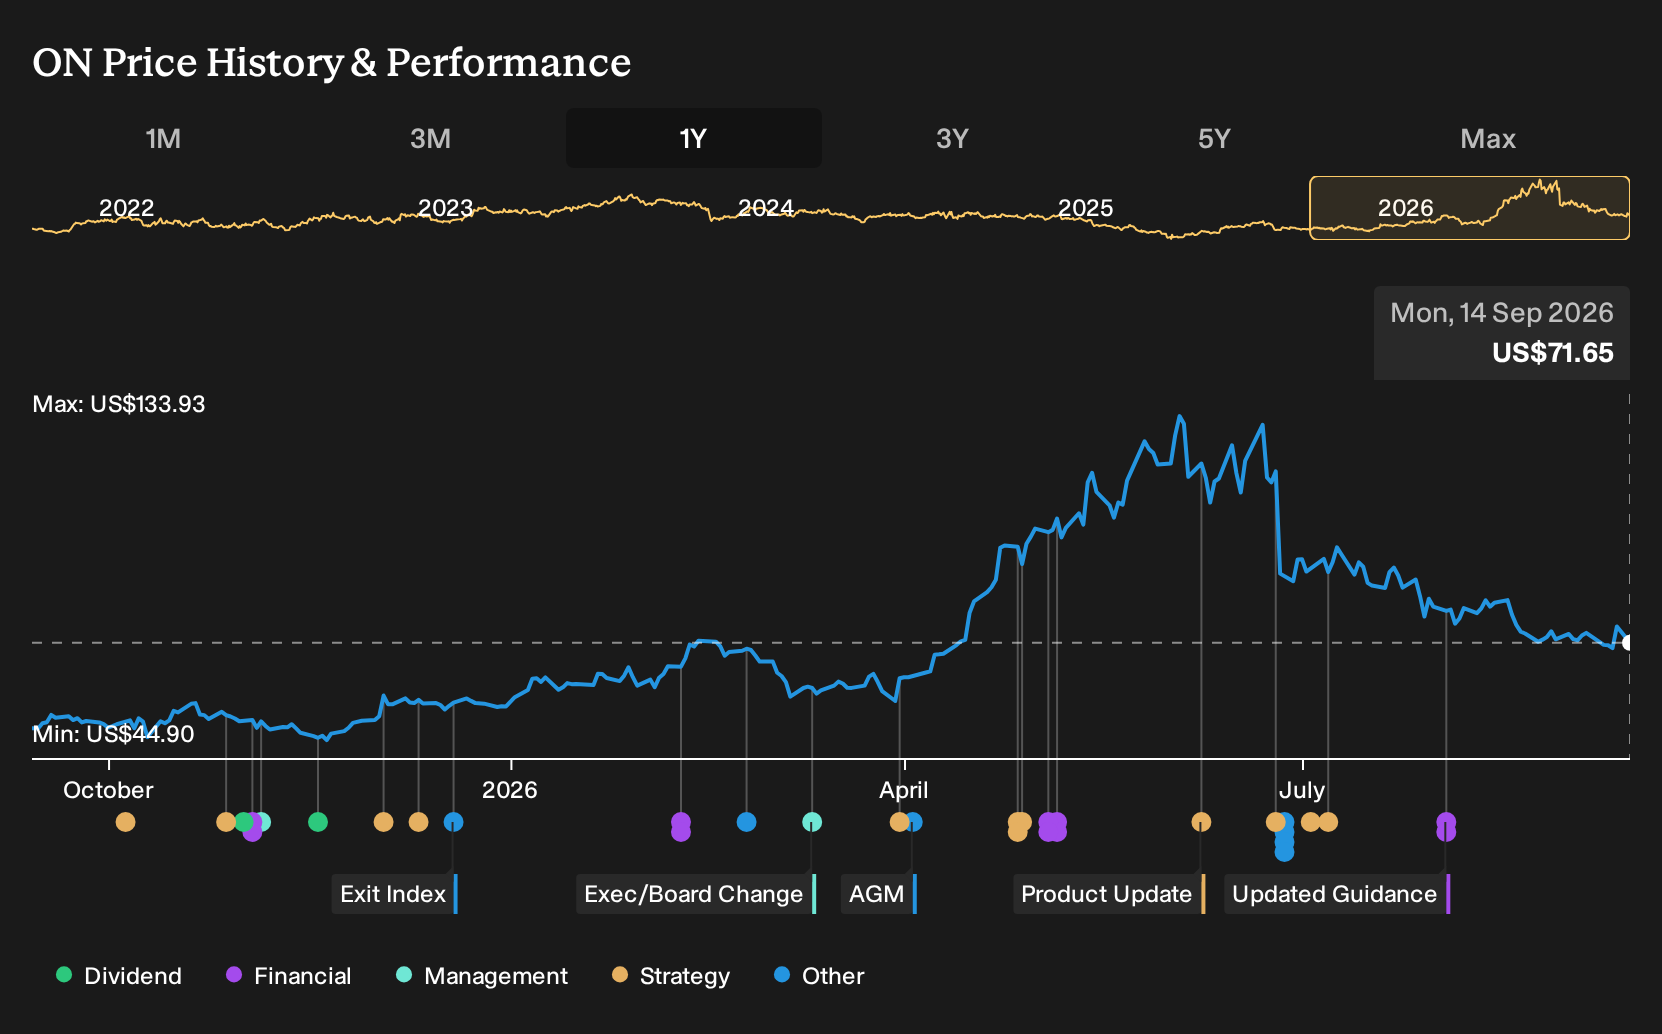
- ON Semiconductor recently saw its shares decline 5.9% in a single session as traders reacted to the upcoming earnings report and current valuation metrics.
- The company is being closely watched because expectations for higher earnings and revenue intersect with a forward P/E that sits below its industry, which sharpens attention on how efficiently ON Semi is turning its growth projects into profits.
- We will now assess how ON Semiconductor's investment narrative is affected by this earnings focused scrutiny of its discounted forward P/E.
Scan how other discounted earnings stories compare to ON Semiconductor by reviewing the hand picked 35 high quality undervalued stocks, moving on different expectations around their next results.
ON Semiconductor Investment Narrative Recap
For an investor in ON Semiconductor, the key belief is that its focus on power and sensing chips for autos, industrial gear and AI data centers can help offset cyclical swings and portfolio pruning. The recent 5.9% share pullback ahead of earnings mainly heightens attention on execution rather than changing that thesis on its own.
The main near term catalyst is whether upcoming results show progress on higher value silicon carbide, intelligent sensing and efficiency efforts, while utilization and margins remain under pressure. The biggest risk is that weaker auto demand or slower EV adoption, especially outside China, keeps factories underused and delays any margin recovery.
With no fresh company announcements tied directly to this latest move in ON Semiconductor, the most relevant context is management's existing plan to exit lower margin legacy products worth about US$200m to US$300m of revenue between 2025 and 2026. That reset keeps the focus on higher value automotive, industrial and AI data center lines.
For you as a shareholder, the question is whether the newer silicon carbide and sensing franchises can take up that slack while competition in EV power and imaging remains intense. Execution on manufacturing efficiency and product mix remains central to the story, so each earnings print becomes a practical check-in on that transition.
ON Semiconductor's outlook projects US$9.0b in revenue and US$2.5b in earnings by 2029. This is based on an assumed 13.0% annual revenue growth rate and an earnings increase of about US$1.87b from current earnings of US$630.2m.
Uncover why ON Semiconductor's fair value indicates a 50% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the lowest ON Semiconductor analysts focus far more on geopolitical and supply chain cost risk, which looks especially relevant after a 5.9% share drop on valuation worries. These bearish voices were penciling in about US$8.0b of revenue and US$2.2b of earnings by 2029. This paints a tougher story you may want to compare with other viewpoints.
Explore 4 other ON Semiconductor fair value estimates, including one that suggests it could be worth just $76.97.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your ON Semiconductor research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ON Semiconductor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ON Semiconductor's overall financial health at a glance.
Looking For More Ideas Beyond ON Semiconductor?
If the ON Semiconductor story has sharpened your thinking about valuation, earnings power and risk, it can help to set it against a wider field of candidates using the Simply Wall St Screener.
- If resilience matters most to you, you could start with companies that pair sturdy finances with measured risk profiles by checking out 11 resilient stocks with low risk scores.
- If you want income potential on top of price moves, you could filter for businesses with stronger yields and balance their payouts against cash generation using the 6 dividend fortresses.
- If you are hunting for underfollowed opportunities with solid fundamentals, you might scan a 15 high quality undiscovered gems that may not yet be on every investor's radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com