


U.S. stock futures declined Tuesday as the Dow Jones, S&P 500 and Nasdaq 100 indices fell following Monday’s lower close.
The Federal Open Market Committee’s two-day meeting will commence, with all eyes on the FOMC’s policy direction. Meanwhile, the 10-year Treasury bond yielded 5.03% at the last check, topping 5% on Monday for the first time since 2023.
Veteran Ed Yardeni called it confidence in the economy, and Peter Schiff warned it’s just the start of a bigger climb, as the Federal Reserve’s interest rate decision looms on Wednesday.
The CME Group’s FedWatch tool projections show markets pricing in a 94.5% likelihood of the Federal Reserve hiking interest rates tomorrow.
Meanwhile, energy prices continue to surge amid the ongoing U.S.-Iran conflict, with Brent crude reaching $107.85 a barrel, up 2.05%. Sen. Elizabeth Warren (D-Mass.) blamed the war for national average gas prices hitting $4.31 a gallon. California Governor Gavin Newsom (D) criticized the administration for failing to shield Americans from predictable disruptions in the Strait of Hormuz. Meanwhile, Iran’s Security Chief Mohsen Rezaee stated there will be no negotiations until Tehran’s conditions are met.
| Index | Performance (+/-) |
| Dow Jones | 0.67% |
| S&P 500 | 0.59% |
| Nasdaq 100 | 0.62% |
| Russell 2000 | 0.66% |
The SPDR S&P 500 ETF Trust (NYSE:SPY) and Invesco QQQ Trust ETF (NASDAQ:QQQ), which track the S&P 500 index and Nasdaq 100 index, respectively, were lower in premarket on Tuesday. The SPY was down 0.53% at $756.87, while the QQQ declined 0.56% to $705.23.
Stocks In Focus
Genpact
- Genpact Ltd. (NYSE:G) rose 1.21% in premarket on Tuesday as the company named Sumita Pandit as Chief Financial Officer just as it rolled out its agentic AI Record-to-Report Suite.
- Benzinga’s Edge Stock Rankings indicate that G maintains a weak price trend in the long term but a strong trend in the short and medium terms, with a good growth score.

Strategy
- Strategy Inc. (NASDAQ:MSTR) dropped 4.20% in premarket on Tuesday, after Monday’s advances following Senate Republicans releasing a revised draft of the Clarity Act ahead of Tuesday’s procedural vote. The draft addresses Democrats’ ethics and banking industry concerns, which may increase the likelihood that the bill will pass.`
- Benzinga’s Edge Stock Rankings indicate that MSTR maintains a weak price trend in the long term but a strong trend in the short and medium terms.
CrowdStrike Holdings
- CrowdStrike Holdings Inc. (NASDAQ:CRWD) was down 1.45% after Monday’s 13.85% rally as the company announced it registered the resale of 2.12 million shares.
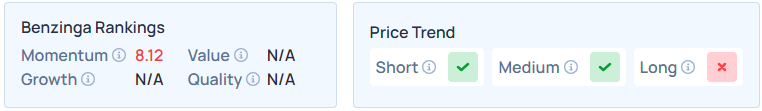
- Benzinga’s Edge Stock Rankings indicate that CRWD maintains a strong price trend in the long, short, and medium terms, with a poor value score.

Blue Moon Metals
- Blue Moon Metals Inc. (NASDAQ:BMM) was down 1.23% in Tuesday’s premarket after gaining 4.12% on Monday after the company, along with Elmet Group Co. (NASDAQ:ELMT), and EQ Resources (OTC:EQRLF), announced a binding letter agreement to invest $150 million – $175 million in Springer Tungsten Complex in Imlay, Nevada.
- Benzinga’s Edge Stock Rankings indicate that BMM maintains a weak price trend in the long, short, and medium terms.

Tyra Biosciences
- Tyra Biosciences Inc. (NASDAQ:TYRA) was 0.20% higher as it announced pricing of $400 million underwritten offering of common stock and pre-funded warrants.
- Benzinga’s Edge Stock Rankings indicate that TYRA maintains a weak price trend in the long, medium, and short terms.

Cues From Last Session
Communication Services led Monday’s gains, accompanied by Health Care and Consumer Staples. Conversely, Information Technology suffered the steepest decline, with Industrials and Utilities also experiencing notable drops.
| Index | Performance (+/-) | Value |
| Dow Jones | 0.29% | 52,421.20 |
| S&P 500 | 0.48% | 7,619.98 |
| Nasdaq Composite | 0.56% | 26,186.41 |
| Russell 2000 | 0.40% | 2,892.24 |
Insights From Analysts
LPL Financial maintains a positive outlook on both the U.S. economy and the stock market despite potential Federal Reserve interest rate increases. LPL emphasizes that the U.S. economy shows surprising resilience, driven by solid growth, strong household balance sheets, low debt-service burdens, and ongoing investments in artificial intelligence.
Consequently, they expect the economy to remain “capable of growing near 2% even as markets price in the possibility of additional rate increases.”
Regarding equities, LPL’s Strategic and Tactical Asset Allocation Committee maintains a tactical overweight position. Historically, rate hikes do not derail bull markets unless paired with high recession risk. LPL notes that “today’s combination of economic resilience and moderating inflation suggests the backdrop for equities remains supportive.”
Furthermore, they believe that “an improving macro backdrop and sustained AI-driven earnings growth will continue to support the broader equity market through the remainder of 2026.”
While higher interest rates may introduce short-term market volatility, LPL views them as “more likely a headwind than a bull market-ending event,” keeping their broader market outlook constructive.
Upcoming Economic Data
Here’s what investors will be keeping an eye on Tuesday:
- Data from the Empire State Manufacturing Survey for September is scheduled to be released by 8:30 a.m. ET.
Commodities, Crypto, And Global Equity Markets
Crude Oil WTI futures were trading higher in the early New York session by 2.11% to hover around $103.53 per barrel.
Gold Spot US Dollar fell 0.84% to hover around $4,262.90 per ounce. The U.S. Dollar Index spot was 0.25% higher at the 99.6430 level.
Meanwhile, Bitcoin (CRYPTO: BTC) was trading 1.00% lower at $76,920.70 per coin over the last 24 hours.
Asian markets were lower on Tuesday as Japan’s Nikkei 225, India’s Nifty 50, South Korea’s Kospi, China’s CSI 300, Hong Kong’s Hang Seng, and Australia’s ASX 200 indices fell. European markets were also lower in early trading.
Image via Shutterstock