


- Fujitsu has renewed its AI-focused partnership with Palantir Technologies and announced plans to start global sales of its Japan-designed FUJITSU-MONAKA CPU and MONAKA Server from November 2026, targeting sovereign AI infrastructure needs in Japan and Europe.
- The combination of Palantir’s data platforms with Fujitsu’s MONAKA hardware and Takane large language model points to a tighter link between high-value services and in-house infrastructure, which could influence where future profit pools concentrate inside the business.
- We will examine how Fujitsu's investment narrative is affected by the MONAKA sovereign AI server initiative together with the renewed Palantir alliance.
Compare how Fujitsu's AI and quantum bets stack up against other hardware and infrastructure plays by reviewing our curated list of 60 AI infrastructure stocks in this space.
Fujitsu Investment Narrative Recap
To own Fujitsu, you need to believe the pivot toward digital services, AI, and higher margin work can offset pressure in legacy hardware and any softness in overseas operations. The renewed Palantir alliance and MONAKA plans speak directly to that story. For the next year or so, the key swing factor still looks like execution on large digital transformation projects rather than any single AI headline.
The biggest risk remains concentration in Japan and dependence on chunky, multi year public and enterprise contracts, which can leave earnings uneven and exposed if budgets tighten. Recent announcements are encouraging for the AI narrative but do not remove concerns about slower international momentum or the drag from traditional infrastructure lines.
The Palantir partnership renewal is the clearest near term operational catalyst tied to this update. Fujitsu is committing more Forward Deployed Engineering resources, embedding its own Takane LLM and industry expertise into Palantir Foundry and AIP, and positioning itself as a Global FDE Partner. That deepens its role in complex AI projects where customers want governed data, strong access controls, and production grade environments.
This alliance also speaks directly to the risk that Fujitsu underuses AI in delivery. Building in house Palantir capability can support higher productivity on large programs and potentially make its modernization and Uvance offerings more competitive, especially in Europe and Japan. The flip side is execution risk: if these AI platforms are slow to scale across clients or regions, the cost of building that capability could weigh on returns.
Fujitsu Earnings Expectations Behind the AI Story
Fujitsu's narrative ties its AI push, including MONAKA and the Palantir alliance, to a concrete earnings and revenue profile that analysts have already mapped out. Consensus forecasts point to revenue increasing by 3.4% per year over the next three years, with profit margins projected to move from 9.0% today to 10.8% on a three-year view. That margin shift underpins the expectation that earnings could rise from ¥317.8 billion today to ¥421.4 billion by about 2029, even though analyst estimates range widely between ¥338.7 billion and ¥477.8 billion.
The earnings bridge is sizeable. Moving from ¥317.8 billion to ¥421.4 billion implies an increase of roughly ¥103.6 billion, which is what needs to show up in future profit and loss statements for the current consensus story to hold together. Analysts also factor in a 2.12% yearly reduction in share count over the next three years, which would help earnings per share, provided the buybacks are executed at prices that do not overpay for that future earnings stream.
On the revenue side, the analyst model pins 2029 sales at ¥3,905.6 billion. That number gives context for the AI server and sovereign infrastructure push, because it implies that MONAKA and related offerings either have to support that trajectory or leave other segments to do more heavy lifting. The forecast assumes investors will be comfortable with Fujitsu trading on a P/E of 22.5x those 2029 earnings, compared with 20.4x today and 16.3x for the broader Japanese IT peer group.
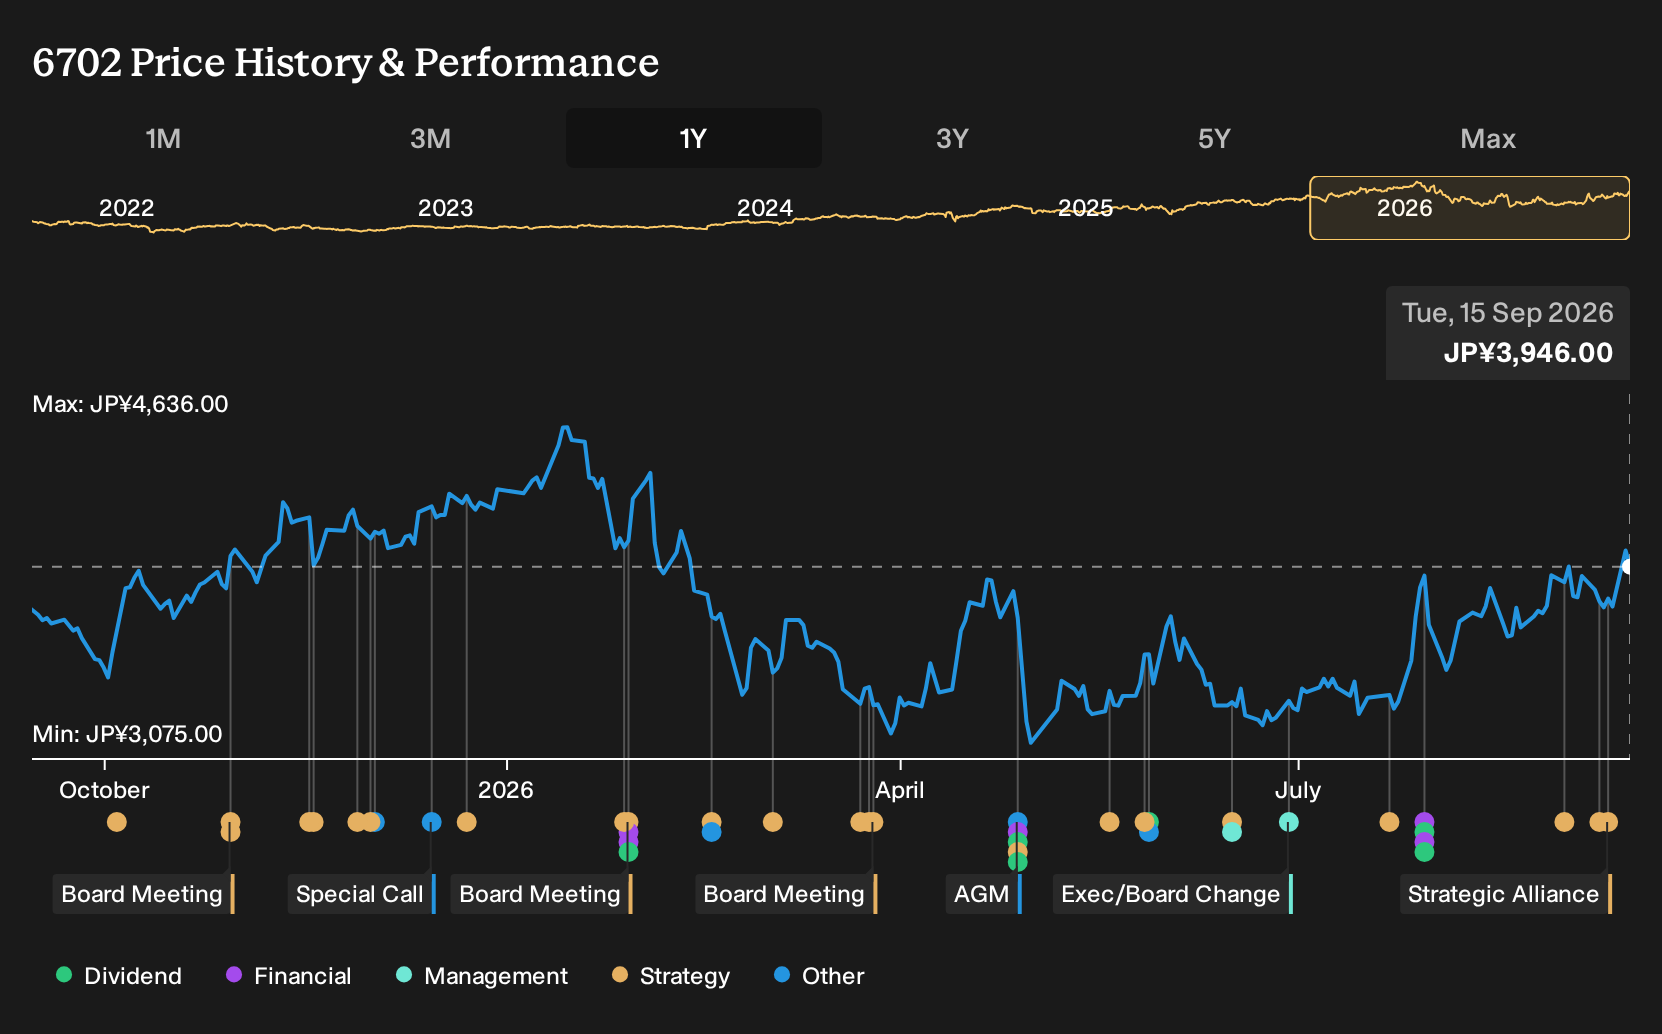
If that higher multiple does not materialize, or if the margin expansion from 9.0% to 10.8% stalls, the arithmetic behind the current analyst price targets starts to look stretched. The current consensus price target sits at ¥4,724.62, with a bullish end of ¥6,000.0 and a bearish mark at ¥3,830.0, versus a share price of ¥3,745.0. That range reflects real disagreement about how much Fujitsu can convert AI and digital transformation work into sustained profitability rather than one-off contract wins.
Fujitsu's narrative projects ¥3,905.6 billion in revenue and ¥421.4 billion in earnings by 2029. This requires 3.4% yearly revenue growth and an earnings increase of about ¥103.6 billion from ¥317.8 billion today.
Uncover why Fujitsu's fair value indicates a 20% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle focuses on talent risk rather than hardware or AI upside. Some of the most optimistic Fujitsu analysts still flagged global skill shortages as a potential brake, even as they penciled in revenue of ¥4,138.0 billion and earnings of ¥454.7 billion by 2029. Those estimates were set before this partnership news, so opinions may shift.
Explore 2 other Fujitsu fair value estimates, including one that suggests as much as 51% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Fujitsu research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Fujitsu. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fujitsu's overall financial health at a glance.
Looking For More Investment Ideas Beyond Fujitsu?
If the Fujitsu story has sharpened your thinking about AI, infrastructure, and earnings quality, it can be useful to line it up against other opportunities using a consistent framework. The Simply Wall St Screener lets you filter for very specific traits so you can compare this stock with others that fit the kind of portfolio you want to build.
- For investors who want potential value with quality fundamentals, review our curated 18 high quality undervalued stocks to see companies that combine strong cash flows with balance sheets analysts may be overlooking.
- If capital preservation and steadier risk profiles matter most to you, focus on companies in the 12 resilient stocks with low risk scores and see which businesses score well on resilience.
- When you care about financial strength first and share price second, filter for firms in the list of solid balance sheet and fundamentals (19 results) and compare how their fundamentals stack up.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com