


Fresh Monthly Sales Data Puts Ohsho Food Service in Focus
Ohsho Food Service (TSE:9936) has drawn attention after releasing August 2026 sales data, with all company operated stores generating ¥9,517 million and existing outlets contributing ¥9,376 million for the month.
Recent trading has been mixed. The share price has risen about 9.1% over the past 90 days and 2.6% over the past month, yet it remains down roughly 8.1% year to date. The 1 year total shareholder return decline of 21.8% contrasts with 3 year and 5 year total shareholder returns of 33.8% and 59.8% respectively. This points to longer term momentum that has cooled in the short run as investors digest updates like the August sales figures around the current ¥2,956 level.
Spot patterns in how August sales news like Ohsho Food Service's feeds into potential turnarounds by scanning our hand picked 18 high quality undervalued stocks, which pairs balance sheet strength with discounted prices.For Ohsho Food Service, the recent bounce after the August sales release could be a nod to quiet operational progress or just a short term mood swing. The valuation work has to sort out which story fits.
Price-to-Earnings of 24.6x for Ohsho Food Service: Is It Justified?
Valuation for Ohsho Food Service currently leans on a P/E of 24.6x at a ¥2,956 share price, which points to investors paying a premium compared with both its own fair P/E estimate and the broader hospitality group.
P/E simply compares what the market is willing to pay today for each unit of earnings. For a restaurant operator like Ohsho Food Service, this ratio often reflects how investors weigh relatively steady demand for eating out against questions over cost pressures, store efficiency and long term profit resilience.
The stock is described as expensive versus an estimated fair P/E of 18.6x. That suggests the market is assigning a much richer tag than the level that regression based fair value work points to, a level the share price could move toward if sentiment cools or earnings do not keep pace with expectations.
Against its closest listed peers, Ohsho Food Service also looks fully priced. The current 24.6x multiple exceeds the JP Hospitality industry average of 22.1x, which signals investors are paying up relative to sector norms as well as to the firm specific fair ratio benchmark.
Explore the SWS fair ratio for Ohsho Food Service.
Result: Price-to-Earnings of 24.6x (OVERVALUED)
Still, the story around Ohsho Food Service can crack if rising costs squeeze its ¥6,324 million net income, or if revenue growth stalls from the recent 2.7% pace.
Find out about the key risks to this Ohsho Food Service narrative.
Another View On Ohsho Food Service’s Value
The SWS DCF model paints a much harsher picture for Ohsho Food Service. With the share price at ¥2,956 and the model’s future cash flow value at ¥774.04, the stock screens as heavily overvalued on this framework. If cash generation does not match the optimism in the current price, where does that leave holders?
Look into how the SWS DCF model arrives at its fair value.
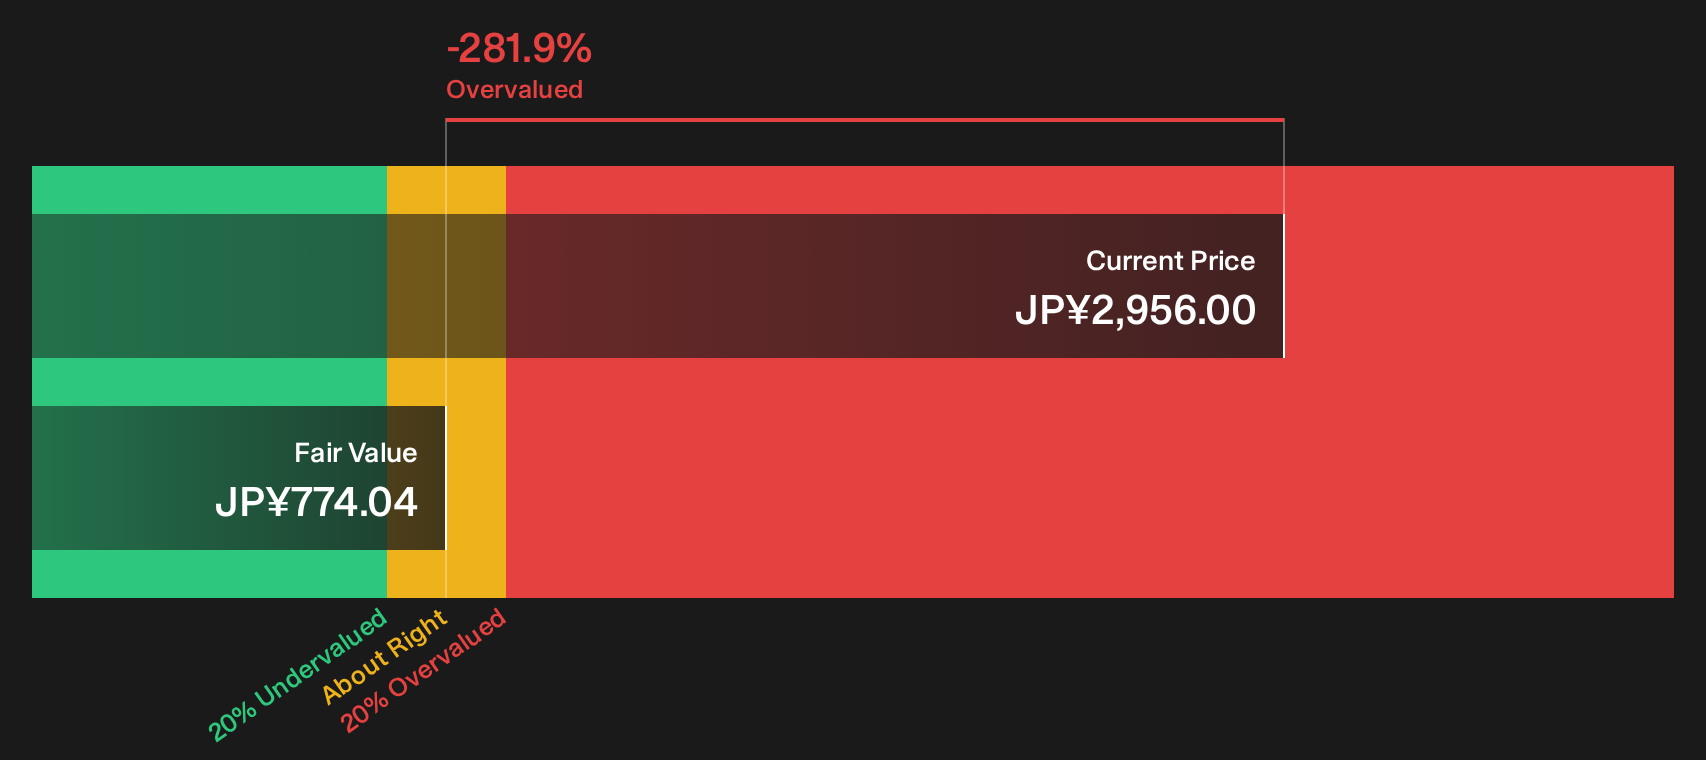
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ohsho Food Service for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Ohsho Food Service so far. If you prefer to pressure test the data rather than the mood, start by examining the real tension between risk and potential upside by weighing the 1 key reward and 1 important warning sign.
Looking For More Ideas Beyond Ohsho Food Service?
Do not stop with Ohsho Food Service. Use the Simply Wall Street screener to surface fresh opportunities that match your risk, return and income goals before others move first.
- Target potential value with pricing that still looks reasonable by scanning the 18 high quality undervalued stocks that couples quality fundamentals with discounted entries.
- Build a steadier income base by reviewing the 17 dividend fortresses focused on higher yielding payouts backed by stronger financial profiles.
- Protect your downside by filtering for resilience through the 12 resilient stocks with low risk scores that highlights businesses with more robust risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com