


- Vertex Pharmaceuticals recently outlined progress in its renal and rare endocrine pipeline, including an FDA decision expected in November for povetacicept in IgA nephropathy, along with advances in kidney disease trials and continued focus on cystic fibrosis therapies.
- The update reflects a stronger emphasis on kidney and cell therapies as management aims to broaden revenue sources beyond cystic fibrosis and make fuller use of its R&D and commercial infrastructure.
- This article will examine how Vertex Pharmaceuticals' investment narrative is shaped by renal portfolio expansion and the upcoming povetacicept FDA decision.
Scan beyond Vertex Pharmaceuticals and compare its renal pivot with other healthcare groups that are sharpening their focus on durable cash generation and balance-sheet strength through our hand-picked list of solid balance sheet and fundamentals (23 results)
Vertex Pharmaceuticals Investment Narrative Recap
For Vertex Pharmaceuticals, you really need to be comfortable with a story that leans on cystic fibrosis cash flows while management pushes hard into renal disease, gene editing and cell therapies. The short term hinge point still sits with the November FDA decision for povetacicept in IgA nephropathy. The CFO transition and tech leadership presentation do not materially change that clinical catalyst.
The biggest risk remains execution and regulatory outcomes in newer areas like kidney disease and genetic medicines, where timelines and approval paths can shift and keep R&D spend high. Recent news around leadership and digital strategy mainly affects how efficiently Vertex Pharmaceuticals may run that engine, rather than the underlying scientific risk.
The most directly relevant update is the appointment of Jonathan Poole as Chief Financial Officer, effective 1 January 2027, while Charles Wagner remains Chief Operating Officer. That keeps continuity in day to day operations and puts a long tenured internal finance leader in charge of capital allocation as renal and cell therapy programs move through the clinic.
For you as a shareholder, this matters because Vertex Pharmaceuticals is balancing heavy R&D investment with the cash coming from CF, CASGEVY and JOURNAVX. A CFO with prior biotech finance and board level audit experience may help keep spending, partnering and potential buybacks aligned with the firm’s key catalysts, including the povetacicept decision and broader kidney portfolio progress.
Vertex Pharmaceuticals' current analyst script assumes revenue growth of 10.9% a year and earnings moving from $4.4b today to a consensus of $6.5b by 2029. That implies about $17.2b in revenue and $6.5b in profit in 2029, with the earnings outlook rising by $2.1b over that period.
Uncover why Vertex Pharmaceuticals' fair value indicates an 8% potential upside to its current price, which could narrow quickly.
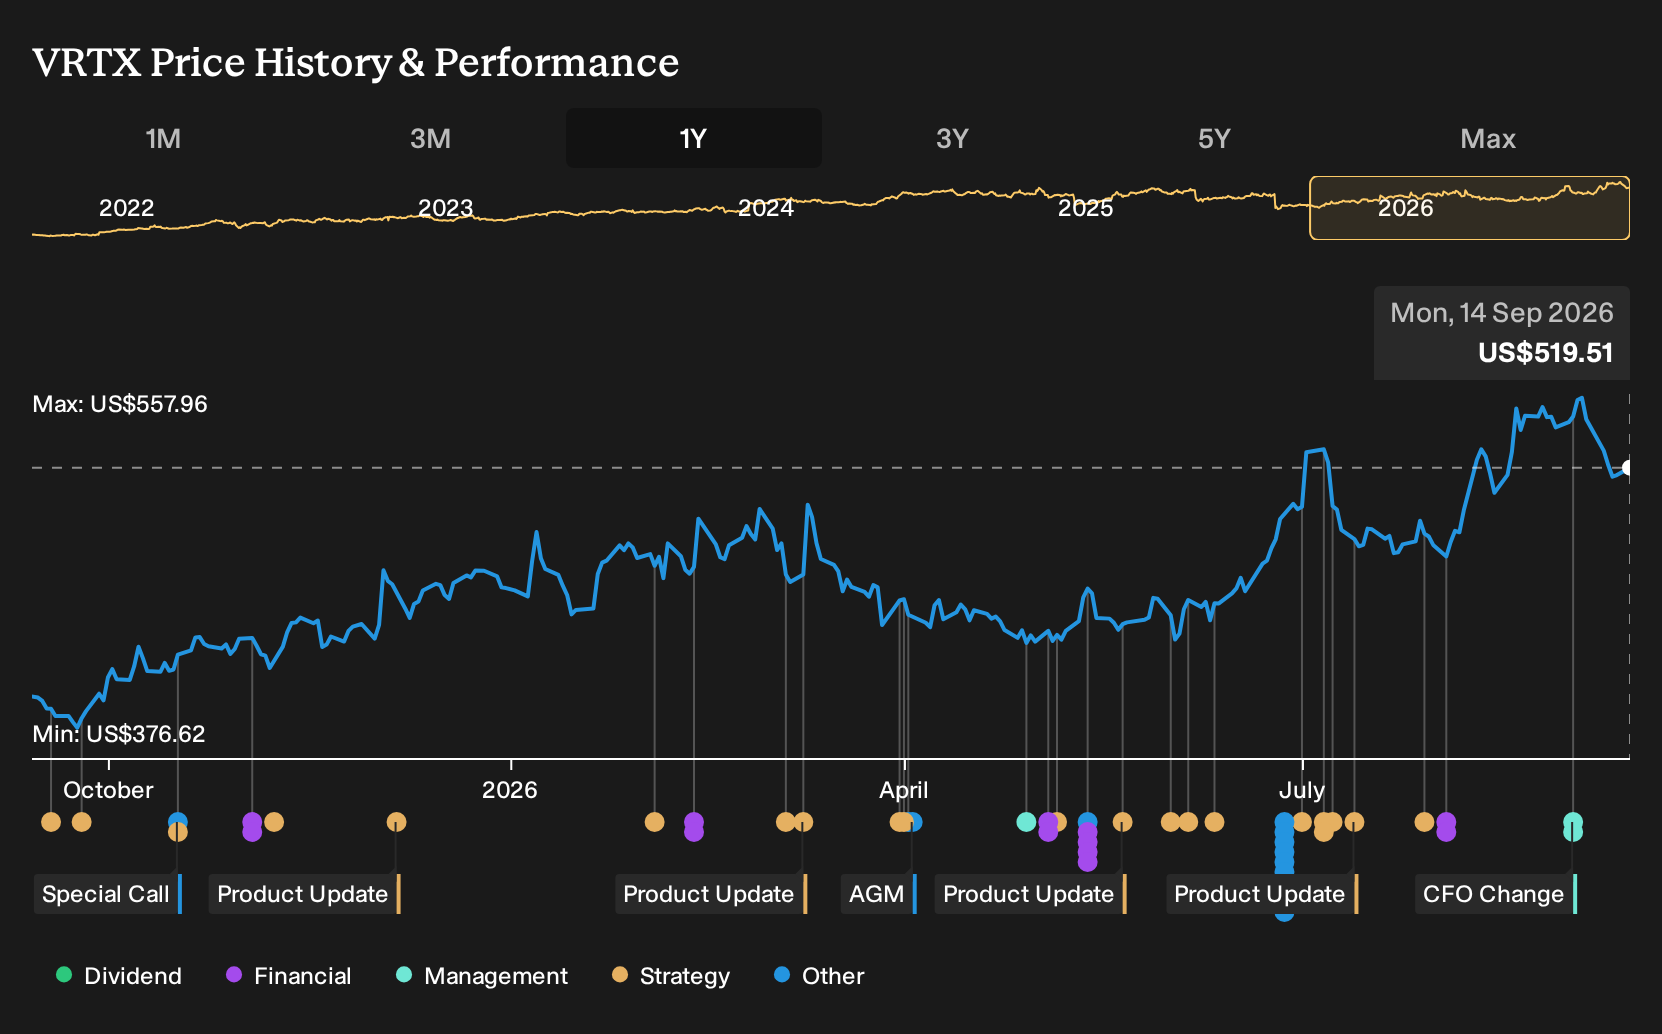
Exploring Other Perspectives
One alternative angle to the Vertex Pharmaceuticals story focuses on pricing pressure rather than the povetacicept decision. The most cautious analysts were working with only 6.8% annual revenue growth and earnings of about US$4.6b by 2029 before this CFO news. That view is far more pessimistic, and these forecasts may shift as new information lands.
Explore 5 other Vertex Pharmaceuticals fair value estimates, including one that suggests as much as 18% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Vertex Pharmaceuticals research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Vertex Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vertex Pharmaceuticals' overall financial health at a glance.
Looking For More Investment Ideas Beyond Vertex Pharmaceuticals?
Once you have a handle on the Vertex Pharmaceuticals story, it can help to put it in context by lining it up against other businesses with very different risk and return profiles. A focused screener lets you filter quickly for the kind of balance sheet strength, income potential or mispricing that fits your own approach, rather than relying on headlines.
- If you want to zero in on companies that look attractively priced relative to their quality, use our curated list of 35 high quality undervalued stocks to see which stocks currently fit that profile.
- For investors who care most about steady income, scan through the 6 dividend fortresses and find businesses that combine higher yields with a focus on durability.
- If capital preservation and resilience come first for you, start with the 11 resilient stocks with low risk scores to highlight businesses that score well on financial strength and volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com