


Moog (MOG.A) is heading into a busy investor week, with back to back appearances at the Jefferies Global Industrials Conference on September 10 and at Morgan Stanley’s Laguna Conference on September 15.
Recent trading has cooled, with the 30 day share price return down 17.86% and the 90 day move lower by 9.69%. Even so, Moog still shows a 45.04% share price return year to date and an 84.59% total shareholder return over one year. This signals longer term momentum, while near term enthusiasm has eased ahead of these conference updates.Scan how Moog compares with other industrials showing similar conference driven interest by reviewing the hand picked list of solid balance sheet and fundamentals (23 results).
The pullback leaves Moog well off recent highs yet still up strongly over the past year. Investors may want to consider whether to step in after this cooling or wait for a clearer valuation reset before viewing it as a potential dip opportunity.
Most Popular Narrative: 19% Undervalued
Moog's most followed valuation story pegs fair value at $446.40 using an 8.15% discount rate, compared with a last close of $362.41. This points to a material gap that conference updates may either reinforce or challenge.
Operational efficiency initiatives (including facility consolidation, divestiture of noncore product lines, and the 80/20 simplification program) are resulting in higher productivity and margin improvement. This should continue to drive both operating margins and free cash flow higher despite near-term tariff and working capital headwinds.
See why 17 investors see Moog as 19% undervalued.
Result: Fair Value of $446.40 (UNDERVALUED)
Still, the Moog story leans heavily on elevated defense budgets and cleaner cash conversion, so any slowdown in spending or persistent working capital drag could quickly test that undervalued tag.
Find out about the key risks to this Moog narrative.
Another View on Moog’s Valuation
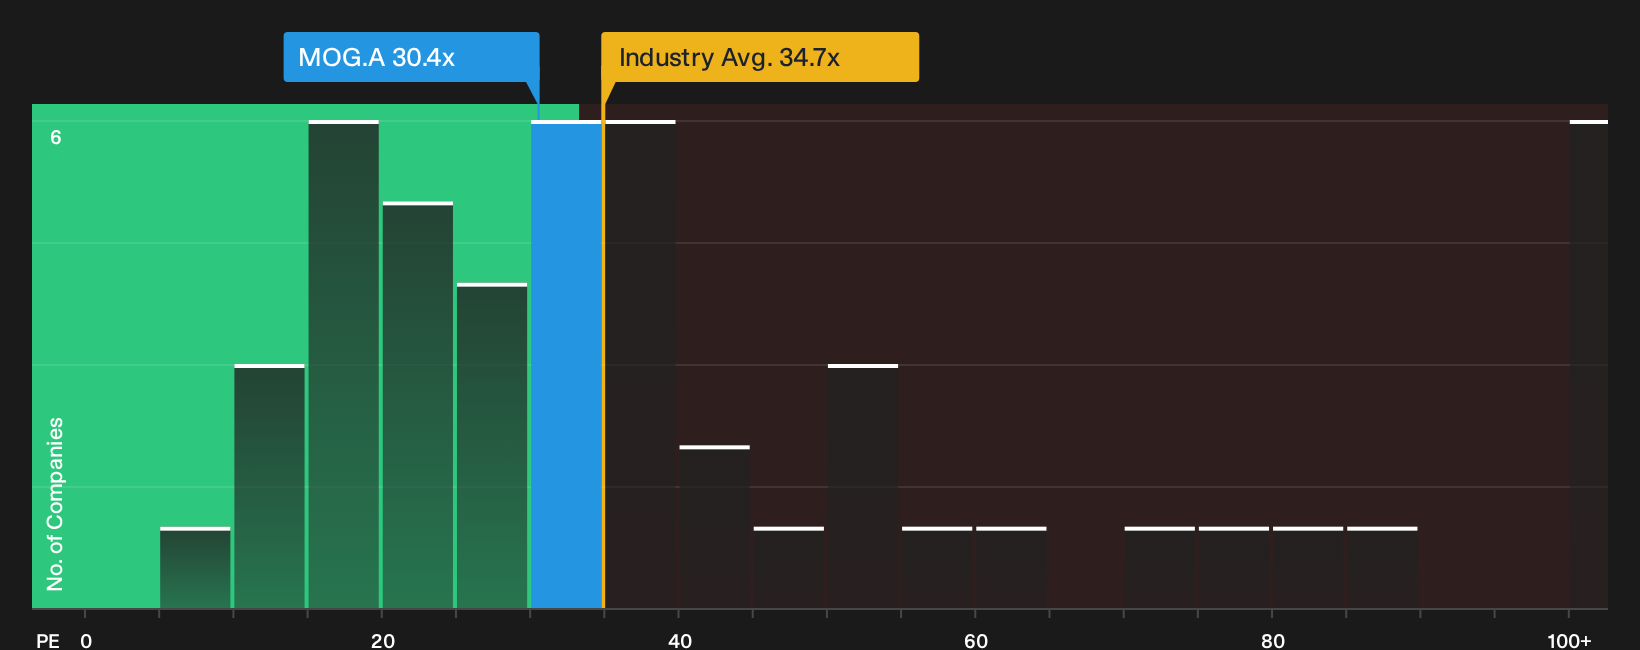
The market story around Moog looks very different when viewed through earnings multiples. The stock trades on a P/E of 30.4x, below the US Aerospace & Defense average of 36.1x, and above an estimated fair ratio of 18.3x. That difference indicates investors are paying a sizeable premium that could unwind if sentiment cools.
Our DCF work is only one lens. The earnings multiple view presents a more demanding picture for Moog. This raises a simple question for you as conferences approach: which narrative feels more realistic if expectations shift?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed about the tone of this Moog story so far. Use the data, pressure test both upside and downside, and weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Moog?
If Moog has sharpened your thinking, do not stop here. Broader opportunity often sits in fresh ideas that match your risk, income, and quality preferences.
- Target resilient quality by scanning a 11 resilient stocks with low risk scores that aims to limit unpleasant surprises while keeping your capital working.
- Hunt for potential mispricing by reviewing a curated 35 high quality undervalued stocks that screens for strong fundamentals at prices that may not fully reflect them.
- Build income potential into your watchlist by checking a focused 6 dividend fortresses that zeroes in on higher yielding opportunities.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com