


Cohu (COHU) has drawn fresh attention after a recent pullback, with the share price closing at US$49.97. The move comes alongside mixed short term returns and a much stronger performance so far this year.
Recent trading has been choppy. The share price return is down 12.46% over one day and 15.73% over the past month, yet Cohu still carries a 103.05% year to date share price gain and a 136.15% one year total shareholder return. This indicates that momentum has built over the longer stretch even as shorter term enthusiasm cools and risk perceptions reset.
Scan how Cohu's sharp pullback compares with other chip related opportunities by reviewing our hand picked list of 60 AI infrastructure stocks.
Bulls see Cohu's pullback as a reset after strong gains, while bears point to recent losses and current net income pressure. Which story does the valuation actually support next?
Most Popular Narrative: 29% Undervalued
Cohu's most followed narrative pegs fair value at $70.88 per share, well above the last close at $49.97. This frames the recent pullback as a move against that longer term thesis.
The push towards automation, data analytics, and AI-driven yield/process optimization through Cohu's software suite (DI-Core, Tignis) supports an ongoing shift to higher-margin, recurring software and services revenue, which is expected to enhance long-term net margins and earnings stability. Strategic diversification into automotive, industrial, precision analog, and display/AR markets (beyond traditional consumer electronics) is increasing the resilience and breadth of Cohu's revenue base, making earnings less vulnerable to cyclical downturns and customer concentration risks.
See why 11 investors see Cohu as 29% undervalued.
Result: Fair Value of $70.88 (UNDERVALUED)
Still, Cohu's reliance on cyclical end markets and concentrated customer ramps means that any delayed qualifications or weaker orders could quickly challenge that 29% undervalued narrative.
Find out about the key risks to this Cohu narrative.
Another View On Cohu’s Valuation
The popular Cohu story leans on a fair value of $70.88, yet the SWS DCF model points in the opposite direction. On that cash flow lens, the estimated value sits around $34 per share, which would leave the current $49.97 price looking expensive rather than cheap. Which yardstick do you trust when the gap is this wide?
To understand how that cash flow based result is built and what would need to change for it to move closer to the narrative fair value, take a closer look at the Look into how the SWS DCF model arrives at its fair value..
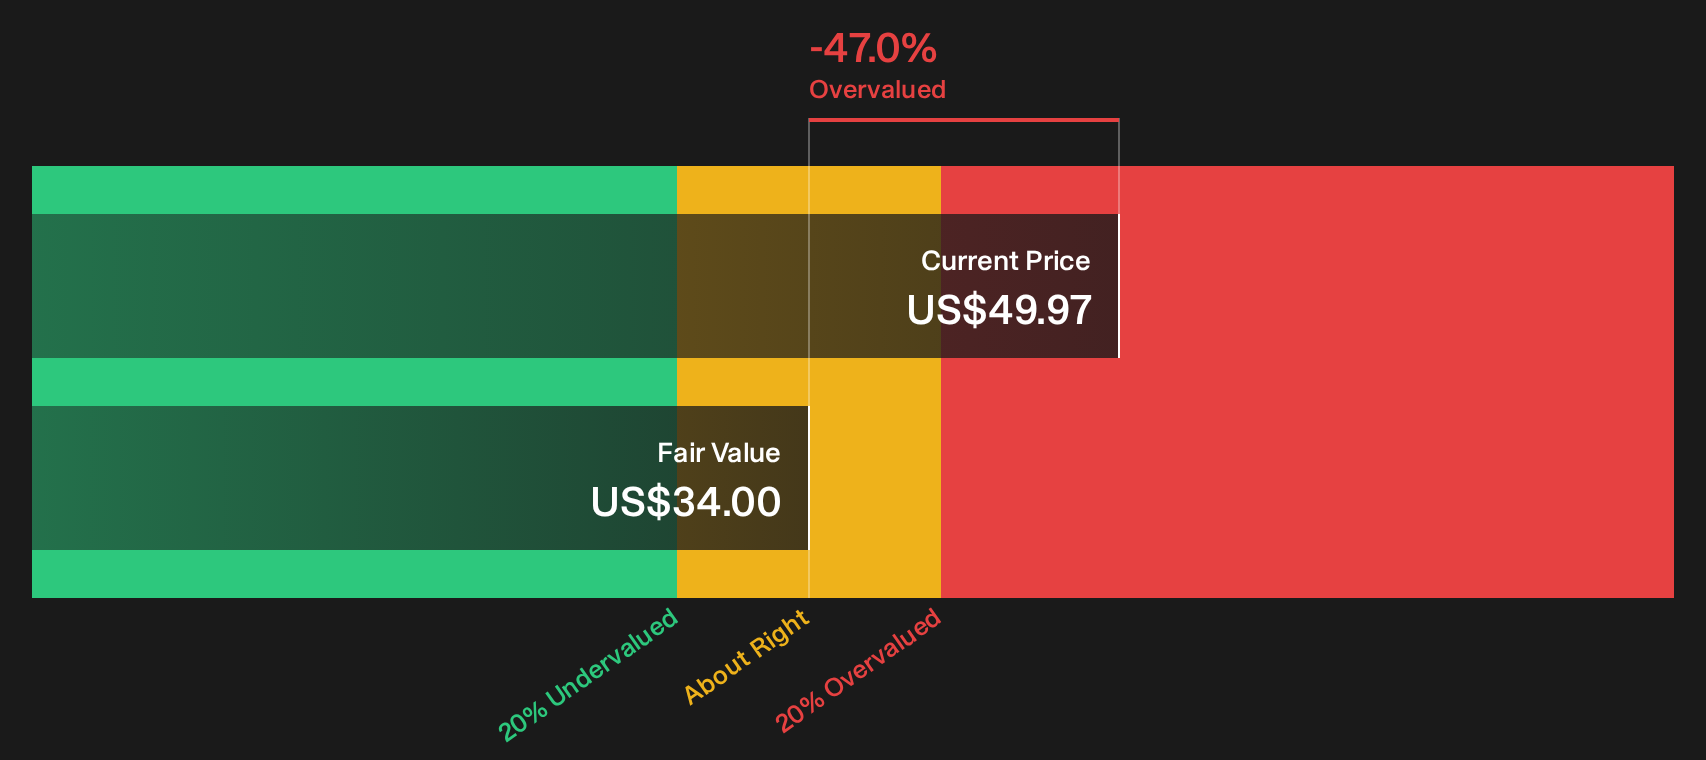
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Cohu for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Cohu's story reflects both strong past returns and emerging concerns. Move quickly, review the underlying numbers, and weigh both sides in the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Cohu?
If Cohu's split valuation story has you thinking bigger, broaden your watchlist with fresh ideas that match different risk levels, income needs, and balance sheet strength.
- Spot potential turnaround opportunities early by scanning 3 elite penny stocks with strong financials that already show stronger financial underpinnings than most tiny tickers.
- Target value driven upside by reviewing the 35 high quality undervalued stocks that combine solid fundamentals with prices that still trail underlying business quality.
- Prioritise resilience in the next downturn by focusing on companies in the 11 resilient stocks with low risk scores that pair steadier metrics with more controlled risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com