


Global trade rules are getting shakier, tariffs keep popping up, and long supply chains look a lot less comfortable than they did a few years ago. That shift creates a clear dividing line between companies that lean on exports and those with more grounded, local cash flows. This article explores that split and highlights three dividend stocks whose business models appear closely tied to the trade risks now in focus.
The three stocks below are only a sample of the idea, and the full screen surfaced 9 more large, dividend-focused businesses with equally compelling stories that are not covered in this article. If you want to go straight to the source and identify which trade-resilient income plays best fit your criteria, analyze them side by side with the Global Trade-Resilient Dividend Stocks screener.
Hirose ElectricLtd (TSE:6806)
Overview: Hirose ElectricLtd designs and manufactures connectors and related electronic components used across consumer devices, cars, telecoms equipment, and industrial machinery. This aligns with the screener by offering diversified, often locally rooted demand rather than relying solely on export heavy end markets.
Operations: Hirose ElectricLtd generates about ¥196.5 billion from multi pin connectors, ¥19.3 billion from coaxial connectors, and ¥8.6 billion from other products, with sales spread across China, Japan, South Korea, and other regions.
Market Cap: ¥784.7 billion
Hirose ElectricLtd combines large scale, connector focused earnings and a credible dividend policy with revenue drawn from multiple Asian and global end markets. That mix fits the trade resilient income theme, even though its products still feed into cyclical electronics and industrial supply chains. This leaves one unseen pressure that could quietly reshape how dependable those cash flows feel.
That quiet pressure is easier to size up when you see the full picture in the 4 key rewards and 1 important warning sign, where potential trade resilience and friction sit side by side.

Aktieselskabet Schouw (CPSE:SCHO)
Overview: Aktieselskabet Schouw is a Danish industrial group led by BioMar, which supplies fish and shrimp feed that ties neatly into a trade resilient, food and aquaculture dividend theme.
Operations: Aktieselskabet Schouw generates DKK16.5b from BioMar and DKK8.7b from GPV, with smaller contributions from HydraSpecma, Fibertex units, and Borg Automotive.
Market Cap: DKK17.8b
Aktieselskabet Schouw taps straight into the Global Trade Resilient Dividend Stocks idea because its core aquaculture feed business serves everyday food demand rather than discretionary spending. This can matter when global trade rules look unsettled and income investors want steadier cash generation.
"Ongoing expansion of BioMar's feed volumes, supported by long-term demand for healthy, protein-rich food sources and increasing aquaculture adoption, positions Schouw for sustained revenue and margin growth as global dietary trends shift and middle class consumption rises."
What really decides how dependable that story feels is how one less visible funding pressure shapes future margin headroom when conditions tighten.
That hidden funding squeeze is exactly where the full narrative for Aktieselskabet Schouw shows whether Aktieselskabet Schouw’s aquaculture engine is quietly decoupling from trade risk or masking new fragility.

HORIBA (TSE:6856)
Overview: HORIBA supplies measurement and analytical equipment and services used across energy, healthcare, materials, mobility, and semiconductor industries worldwide.
Operations: HORIBA generates about ¥180.7b from Advanced Materials & Semiconductor, ¥138.5b from Energy Environment, and ¥44.8b from Bio Healthcare, supported by sizable sales in Japan and wider Asia.
Market Cap: ¥905.6b
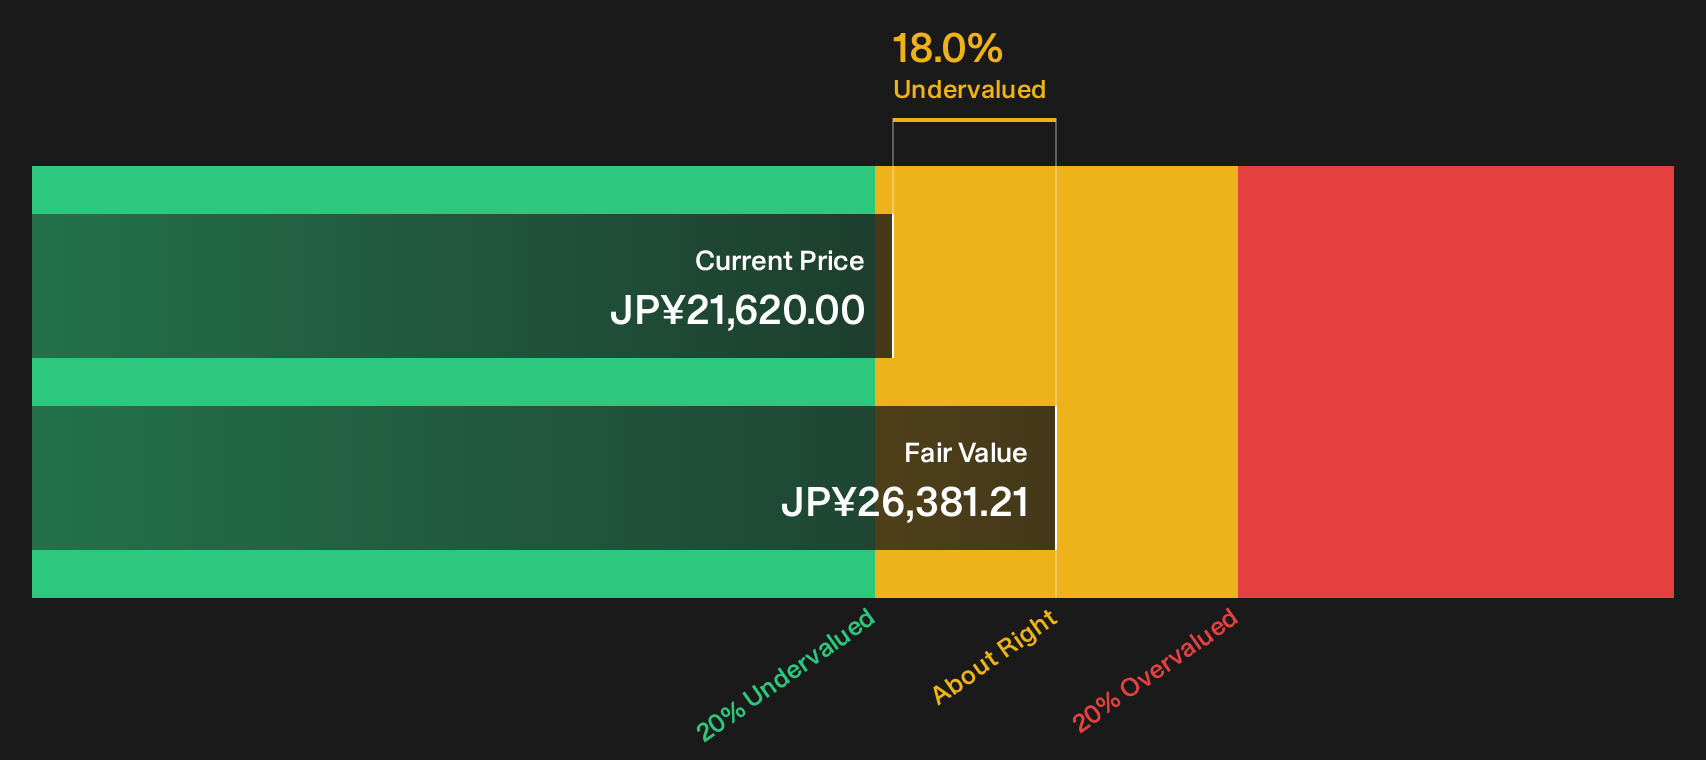
HORIBA fits a trade resilient dividend idea because recurring demand for testing gear and services supports cash flow even when trade flows are uneven. The stock trades below an internal fair value estimate, yet income investors still need to watch how one unresolved funding risk shapes future payout comfort and valuation support.
That funding question is exactly where the 3 key rewards and 2 important warning signs surfaces whether HORIBA’s payout comfort and valuation ceiling are quietly shifting under the hood.
Curious About The Next Big Alternatives
Fresh ideas move first. By the time momentum is flying, the cleanest entry points can be gone. Scan these under the radar lists now and get in early.
- Spot cash rich businesses before the crowd and sift through the list of solid balance sheet and fundamentals (19 results) that keep funding flexibility front and center while it still matters.
- Ride the next infrastructure breakout by tracking the 38 power grid technology and infrastructure stocks quietly building momentum as grids modernize and capital shifts toward reliability.
- Target future automation leaders by scanning the curated 38 robotics and automation stocks quietly compounding know how while headline chasers look elsewhere.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com