


NPK International has delivered a very strong share price run over recent years, which naturally raises a blunt question for anyone looking at the stock today. Is the current valuation still supported by the earnings that underpin it, or has the share price moved ahead of the business performance that investors are paying for?
- Over the past 5 years, NPK International has returned about 375.1%, so a lot of future earnings power is already being treated as important to the story.
- The business model now puts more weight on how consistently it can convert its operations into earnings, which can shape how durable any current P/E or related earnings multiple looks.
- The analysts covering NPK International have run their own numbers. See what analysts think NPK International's shares could be worth.
The stock's next move may depend on whether NPK International's current earnings profile is strong enough to justify the price investors are paying today.
If you are weighing whether NPK International's strong 5 year run still lines up with its earnings, it can help to compare it with a wider list of 35 high quality undervalued stocks.
Does NPK International Look Pricey on Earnings?
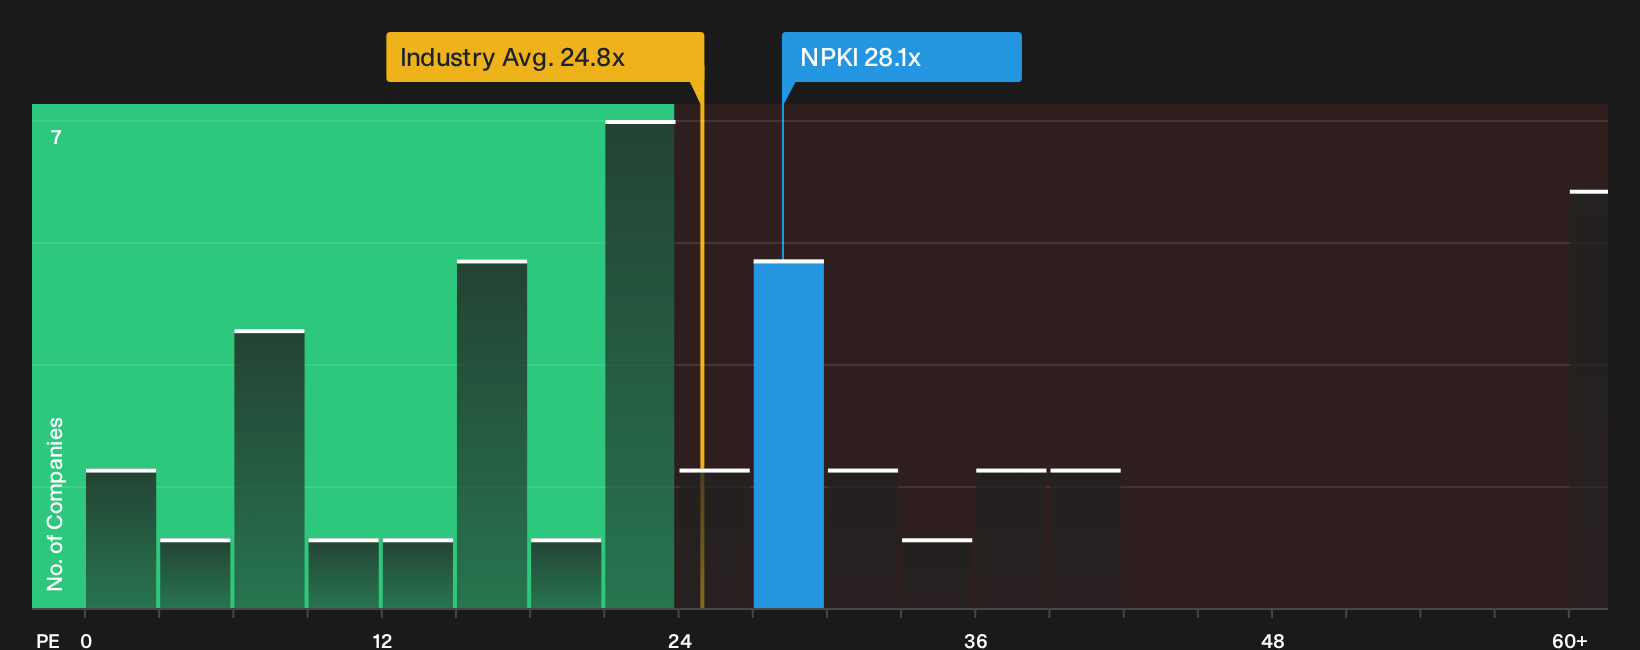
The P/E ratio suits NPK International because earnings are central to how investors seem to be framing the story right now. On this metric, the stock trades on roughly 28.1x, which is higher than the Trade Distributors sector average of about 24.8x. The gap suggests you are paying a premium price for each dollar of current profit compared with the broader industry.
Against a more tailored fair multiple, which adjusts for NPK International's growth profile, profitability, size and risk, the current P/E also screens on the expensive side rather than cheap. The peer group average near 57.5x is much richer, so the stock does not look stretched in relative terms to that set. However, the earnings yield you get at 28.1x still assumes a lot about the durability of the existing profit base. That tension between a higher than modelled fair value and a lower than peer tag is what you need to weigh. Explore the numbers behind NPK International's P/E valuation.
The NPK International Narrative: What Would Justify Today's Price?
Narratives for NPK International pick up where the valuation question leaves off and explain what kind of growth, margins and earnings profile would need to hold for the stock to be worth materially more or less than today’s price. Each narrative lays out the assumptions behind its view of fair value in a transparent way so you can compare those expectations with NPK International's actual results as they are reported over time on Simply Wall St's Community page.
One of the top community narratives on NPK International: 36% undervalued
"Strong and flexible balance sheet with ample liquidity allows continued investment in fleet expansion, operational efficiency, and share repurchases..."
Discover why this Narrative puts NPK International at 36% undervalued.
One last NPK International check that sits beyond the share price
Before you stop at the P/E and community narratives, it is worth asking who is steering NPK International and how their pay packets line up with your interests as a shareholder. See who runs NPK International and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com