


When 10 year Treasury yields touch 5%, mortgage rates push above 7% and oil trades over $100 a barrel, the cost of money and the cost of energy suddenly matter a lot more to every portfolio. Refiners exposed to gasoline and diesel trends can end up on the right or wrong side of that squeeze. This piece breaks down three U.S. Oil & Gas Refiners stocks that screens suggest may be better placed in this macro crosswind.
The three refiners highlighted below are only a sample of what screens are flagging, with the full U.S. Oil & Gas Refiners universe surfacing 13 more companies whose business stories look just as interesting. To identify which fuel processors match your risk, income and valuation preferences fastest, head straight into the U.S. Oil & Gas Refiners screener
Delek US Holdings (DK)
Delek US Holdings is the clearest pure play on the U.S. Oil & Gas Refiners theme in this context, with a business built around turning crude into gasoline and diesel for domestic drivers and haulers, and a logistics arm that helps capture additional value from those refining economics.
"Substantial investment in logistics and midstream infrastructure, especially the ramp-up of growth projects at DKL, is expected to materially lower feedstock and transportation costs, while growing third-party business and unlocking new earnings streams, positively contributing to net margins and EBITDA."
What matters now is how one pressure on future refining profits resolves as fuel markets and funding costs continue to shift.
Delek US Holdings runs a U.S.-focused downstream operation, with about US$11.9b of revenue from refining and US$1.2b from logistics, and a roughly US$4.7b market cap that directly ties investor exposure to domestic fuel demand and crack spreads.
That pressure point is where the story gets interesting, and the full narrative for Delek US Holdings maps how Delek US Holdings could turn today’s margin squeeze into accelerating earnings power.

Texas Pacific Land (TPL)
Texas Pacific Land plugs into the U.S. Oil & Gas Refiners theme from a different angle, giving you exposure to Permian crude economics through royalties, land use and water services rather than owning refineries or chasing crack spreads directly.
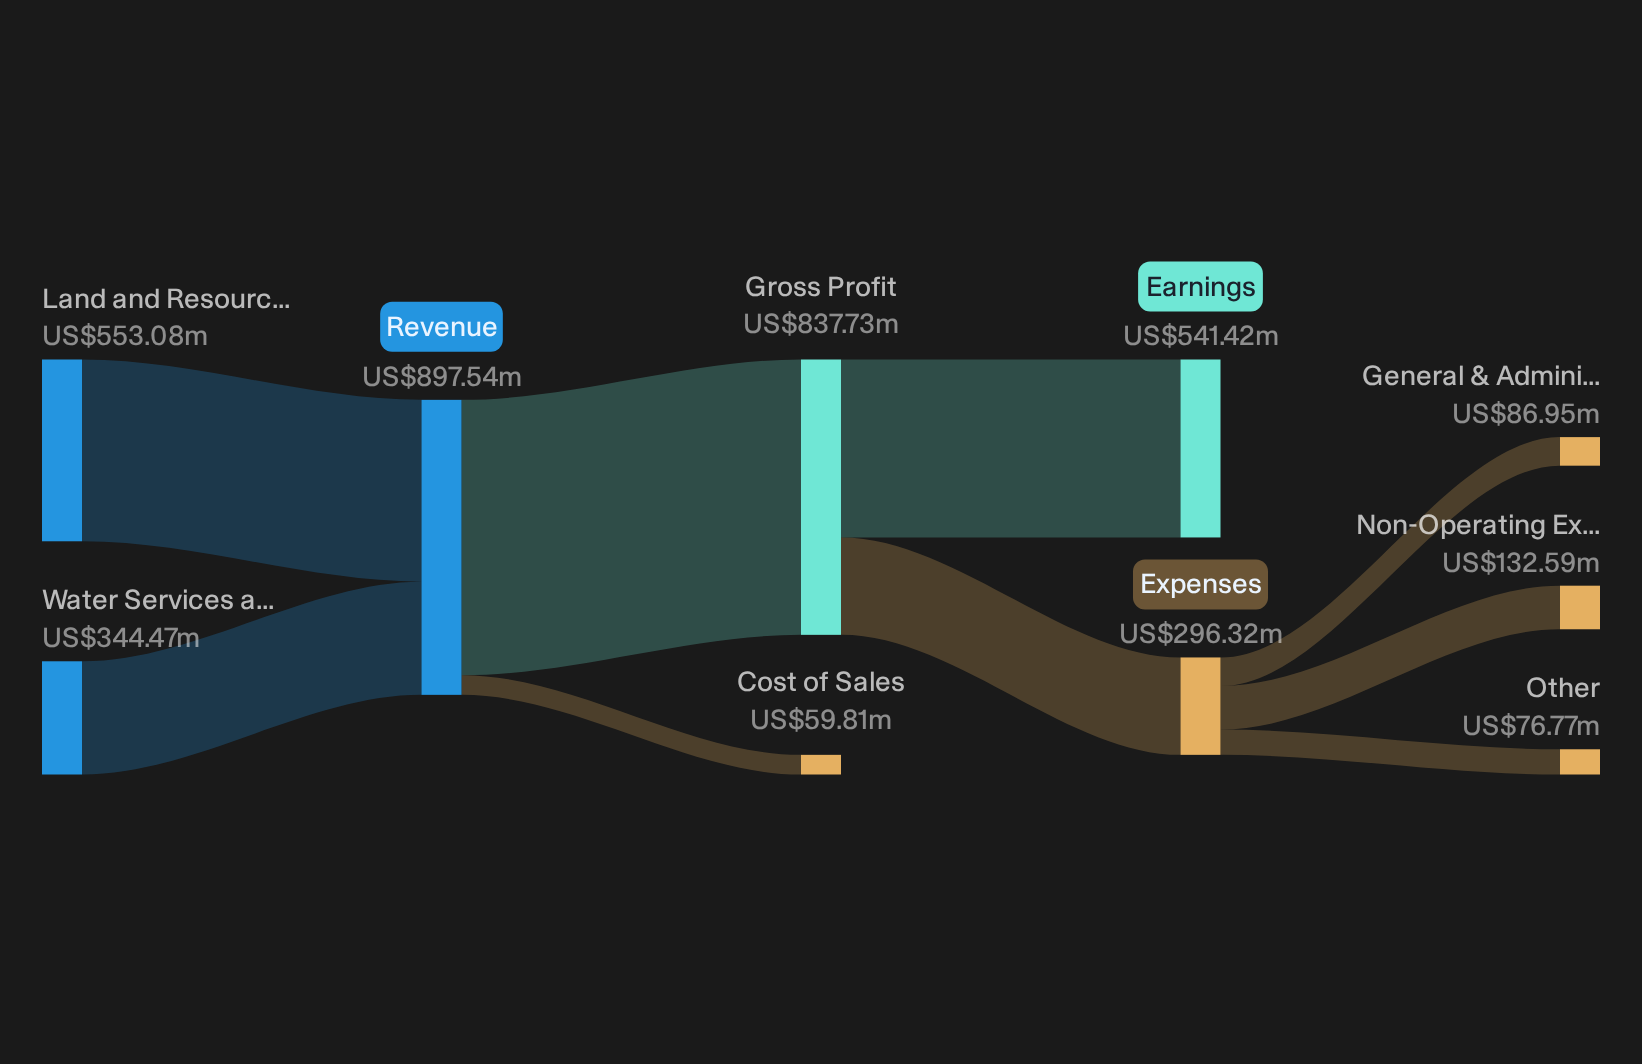
Texas Pacific Land earns about US$553 million from Land and Resource Management and roughly US$344 million from Water Services and Operations, all in the United States, with a market value near US$25.5b.
"Investors might be overly optimistic about Texas Pacific Land's ability to maintain strong royalty revenue growth in the face of long-term shifts toward decarbonization and electrification, which could reduce oil and gas demand and thereby pressure royalty income, negatively impacting long-term revenue and earnings."
What really matters is how one slow moving shift in energy demand eventually feeds back into pricing power, volumes and Texas Pacific Land’s margins.
That slow shift is exactly why reading the full narrative for Texas Pacific Land can help you see where Texas Pacific Land’s royalty engine could be masking future upside or risk.
World Kinect (WKC)
World Kinect links this refiners screen to the broader fuel chain by managing and distributing refined products across aviation, land and marine markets. This makes its push into cleaner energy a key part of how investors may want to think about the stock today.
World Kinect is an energy management specialist tied to refined fuel flows, with US$22.6b from Aviation, US$10.4b from Land and US$8.7b from Marine activity, and a market value of about US$1.8b.
"The company is exceptionally well-positioned to capitalize on the accelerating global demand for renewable fuels and carbon reduction solutions, having already built operational capabilities and customer relationships in renewables; this first-mover advantage could unlock large new revenue streams as regulation and customer preference shifts accelerate, substantially lifting both topline and margins."
What happens to those ambitions if a single pressure on fuel demand and pricing cuts against the assumptions baked into that renewables push?
If that pressure point matters to your thesis, full narrative for World Kinect to see how World Kinect’s renewables push could be accelerating strengths or quietly masking new risks.

Seeking Alternatives Before The Crowd
Fresh ideas move first. Breakout stories gain momentum, while late entries get caught chasing. Scan these under the radar for now opportunities while it matters and get in early.
- Spot cash rich balance sheets, then use the curated list of solid balance sheet and fundamentals (23 results) to see which businesses might hold up when weaker players start dropping.
- Ride structural AI momentum by checking the hand picked 60 AI infrastructure stocks before infrastructure leaders stop flying under the radar.
- Target income that works harder and review the curated 6 dividend fortresses while yields and payout strength still look attractive.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com