


Zillow Group has seen its share price pressure build over the past year, and that slump puts sharper focus on a simple question for you as an investor: Is the current valuation supported by the earnings power of the real estate platform, or has the stock price moved out of sync with what the business is generating today?
- The share price has fallen 64.7% over the past 5 years, which puts long term holders in a difficult spot and raises the stakes for whether ongoing earnings can justify staying invested.
- Zillow's August Market Report pointed to softer home sales as higher mortgage rates kept buyers on the sidelines, which can feed into expectations for how quickly the company converts its audience and product set into sustainable earnings.
- Your read on Zillow Group is one view; the desks covering it have another. See what analysts think Zillow Group's shares could be worth.
The stock's next move may depend on whether Zillow Group's current price can be squared with what its earnings say the business is worth today.
If you are weighing whether Zillow Group’s earnings justify today’s share price, it can help to compare it with other companies screened for 35 high quality undervalued stocks.
Is Zillow Group Getting Expensive on Earnings?
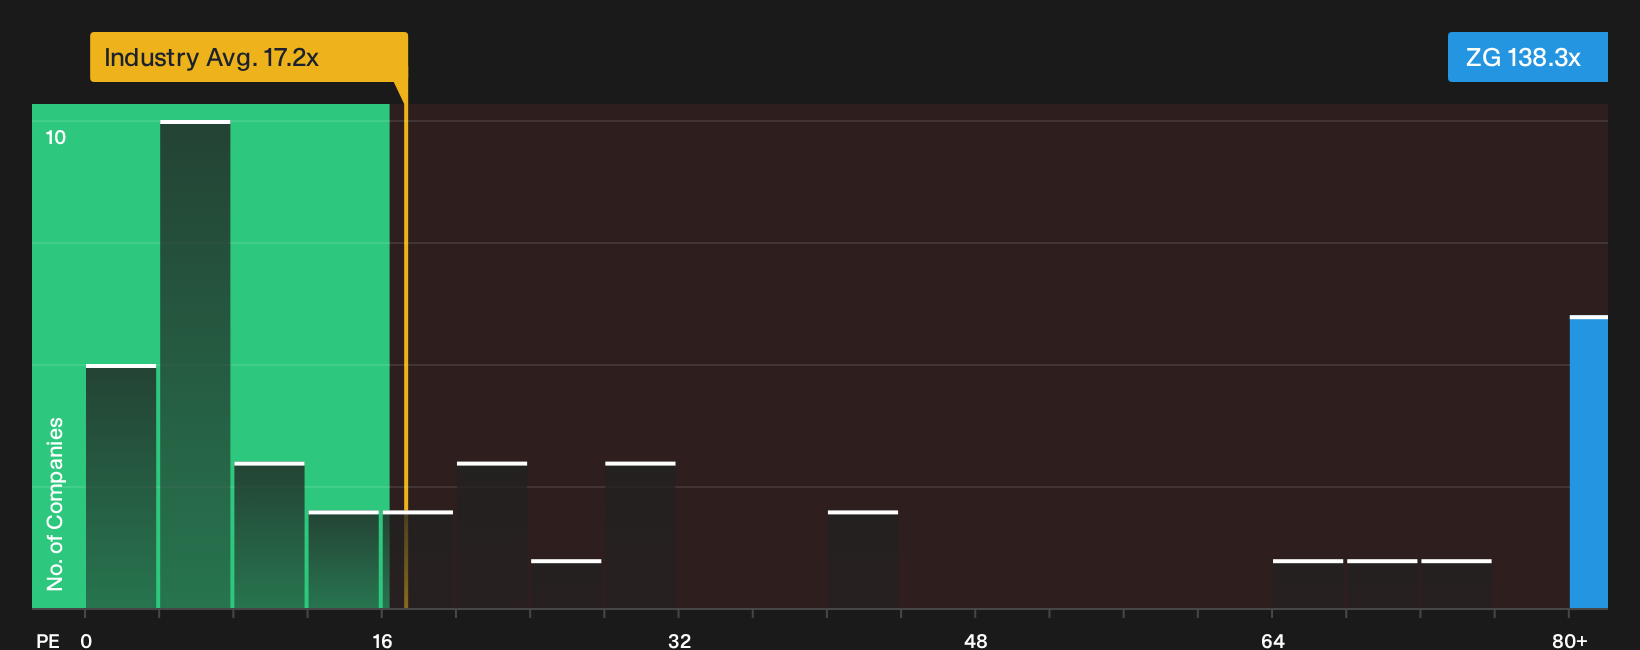
The P/E ratio works well for Zillow Group because earnings are now positive and give you a concrete profit figure to compare with the share price. On this measure, the stock trades on a P/E of 138.3x, which is far above the wider real estate sector average of 17.2x and also well above peers at 81.3x. That gap means you are paying a much higher price per dollar of current earnings than investors in similar businesses.
The Fair Ratio model, which looks at factors like growth potential, profitability and risk profile for Zillow Group, points to a lower P/E level than where the shares change hands today, so the stock screens as overvalued on this yardstick. Because the August market report flagged slower home sales as higher mortgage rates kept buyers away, the current premium P/E suggests the market is still assigning a rich valuation despite softer housing activity. Explore the numbers behind Zillow Group's P/E valuation.
The Zillow Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for Zillow Group leaves off and explain what growth, margin and earnings paths would need to hold for the stock to be worth materially more or less than today’s price, all hosted on the Community page.
Each narrative presents Zillow Group's fair value as a thesis about how the business might perform that you can track over time rather than as a single static estimate.
The community is split on Zillow Group, with one camp seeing meaningful upside and the other arguing the recent price already bakes in the good news.
Bull case: 46% undervalued
"The accelerated digital transformation of real estate, combined with Zillow's leading traffic, engagement, and product innovation including AI powered tools and immersive experiences, positions the company to expand market share..."
Discover why this Narrative puts Zillow Group at 46% undervalued.
Bear case: 6% overvalued
"Competitive and legal pressures are front of mind, with rising concern over Google expanding real estate listings ads, ongoing portal competition, MLS disputes, and legal costs that could weigh on margins and sentiment..."
Explore why this Narrative puts Zillow Group at 6% overvalued.
One more angle on Zillow Group that could shift your view
Share price and earnings only tell part of the story, because the people setting Zillow Group’s course and how they are rewarded can quietly tilt risk and reward for shareholders. See who runs Zillow Group and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com