


Conference appearances put NewAmsterdam Pharma in focus
NewAmsterdam Pharma (NasdaqGM:NAMS) heads into a busy investor week, with management scheduled to appear at the Wells Fargo 21st Annual Healthcare Conference on September 9 and the Cantor Fitzgerald Global Healthcare Conference on September 10.
These back to back conferences give executives a platform to update institutions on the late stage cardiometabolic pipeline, outline current financial trends, and respond to questions about how the business is approaching its next phase of clinical and commercial execution.
Recent trading has been tougher for NewAmsterdam Pharma, with the share price down 11.97% over the past week and 36.48% year to date. A much stronger 3 year total shareholder return of 127.70% signals earlier enthusiasm that recent declines have started to cool.
Scan beyond NewAmsterdam Pharma and line up other cardiometabolic and healthcare prospects using our curated list of 15 high quality undiscovered gems for ideas that may still be under the radar.
After a sharp pullback and with NewAmsterdam Pharma trading well below both its analyst target and intrinsic value estimate, the gap between price and implied worth has widened. How far does fair value sit from here?
DCF gap on NewAmsterdam Pharma is hard to ignore
On Simply Wall St's numbers, NewAmsterdam Pharma carries an estimated future cash flow value of $132.79 per share, compared with the last close at $22.36. That gap implies the stock is trading well below the SWS DCF model output based on current inputs.
The SWS DCF model projects a stream of future cash flows for NewAmsterdam Pharma, then discounts those estimates back to today using a required rate of return. The output is a single present value figure, which provides a reference point for where the share price might sit if those cash flows eventuate as expected.
For a late stage biopharma group with limited current revenue of $7.12m and a reported net loss of $259.50m, cash flow modelling becomes a key tool in the absence of conventional earnings based metrics. Forecast revenue growth of 58.3% per year and earnings growth expectations of 65.25% per year feed into those projections, although the business is still loss making and is forecast in some models to remain unprofitable on a 3 year view.
That mix of high growth forecasts, current losses, and an 83.2% discount to the SWS DCF estimate means NewAmsterdam Pharma sits in a part of the market where small changes to assumptions can have a large impact on fair value outputs.
Look into how the SWS DCF model arrives at its fair value.
Result: DCF Fair value of $132.79 (UNDERVALUED)
Still, NewAmsterdam Pharma hinges on successful late stage trials and future funding access, and setbacks on either front could quickly challenge the current valuation story.
Find out about the key risks to this NewAmsterdam Pharma narrative.
Another view on NewAmsterdam Pharma's valuation
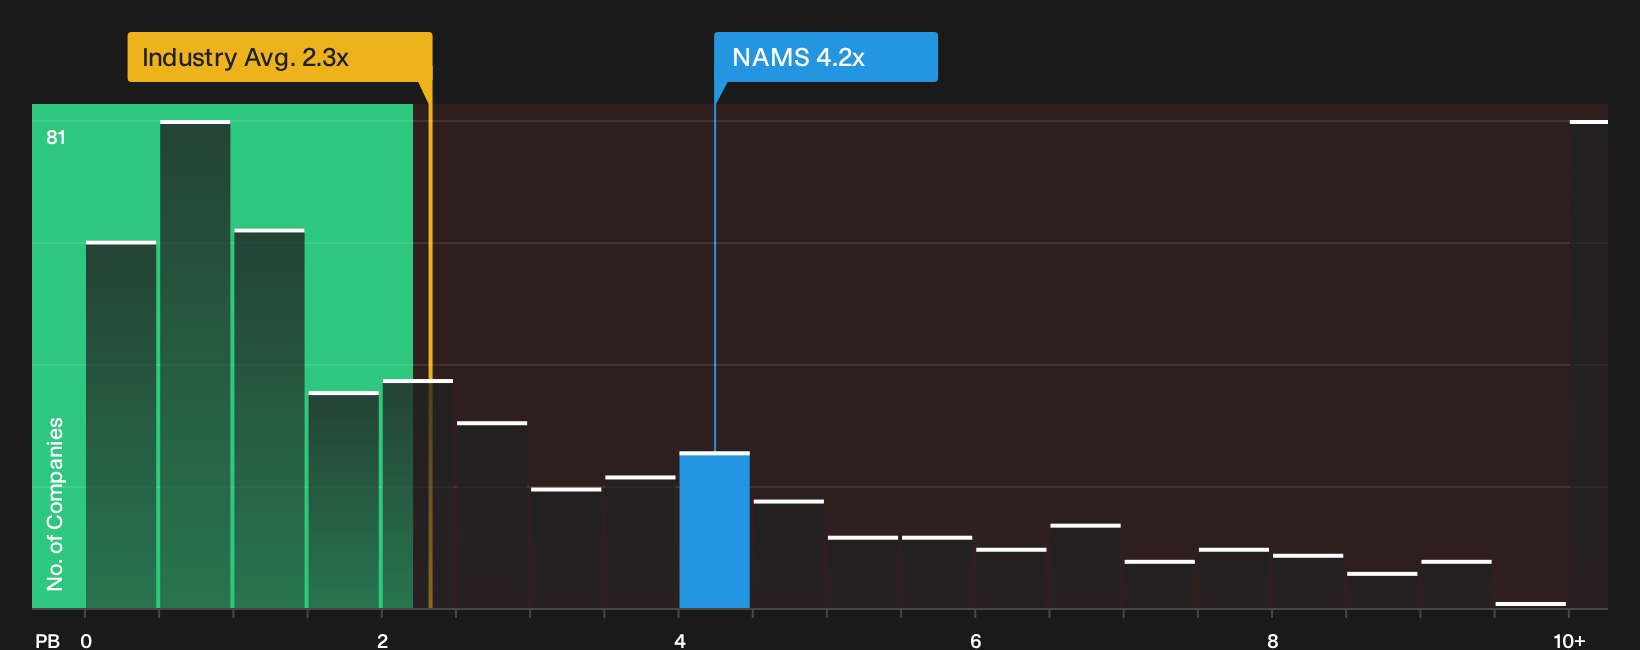
Price-based ratios tell a very different story for NewAmsterdam Pharma. The stock trades on a P/B of 4.2x, which is higher than both the US biotech sector average of 2.3x and the peer group at 4x. That richer multiple can point to valuation risk if sentiment cools.
High growth forecasts and a premium P/B beside a sharp discount to fair value leave a split picture. Which signal do you trust more when capital is on the line: the cash flow model, or what the market is currently willing to pay per dollar of equity?
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out NewAmsterdam Pharma for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of caution and optimism around NewAmsterdam Pharma feels hard to reconcile, it may help to stress test the assumptions yourself and weigh the upside against the risks that matter most to you. Then take a closer look at the 3 key rewards
Looking for more NewAmsterdam Pharma style investment ideas?
If NewAmsterdam Pharma has sharpened your focus on risk, reward, and valuation gaps, do not stop here. The next decision could come from casting a wider net across other opportunities that fit your style, risk tolerance, and time horizon.
- Target value hunting opportunities by scanning a curated pool of underpriced quality with the 35 high quality undervalued stocks.
- Prioritise resilience and support a calmer investing approach by tracking candidates screened for stronger financial footing through the list of solid balance sheet and fundamentals (23 results).
- Lean toward stability and potential income by reviewing companies grouped as "6 dividend fortresses".
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com