


Amidst the backdrop of fluctuating oil prices and global economic concerns, the Australian market is navigating a complex landscape with energy and mining sectors under pressure, while technology stocks face renewed scrutiny. In this environment, identifying promising small-cap stocks that can withstand inflationary pressures and interest rate fluctuations becomes crucial for investors seeking to uncover hidden opportunities.
Top 5 Undiscovered Gems With Strong Fundamentals In Australia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| West African Resources | 19.46% | 25.90% | 27.84% | ★★★★★★ |
| Clover | NA | 4.04% | -7.76% | ★★★★★★ |
| Black Cat Syndicate | NA | 93.32% | 51.74% | ★★★★★★ |
| EDU Holdings | NA | 39.57% | 73.27% | ★★★★★☆ |
| Servcorp | NA | 7.33% | 26.11% | ★★★★☆☆ |
| CTI Logistics | 31.77% | 6.42% | 11.72% | ★★★★☆☆ |
| Lindsay Australia | 67.18% | 15.96% | 9.84% | ★★★☆☆☆ |
| Pepper Money | 2129.01% | -1.51% | -6.89% | ★★★☆☆☆ |
Here's a peek at a few of the choices from the screener.
Black Cat Syndicate (ASX:BC8)
Simply Wall St Value Rating: ★★★★★★
Overview: Black Cat Syndicate Limited, with a market cap of A$703.36 million, is involved in the mining and processing of gold properties in Western Australia through its subsidiaries.
Operations: The company generates revenue primarily from its Kal East Gold Operation and Paulsens Gold Operation, contributing A$156.79 million and A$217.50 million respectively.
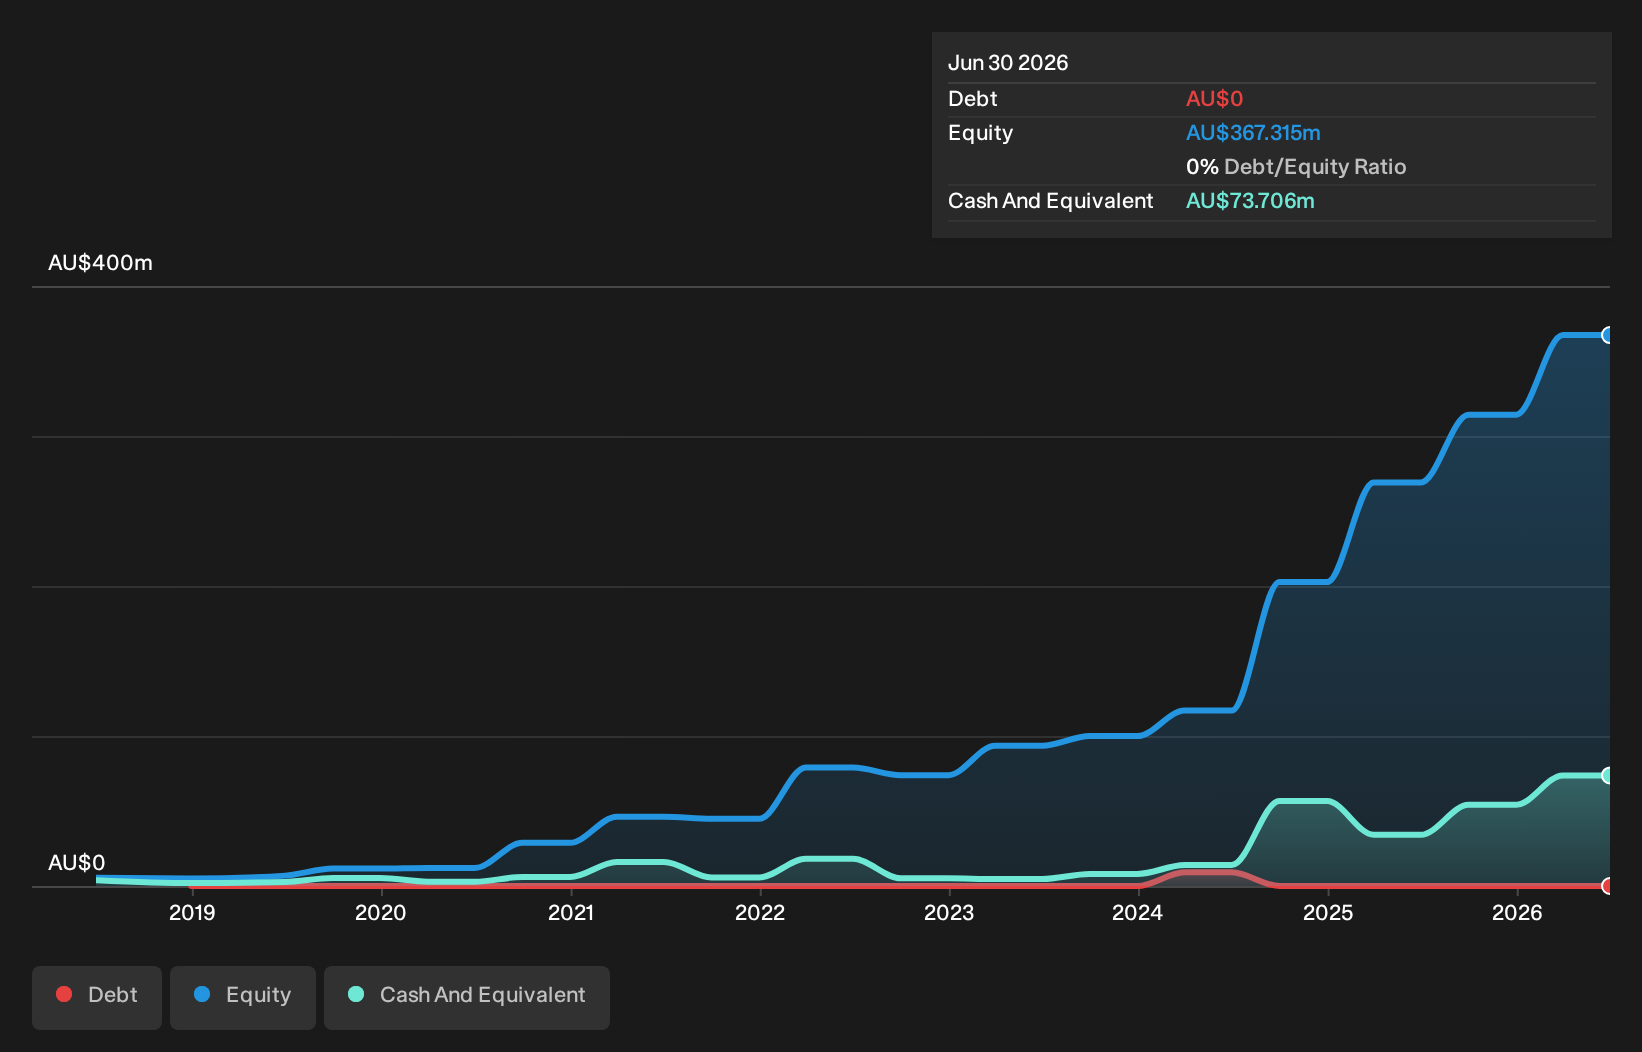
Black Cat Syndicate, an intriguing player in the mining sector, recently reported a significant leap in sales to A$374.29 million from A$37.32 million the previous year, reflecting its dynamic growth trajectory. The company turned around its financial performance with a net income of A$86.46 million compared to a loss of A$25.95 million last year, showcasing an impressive recovery and profitability boost. With gold production soaring to 90,833 oz from 39,169 oz—a remarkable increase—this debt-free entity is trading at 26.6% below estimated fair value and benefits from high-quality earnings and strategic leadership changes with Chris Stone joining as director.
- Click here to discover the nuances of Black Cat Syndicate with our detailed analytical health report.
Explore historical data to track Black Cat Syndicate's performance over time in our Past section.
Pepper Money (ASX:PPM)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Pepper Money Limited is a non-bank lender specializing in mortgage and asset finance in Australia and New Zealand, with a market capitalization of approximately A$784.16 million.
Operations: Pepper Money generates revenue primarily from its Mortgages segment, contributing A$202 million, and Asset Finance, adding A$182.90 million. The Loan and Other Servicing segment adds an additional A$20.20 million to the revenue stream.
Pepper Money, a nimble player in the non-bank lending arena across Australia and New Zealand, is leveraging AI and tech-driven platforms to boost efficiency. Despite its high net debt to equity ratio at 2018%, the company has trimmed its debt from 2756.2% over five years while trading at a significant discount of 67.4% below estimated fair value. With a forecasted earnings growth of 14.78% annually, Pepper Money's diverse offerings like prime mortgages and Sharia loans cater to niche markets amidst tightening bank credit policies, yet competition from fintechs may pressure profit margins despite recent dividend increases to A$0.072 per share.

West African Resources (ASX:WAF)
Simply Wall St Value Rating: ★★★★★★
Overview: West African Resources Limited is involved in the mining, mineral processing, acquisition, exploration, and project development of gold projects in West Africa with a market cap of A$4.21 billion.
Operations: The primary revenue stream for West African Resources Limited is derived from its gold mining operations. The company has a market capitalization of A$4.21 billion, reflecting its significant presence in the gold sector in West Africa.
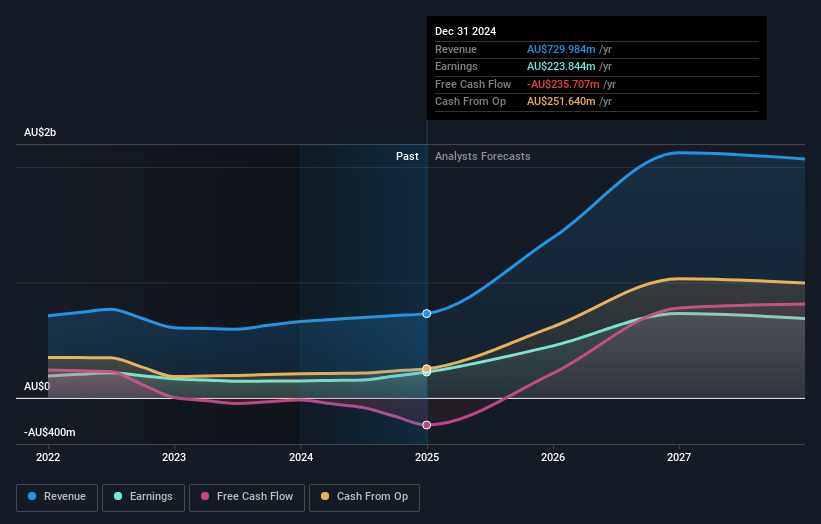
West African Resources, a dynamic player in the metals and mining sector, has shown impressive growth with earnings surging 95% over the past year. The company's debt to equity ratio has significantly improved from 60.8% to 19.5% over five years, indicating prudent financial management. Its interest payments are well-covered by EBIT at a robust 23x coverage, showcasing strong operational performance. Despite profit margins dipping to 25% from last year's 38%, it trades at an attractive valuation of about 85% below estimated fair value. Recent announcements include a special dividend of A$0.2 per share and net income of A$351 million for H1 2026.
Taking Advantage
- Navigate through the entire inventory of 8 ASX Undiscovered Gems With Strong Fundamentals here.
- Have a stake in these businesses? Integrate your holdings into Simply Wall St's portfolio for notifications and detailed stock reports.
- Invest smarter with the free Simply Wall St app providing detailed insights into every stock market around the globe.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com