


- Novartis reported Phase III REMODEL-1/-2 data showing that remibrutinib reduced annualized relapse rates and MRI lesions versus teriflunomide in adults with relapsing multiple sclerosis, with a favorable safety profile and plans to seek global regulatory approval.
- The remibrutinib readout adds another late-stage asset alongside existing priority brands and reinforces Novartis' focus on high-value immunology and neuroscience therapies that can support its broader push for higher quality revenue.
- We will now look at how Novartis' investment narrative could be shaped by the Phase III remibrutinib results in relapsing multiple sclerosis.
Novartis Investment Narrative Recap
To stay a shareholder in Novartis, you need to believe the drug pipeline and existing blockbusters can offset pricing pressure, patent expiries and a relatively high debt load. The near term story is about execution on late stage assets in immunology and neuroscience, plus maintaining momentum in priority brands, while margins stay supported by efficiency gains.
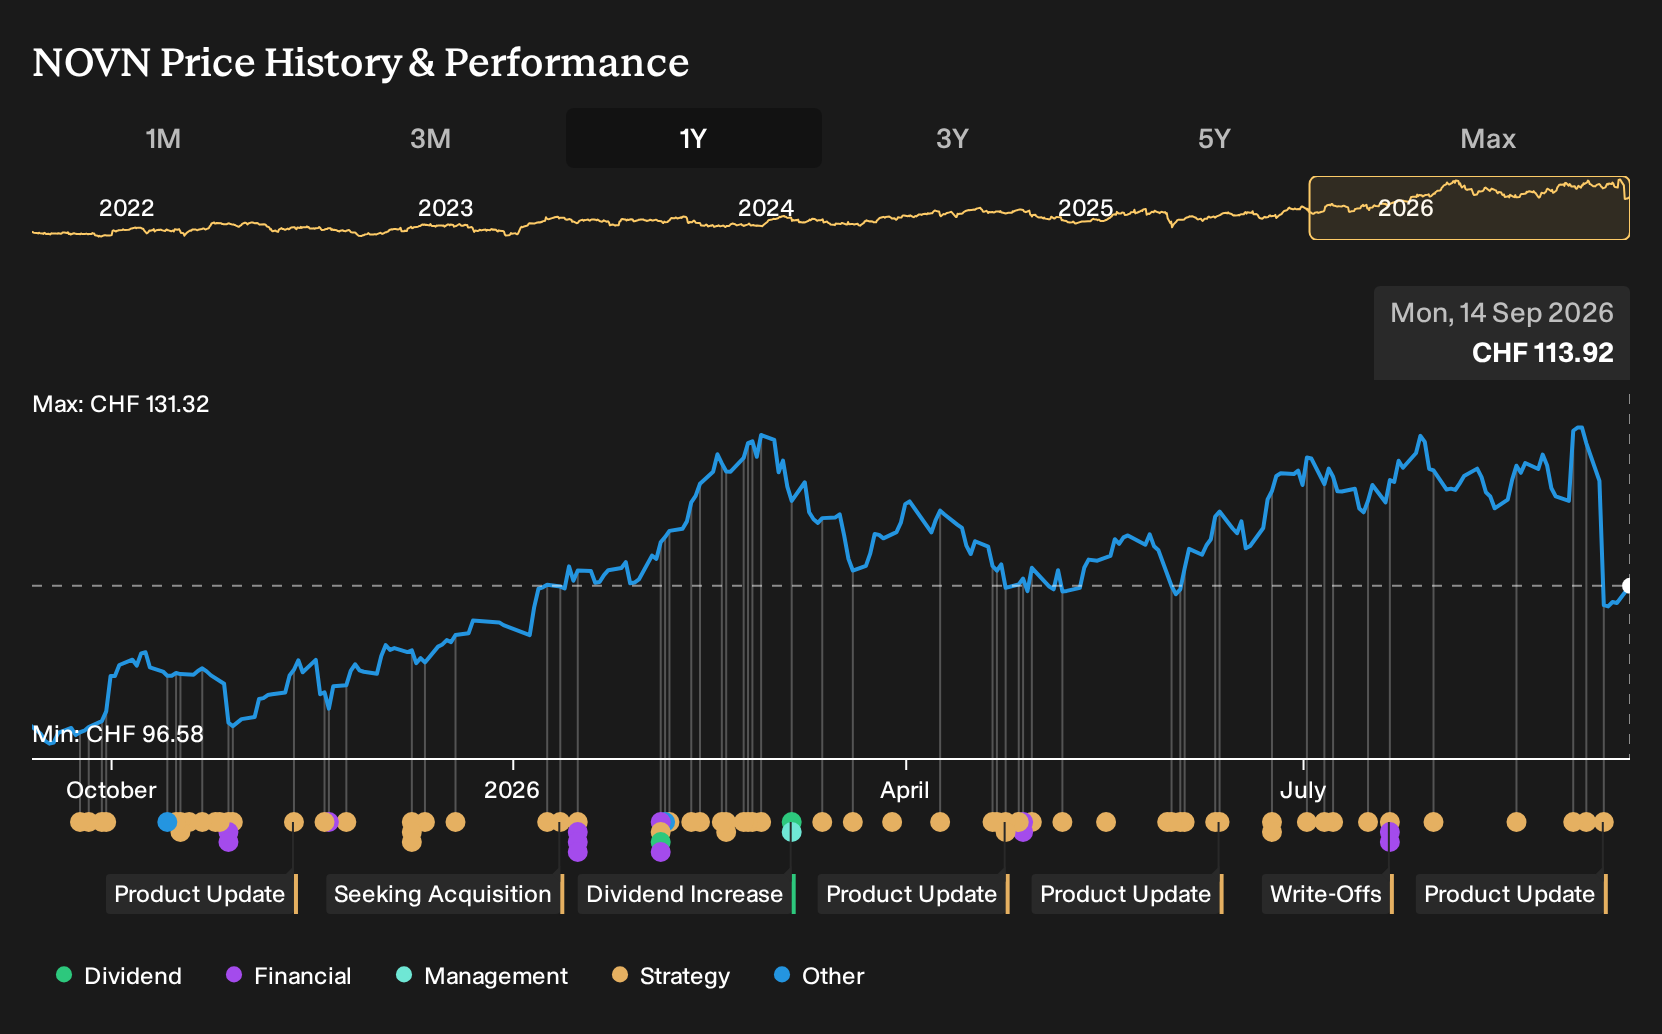
The latest updates are mixed but do not materially change that core premise. Positive remibrutinib data in relapsing multiple sclerosis supports the neuroscience focus, while the pelacarsen and del-desiran trial outcomes underline that pipeline risk remains the biggest operational swing factor and the main near term business risk.
The pelacarsen Lp(a)HORIZON miss is the clearest reminder of that risk. A high profile cardiovascular program did not meet its primary endpoint. As a result, whatever upside investors were mentally assigning to a potential Lp(a) franchise now looks more uncertain and reliance on other late stage assets to support future revenue and earnings growth has increased.
For you, this sharpens the catalyst map. More weight shifts toward regulatory and commercial execution for remibrutinib in multiple sclerosis and for assets like delpacibart zotadirsen in Duchenne muscular dystrophy, along with lupus nephritis programs such as ianalumab and rapcabtagene autoleucel. Novartis still has many shots on goal, but each big readout now matters more.
Novartis' current analyst narrative points to US$67.5b in revenue and US$18.3b in earnings by 2029, based on a 6.0% yearly top line growth assumption and a move from US$12.8b in earnings today. This implies an earnings increase of about US$5.5b from current levels.
Uncover why Novartis' fair value highlights an 8% potential upside to its current price that could close faster than many investors expect.
Exploring Other Perspectives
One alternate angle puts far more weight on late stage drug risk around pelacarsen and the Avidity programs than on remibrutinib’s success. The most optimistic analysts were pencilling in up to US$74.2b in revenue and US$21.5b in earnings by 2029. You can see how views stretch, and why this DM1 setback may reshape those narratives.
Explore 3 other Novartis fair value estimates, including one that suggests as much as 163% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Novartis research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Novartis. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, making it easy to evaluate Novartis' overall financial health at a glance.
Looking for more Novartis style investment ideas?
If the Novartis story has sharpened your thinking on drug pipelines, risk and reward, it can help to widen the lens and line this up against other opportunities on the Simply Wall St Screener.
- For investors who want strong fundamentals with room for a re rating, scan a curated 194 high quality undervalued stocks that share solid quality markers and trade below estimated worth.
- If capital preservation and resilience matter most to you, filter for 102 resilient stocks with low risk scores that score well on business stability and balance sheet strength.
- When income is the priority, focus on cash generating companies offering 163 dividend fortresses that may suit a more yield oriented portfolio.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com