


Leadership change puts Albemarle in focus
Albemarle (ALB) has scheduled a future leadership shift, naming Ragnar "Rag" Udd as CEO effective February 1, 2027. Current leader Kent Masters will transition to the role of Executive Chairman.
Albemarle shares have been under pressure in recent months, with the 30-day share price return down 15.5% and the 90-day move lower by 30.8%, even though the 1-year total shareholder return is up 43.6%. The CEO succession news lands after this weaker short term momentum and suggests investors are reassessing the balance between Albemarle's long term energy storage opportunity and nearer term risks being reflected in the current US$115.03 share price.
Assess how Albemarle's leadership change fits into the broader energy storage story by scanning a curated set of 27 best rare earth metal stocks.After a 30.8% slide over three months and a 43.6% gain over the past year, Albemarle now sits in a sharply reset spot. Does that skew the risk reward toward buyers at US$115.03, or not?
Most Popular Narrative: 39% Undervalued
Albemarle’s most followed narrative pegs fair value at $187.16, well above the recent $115.03 close. This puts real weight on how management steers the next phase of the energy storage cycle.
Albemarle's disciplined capital spending (60% CapEx reduction YoY and ongoing prioritization of highest-return projects) and improved cash conversion is enabling it to generate positive free cash flow, strengthen its balance sheet, and provide greater financial flexibility for future growth, which can bolster earnings as demand recovers and pricing normalizes.
See why 187 investors see Albemarle as 39% undervalued.
Result: Fair Value of $187.16 (UNDERVALUED)
Still, the bullish Albemarle story can break if lithium oversupply keeps pricing weak for longer than expected, or if regulatory and geopolitical setbacks raise costs and delay projects.
Find out about the key risks to this Albemarle narrative.
Another view on Albemarle’s valuation
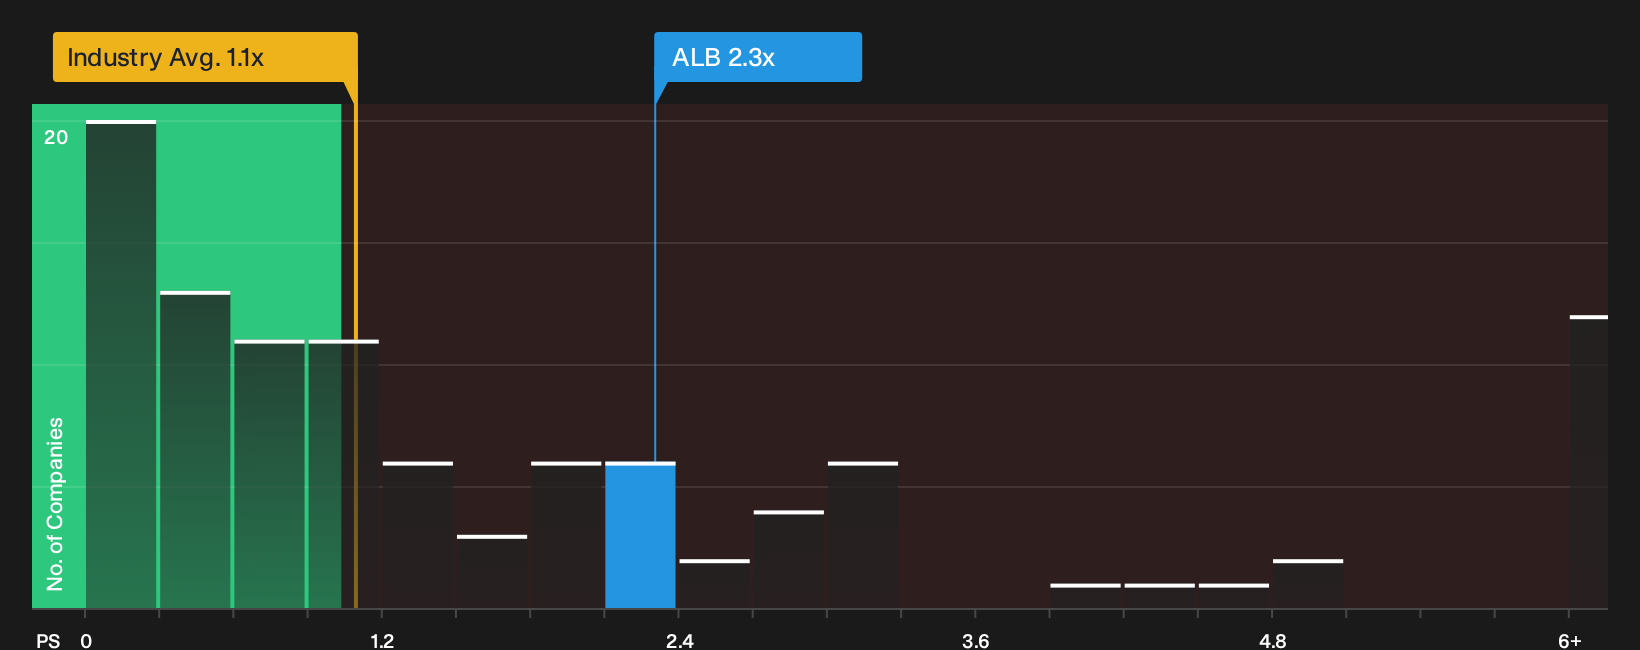
On one side, Albemarle looks cheap versus an internal fair value estimate, with the shares trading at a 55.9% discount to that number and also below an estimated future cash flow value of $260.90. On the other, the current market is asking investors to pay 2.3x P/S, which is roughly double the US Chemicals industry at 1.1x and slightly above the peer average of 2.2x. The fair ratio sits at 1.8x, which is lower than where Albemarle trades today and suggests the multiple could move down, not up, if sentiment cools rather than improves.
That split picture raises a simple question for anyone watching ALB: Which signal carries more weight for you, discounted cash flow or a sales multiple that already prices in a lot of good news for a business with forecast revenue growth of 4.9% per year?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Albemarle's value and leadership can feel messy, so consider acting promptly and weigh the upside against the concerns by reviewing the 3 key rewards and 2 important warning signs.
Looking for more Albemarle-sized investment ideas?
If Albemarle has your attention, do not stop here. Use the broader market as your hunting ground and let data driven filters surface opportunities you might otherwise miss.
- Target resilient income by reviewing 6 dividend fortresses that aim to balance yield with staying power across different market conditions.
- Hunt for potential mispriced opportunities through the 15 high quality undiscovered gems that pair solid fundamentals with relatively low investor attention.
- Prioritize sleep at night stocks with the 11 resilient stocks with low risk scores that focus on companies scoring well on financial strength and downside protection.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com