


American Healthcare REIT (AHR) has spent more than US$2.0b year to date on senior housing acquisitions, concentrating on Class A communities in affluent, supply constrained markets that reshape the REIT’s real estate footprint.
American Healthcare REIT’s recent senior housing deals arrive while the share price sits at US$53.09, with a 90 day share price return of 14.12% and a 1 year total shareholder return of 28.25%. This suggests momentum has been building as acquisitions, leadership appointments and upcoming conference visibility reshape how investors view its growth profile and risk balance.
See how American Healthcare REIT’s senior housing strategy compares with other income-focused real estate opportunities by reviewing our curated list of solid balance sheet and fundamentals (23 results)
American Healthcare REIT now trades about 21% below the average analyst price target and carries an implied intrinsic discount of roughly 53%. Is that an opportunity, or is the market cautious after such rapid portfolio expansion?
Most Popular Narrative: 18% Undervalued
On the latest narrative workup, American Healthcare REIT screens as undervalued, with a fair value of $64.40 against the recent $53.09 close and a relatively low discount rate assumption of about 7.3% anchoring that view.
The combination of a rapidly growing 80+ demographic and a multi-year period of low new supply in senior housing and skilled nursing is expected to drive a persistent supply-demand imbalance, fueling both occupancy gains and rent growth across American Healthcare REIT's portfolio. This dynamic should underpin above-trend revenue and net operating income growth over the next decade.
See why 7 investors see American Healthcare REIT as 18% undervalued.
Result: Fair Value of $64.40 (UNDERVALUED)
Still, the American Healthcare REIT story can change quickly if occupancy in senior housing settles near current levels or if reimbursement pressure squeezes margins and cash flow.
Find out about the key risks to this American Healthcare REIT narrative.
Another View On American Healthcare REIT’s Valuation
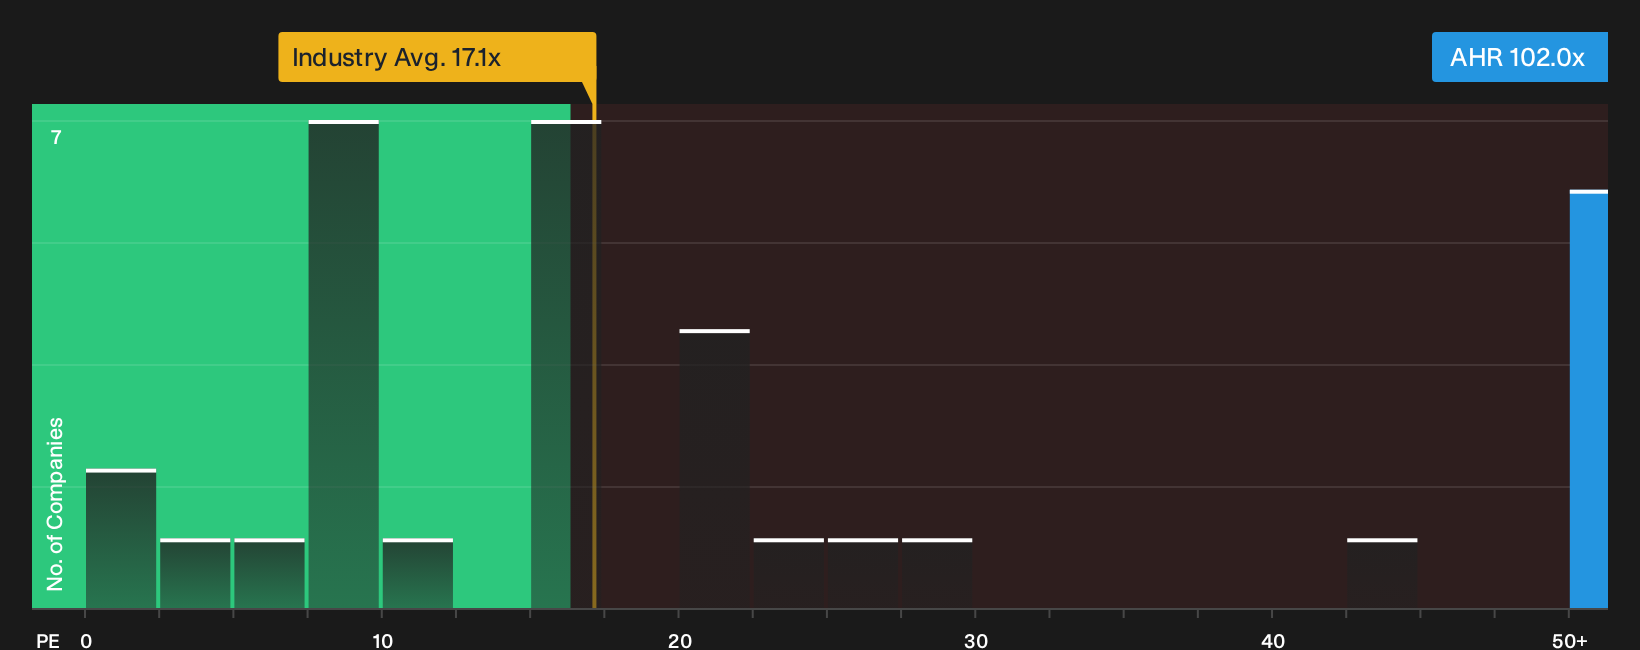
The first lens paints American Healthcare REIT as undervalued on fair value estimates, yet the headline P/E ratio tells a very different story. At about 102x earnings, the stock trades well above its fair ratio of 47.7x, the US peer average of 45.1x, and the global Health Care REITs group at 17.1x. That kind of premium can either signal a rich opportunity if growth plays out or leave investors exposed if expectations cool. The key question is which story investors choose to focus on more.
For a closer look at how that P/E premium lines up with cash flow, balance sheet strength, and earnings quality, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals like these around American Healthcare REIT rarely stay unresolved for long, so review the numbers yourself and move quickly to form your own view. To weigh both sides of the story in one place, start with the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond American Healthcare REIT?
If American Healthcare REIT has your attention, do not stop your research here. Broader context across other opportunities can sharpen your judgment and highlight better fits.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (23 results) for companies that may better match your risk comfort.
- Hunt for quality businesses priced below their assessed worth through the 35 high quality undervalued stocks and see which ones deserve a closer look next.
- Build a stream of potential portfolio income by reviewing the 6 dividend fortresses and weighing which yields align with your long term plan.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com