


- Tidewater, a global offshore service vessel operator, has recently been highlighted for strong revenue growth, rising market share, and solid free cash flow margins that expand its options for allocating capital.
- The focus on free cash flow strength is important because it gives Tidewater more room to refresh its fleet, pursue acquisitions, or reduce debt when conditions suit.
- We will now explore how Tidewater's investment narrative could be shaped by its strong free cash flow profile and capital deployment flexibility.
Scan other cash generative small caps with Tidewater for similar capital flexibility by reviewing our curated list of 16 high quality undiscovered gems.
Tidewater Investment Narrative Recap
Tidewater appeals to shareholders who think tight offshore vessel supply and a solid multi year project pipeline can support healthy utilization and pricing. The big short term swing factor is how quickly offshore customers move ahead with committed projects, especially in regions like Africa where pauses can leave vessels idle and chip away at margins.
The largest operational risk right now is that offshore demand stays softer for longer in key markets, while Tidewater keeps leaning on acquisitions to grow its fleet. Execution on any future deals, integration quality, and the timing of customer activity will likely matter more than this latest update. The recent news does not appear to change that equation in a material way.
With no new major announcements directly tied to this news, the most relevant context remains Tidewater's free cash flow strength and balance sheet flexibility. Management has room to refresh vessels, pursue deals, or trim debt without being boxed in by near term swings in day rates or utilization.
For you as an investor, that financial flexibility sits alongside real execution risks around offshore cycles, customer payment reliability in regions like Mexico, and potential shifts in energy policy. The core question is whether Tidewater can keep turning its vessel footprint and capital structure into consistent earnings and cash generation through those ups and downs.
Tidewater's current analyst narrative points to forecast revenue of US$1.9b and earnings of US$416.5 million by 2029. That outlook assumes revenue growth of 12.6% per year and an earnings increase of about US$169.6 million from US$246.9 million today.
Uncover why Tidewater's fair value indicates a 3% potential upside to its current price, which could narrow quickly.
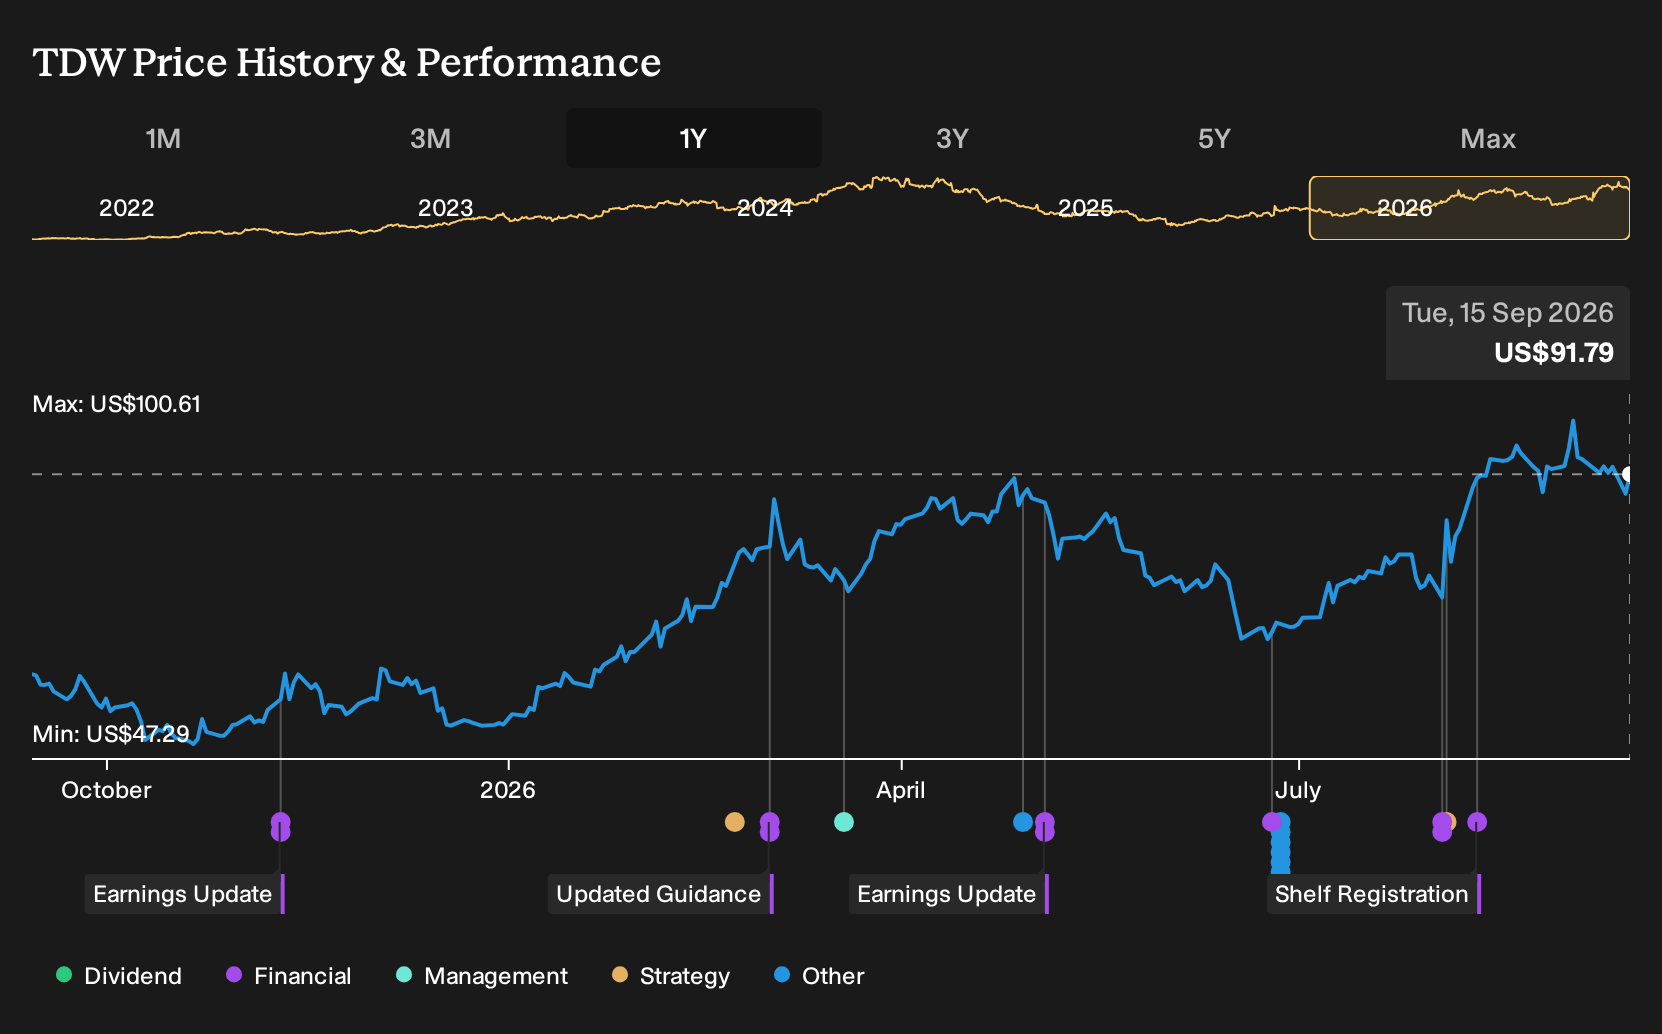
Exploring Other Perspectives
One alternate view on Tidewater leans hard into decarbonization risk. In that narrative, the lowest analysts only saw revenue reaching about US$1.7b and earnings of roughly US$282.4 million by 2029, far below consensus. Those estimates were set before this news, so you may see opinions shift as new information lands.
Explore 4 other Tidewater fair value estimates, including one that suggests as much as 26% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider doing your own independent analysis.
- A great starting point for your Tidewater research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Tidewater. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Tidewater's overall financial health at a glance.
Looking For More Ideas Beyond Tidewater?
Once you have a view on Tidewater, it can help to line it up against other opportunities that match your preferred balance of quality, income, and risk. The Simply Wall St Screener lets you do exactly that by filtering for traits that matter to you instead of relying on headlines.
- If you prize long term value and quality fundamentals, see how Tidewater compares with other opportunities on our 34 high quality undervalued stocks.
- If resilience and balance sheet strength are high on your checklist, weigh Tidewater against companies in our list of solid balance sheet and fundamentals (22 results).
- If downside protection matters most, stress test your Tidewater thesis by lining it up against the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com