


Ormat Technologies has given long term holders a solid ride over the past few years, even as the share price has pulled back sharply in recent weeks. With the stock now sitting near US$91 and recent headlines focused on earnings potential, the key question is whether that tag still lines up with what the business earns.
- Over the past 5 years, Ormat Technologies has delivered a total return of about 40.0%. This puts real weight on whether the current earnings profile can carry that track record forward.
- Recent commentary from analysts points to possible improvement in electricity margins and support from the energy storage segment. Both factors can influence how durable future earnings look against today’s valuation.
- Your read on Ormat Technologies is one view; the desks covering it have another. See what analysts think Ormat Technologies's shares could be worth.
The stock's next move may depend on whether Ormat Technologies' current earnings are strong enough to justify the price investors are paying today.
If you are weighing Ormat Technologies against other earnings driven utilities, it can help to see how similar themes play out across 38 power grid technology and infrastructure stocks
Is Ormat Technologies Getting Expensive on Earnings?
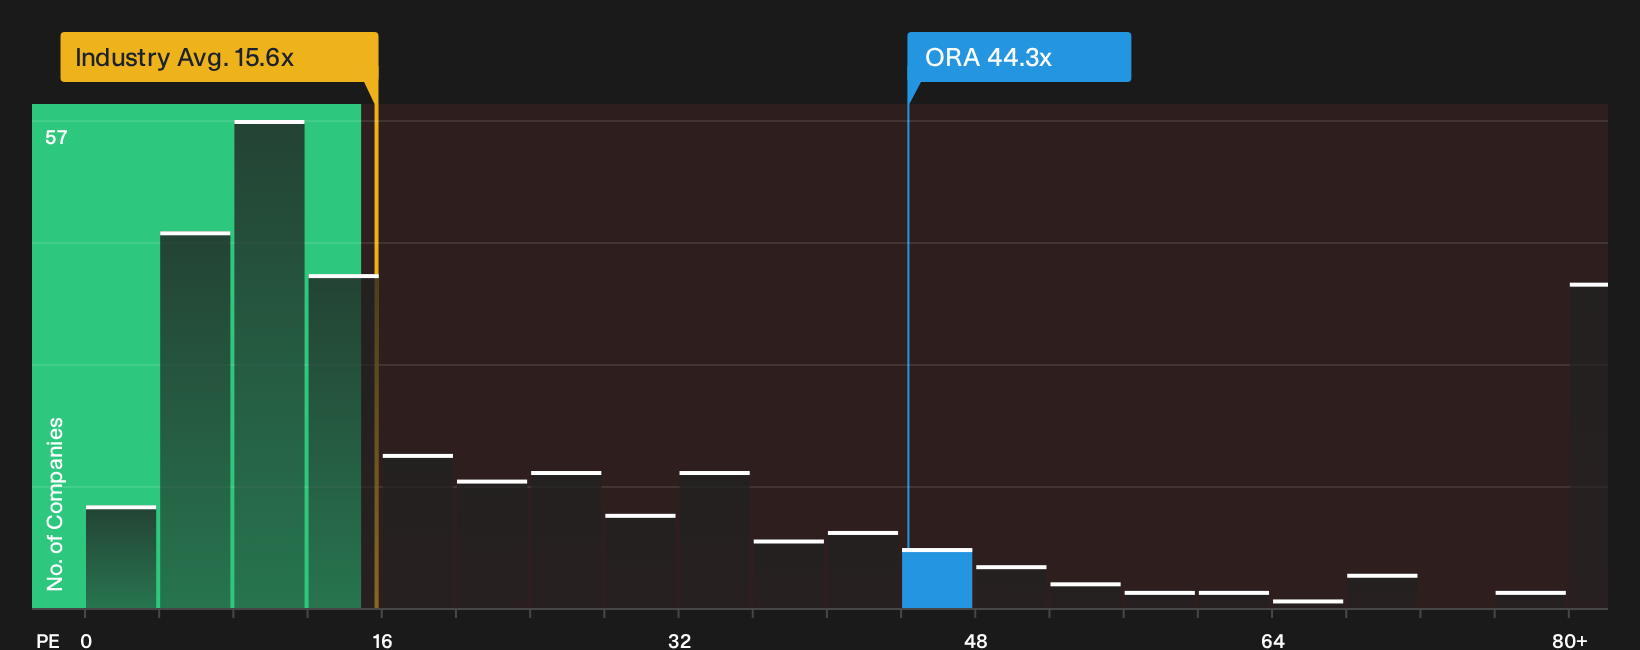
The P/E ratio suits Ormat Technologies because earnings remain the main focus for how investors frame its value today. At roughly 44.3x earnings, the stock trades well above the Renewable Energy sector average of about 15.6x and also above the peer group near 28.8x. That premium means buyers are paying a higher price for each dollar of profit than is typical across similar utilities.
The Fair Ratio, which reflects what might be expected given Ormat Technologies' size, growth profile, margins and risk, sits below the current P/E, so the shares screen as overvalued on this framework. Despite recent bullish commentary around earnings potential and margin targets through 2030, the current multiple already builds in a strong outlook compared with both the sector and peer benchmarks, so anyone looking at the stock today needs to decide whether that richer starting point feels justified. Explore the numbers behind Ormat Technologies's P/E valuation.
The Ormat Technologies Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Ormat Technologies pick up where the P/E puzzle leaves off and explain which potential paths for future growth, margins and earnings would need to occur for the stock to be worth materially more or less than today’s price. Rather than a single ratio or model output, they describe the future that number relies on so you can monitor over time whether Ormat Technologies' reality aligns with those assumptions on the Community page.
One of the top community narratives on Ormat Technologies: 33% undervalued
"Favorable policy changes and tax incentives accelerate project timelines, lower costs, and enhance revenue growth and profitability for geothermal and energy storage developments…"
Discover why this Narrative puts Ormat Technologies at 33% undervalued.
One more Ormat Technologies check before you log off
Price ratios tell you what investors pay today, while analyst projections sketch where they think Ormat Technologies could be a few years from now. This gives you a different benchmark to compare with the current tag. Explore where analysts expect Ormat Technologies to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com