


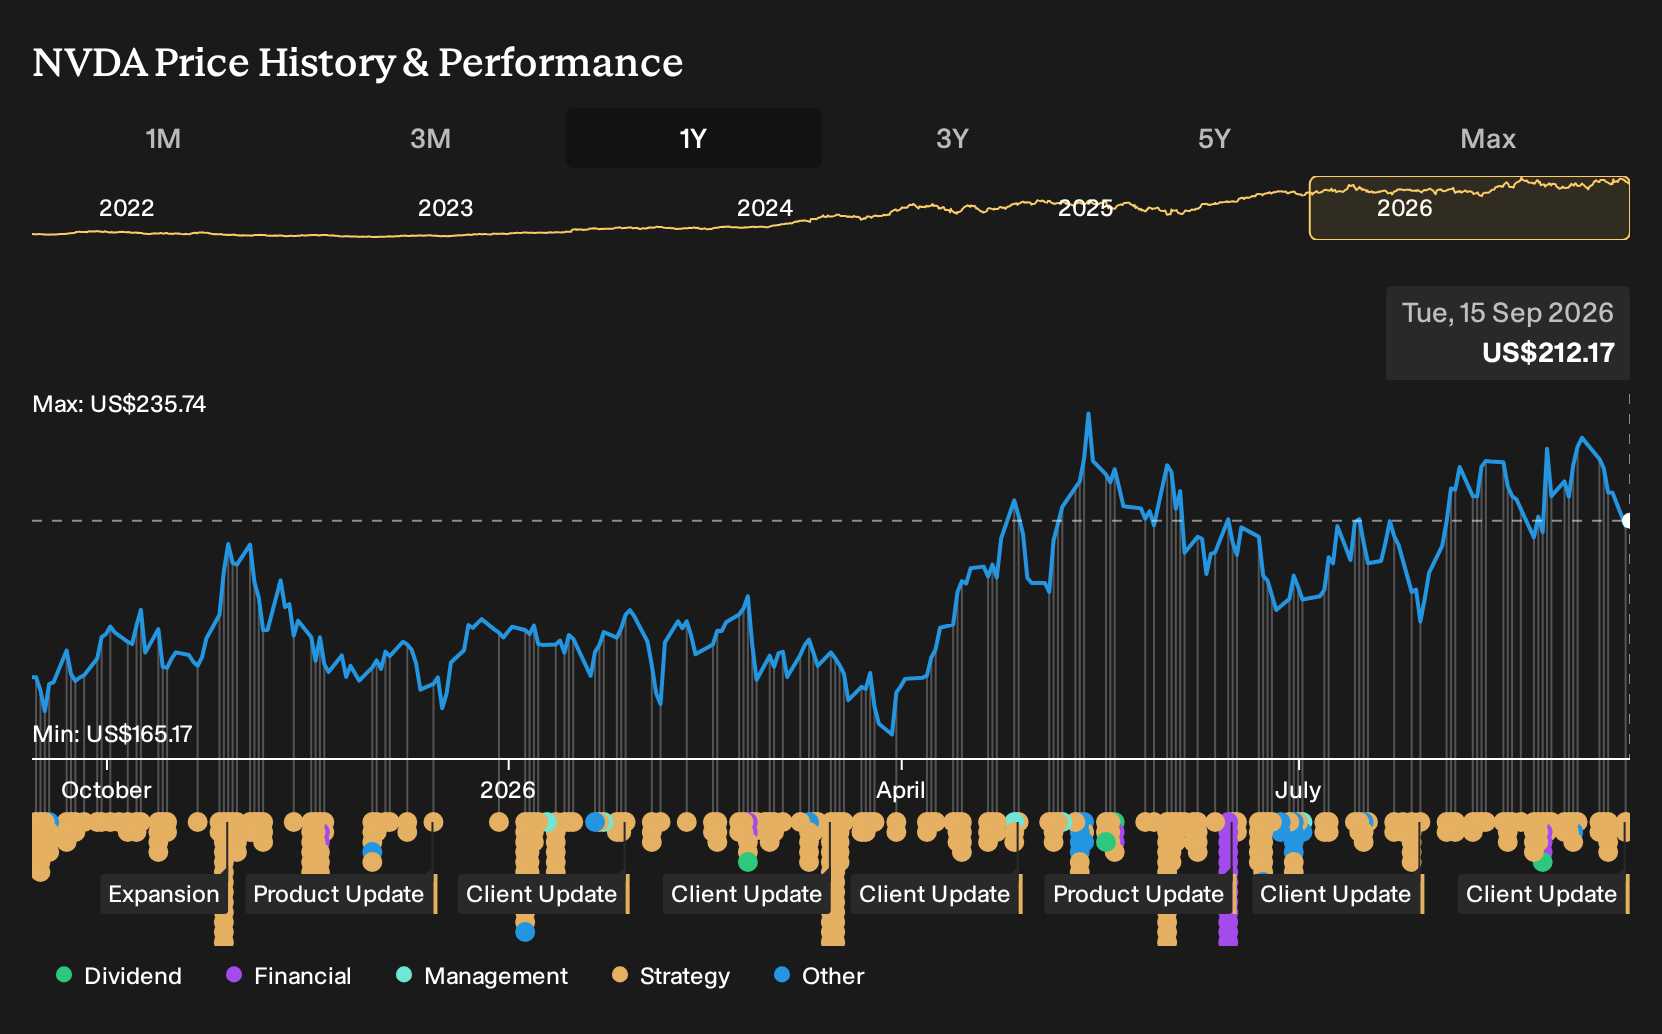
- Over recent days, high profile AI leaders including Anthropic’s Dario Amodei have urged a slower pace for frontier AI models, raising questions about how any future guardrails might affect Nvidia’s core AI data center business and long pipeline of infrastructure projects.
- Despite the headlines, Nvidia and major customers report no evidence of cancelled chip orders or paused buildouts, which points to sentiment driven volatility rather than a clear shift in the firm’s underlying demand or multi year AI infrastructure commitments.
- We will now look at how Nvidia's investment narrative holds up as AI safety calls intersect with continued aggressive infrastructure spending.
Scan beyond NVIDIA and see how other chipmakers and AI infrastructure players are positioned right now with our curated list of 60 AI infrastructure stocks.
NVIDIA Investment Narrative Recap
NVIDIA is essentially a bet on AI compute staying scarce and valuable, with the business using its full stack, from GPUs to software, to supply that capacity. For a shareholder, the near term hinge point is whether hyperscalers and sovereign buyers keep building AI factories at the current clip. The recent AI slowdown debate has hit sentiment, but customer commitments and project pipelines described so far do not point to a clear demand break.
The biggest operational risk right now is not demand. It is constraints, from chip supply and memory availability to power and regulatory scrutiny of large data centers. Any sustained hit to China access, or a faster shift by big customers to in house silicon, would start to bite that multiyear AI infrastructure story. Based on disclosed information, the latest headlines have not yet changed those structural risks in a material way.
Among the recent announcements, the launch of the AI Energy Management Alliance looks closest to the current debate over pacing frontier models and data center buildouts. NVIDIA, Google and Emerald AI are trying to make AI data centers more grid friendly, with facilities that can dial power use up or down when the electricity system is under stress. That directly targets one of the practical bottlenecks in scaling AI, which is access to reliable, affordable power.
For you as an investor, AEMA speaks to NVIDIA’s attempt to keep AI capex flowing even as regulators and utilities ask harder questions about power usage and emissions. If the alliance can move industry standards on flexible demand and interconnection, it could support NVIDIA’s pipeline of AI factories. If it stalls, energy constraints and permitting friction remain a key headwind to the very infrastructure spending that underpins the NVIDIA story right now.
NVIDIA's narrative projects US$714.0b revenue and US$392.6b earnings by 2029, based on analysts assuming 41.2% yearly revenue growth and earnings rising by about US$233.0b from US$159.6b today.
Discover why NVIDIA's fair value indicates a 43% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate take focuses on margin risk rather than AI demand. On this view, even deals like Jetson Orin Nano 2 in home robots or AEMA on data center power cannot offset pressure if customers push back on pricing. The most cautious analysts were working off US$688.2b revenue and US$366.8b earnings by 2029, with a much lower assumed P/E, before this week’s announcements. That perspective presents a far more conservative Nvidia story and serves as a reminder to weigh several narratives before deciding how this news fits your own view.
Explore 111 other NVIDIA fair value estimates, including one that suggests it could be worth just $205.19.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your NVIDIA research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for NVIDIA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NVIDIA's overall financial health at a glance.
Looking For More Ideas Beyond NVIDIA?
If this NVIDIA story has you thinking bigger about your portfolio, it can help to line it up against a wider bench of potential opportunities. The Simply Wall St Screener lets you filter for the kind of businesses that match your risk appetite and income goals, rather than forcing everything through a single AI theme.
- If you want potential upside without paying any price, consider companies that combine quality with a valuation gap through our 34 high quality undervalued stocks.
- If capital preservation and resilience matter most to you, focus on businesses with sturdier finances by scanning the 11 resilient stocks with low risk scores.
- If you are hunting for under the radar stories with solid fundamentals, cast a wider net using the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com