The Zhitong Finance App learned that CICC released a research report saying that in September, the FOMC Federal Reserve announced an interest rate hike of 25 bps, raising the benchmark interest rate to 3.75%-4.00%, which is in line with market expectations. This is the first time since December 2025 that the Federal Reserve has adjusted the target interest rate for federal funds, and the first time since July 2023. Previously, the Federal Reserve cut interest rates 6 times from September 2024 to December 2025, with a cumulative total of 175 bps of interest rate cuts. In terms of allocation, it is recommended to focus on: 1) technology growth stocks; 2) comprehensively consider the geographical situation and production capacity cycle position, and focus on areas where performance is improving and the supply and demand pattern is improving. The fundamental recovery in the pure domestic demand industry is still progressing relatively slowly and requires further observation.
CICC's main views are as follows:
How will the Federal Reserve's rate hike affect A-shares? This interest rate hike may not be equivalent to the beginning of the US interest rate hike cycle; the two have different meanings for A-shares
From the perspective of the general influence mechanism, if the Federal Reserve continues to raise interest rates, it may affect A-shares through three channels: 1) On the financial side, the Fed's interest rate hike may lead to a tightening of global liquidity. Interest rate hikes will lead to an increase in overseas financing costs. Under normal circumstances, the US dollar tends to strengthen, leading to marginal changes in exchange rates and capital flows, and affecting A-share capital expectations. 2) Fundamentally, the Fed's interest rate hike may have an impact on exports. In particular, at a stage where interest rates in the US may not be low, interest rate hikes may suppress demand for traditional overseas industries, thereby suppressing the export demand of some Chinese companies that are suppliers. 3) On the policy side, under normal circumstances, the Fed's interest rate hike may have an impact on China's monetary policy expectations from external conditions.
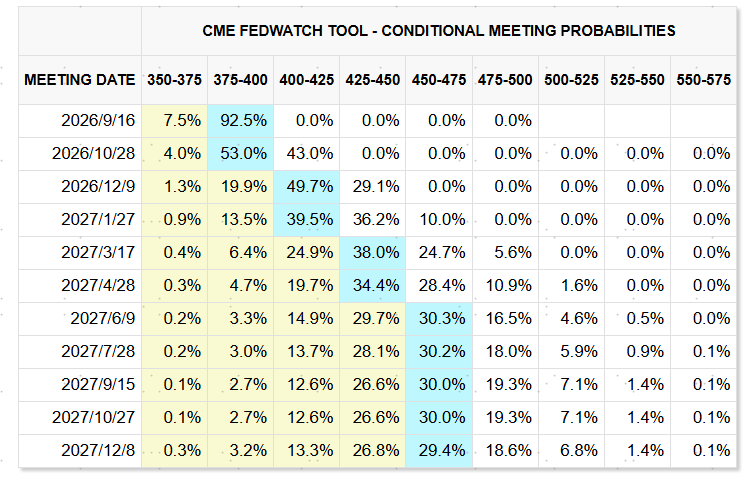
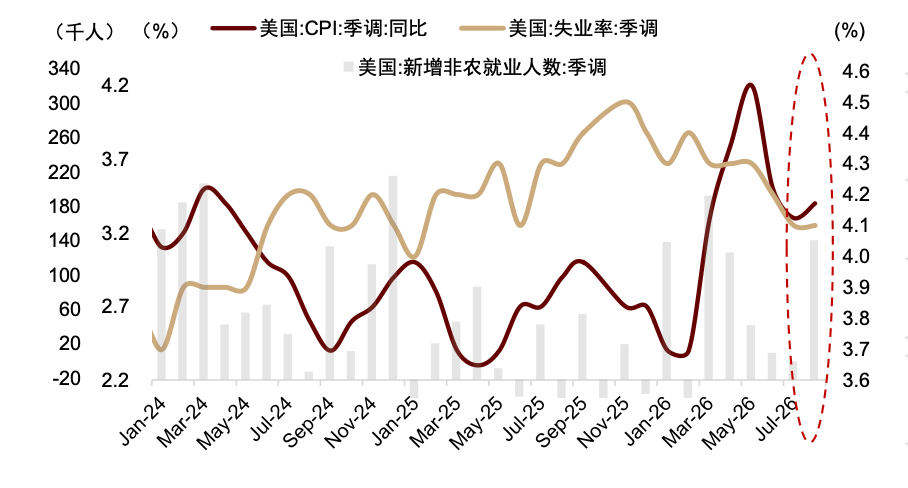
However, the current US interest rate hike may be different from the beginning of a normal US interest rate hike cycle. It remains to be seen whether it will have a lasting impact on A-shares. If it is only a short-term or even a single rate hike, the impact will be relatively limited, and A-shares have recently had a full response. Combined with the recovery in US inflation in the past two months and the strong performance of non-agricultural data (Chart 1), the market has largely included the current US interest rate hike in expectations. According to CME FedWatch, before the current US interest rate hike, the market expected the probability of this rate hike to exceed 90% (Chart 2). The performance of the A-share market has been weak recently, and expectations of interest rate hikes from the US are one of the main external factors suppressing. However, it should be noted that there is still great uncertainty about whether the current US interest rate hike will continue and that the interest rate hike cycle will take a long time to form.
The rise in US inflation since this year has been greatly linked to the rise in oil prices due to the geographical conflict. In particular, the recent escalation of the geographical conflict between the US and Iran has once again escalated, and the scope of influence has spread, and the price of Brent crude oil has once again exceeded 100 US dollars/barrel. However, in the medium term, there is great uncertainty about the impact of geopolitical risks on oil prices, and the current US economic environment may not support a sustained and large increase in interest rates. Furthermore, according to an article previously published by CICC, the Federal Reserve is currently facing “triple restraints” (inflation targets and market restrictions, FOMC committee restrictions, politics and high debt constraints), and that the current monetary policy actions of the US may instead accelerate the restructuring of the international monetary order, further diversification and fragmentation of global asset allocations. In this context, if the US interest rate hike faces major constraints in the medium term and is difficult to sustain, the bank believes that the impact on A-shares may be relatively limited, and there has been a full response in the early stages.
How is the future market configured? Recent fluctuations in the A-share market are mainly affected by external factors, including the situation in the Middle East, expectations of interest rate hikes by the Federal Reserve, and rising US bond yields. However, the impact of these external disturbances on A-shares is mostly short-term and phased. The fundamentals of A-shares are relatively good this year, and the performance growth rate of listed companies is expected to be at the best level in the past five years; the overall valuation of the A-share market is quite attractive, and the structural overvaluation phenomenon faced in the first half of the year has improved to a large extent. The restructuring of the global monetary order and technological narratives in the medium term have not changed in support of A-shares. At the moment, the bank believes that there is no need to be pessimistic about the future market of the A-share market, and the long-term, steady trend since “9.24” is still expected to continue.
In terms of allocation, it is recommended to focus on: 1) Technological growth. The key to the performance of growth stocks is still the implementation of the industry's own prosperity and performance. With stable fundamentals, the US interest rate hike may not necessarily have a greater impact on global growth stocks. The A-share technology sector may show a trend of differentiation in the future, and careful selection is needed: AI infrastructure-related links, such as optical communication, PCB, etc., are still highly uncertain this year, and it is expected that there will be a rebound after the downturn in the early stages. More companies in the fields of semiconductors and computing power still need to pay attention to the degree of compatibility between fundamentals and valuations; more innovative drug companies have entered the clinical data verification stage, which is worth paying attention from the bottom up. 2) Comprehensively consider the geographical situation and production capacity cycle position, and focus on areas where performance is improving and the supply and demand pattern is improving, such as power grid equipment, petrochemicals, etc. The fundamental recovery in the pure domestic demand industry is still progressing relatively slowly and requires further observation.
Chart 1: US inflation has recently rebounded, and employment data is strong
Source: Wind, CICC Research Division
Chart 2: Before the current rate hike, the market expected the probability of an interest rate hike was over 90%