


Amidst recent geopolitical tensions and fluctuating oil prices impacting global markets, Asian stock indices have shown resilience, navigating through inflationary pressures and monetary policy shifts. In this environment, identifying undervalued stocks can be an effective strategy for investors seeking opportunities; these stocks are trading below their intrinsic value estimates, offering potential for growth as market conditions stabilize.
Top 10 Undervalued Stocks Based On Cash Flows In Asia
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Shizuki Electric (TSE:6994) | ¥1175.00 | ¥2305.87 | 49% |
| Rakus (TSE:3923) | ¥1061.00 | ¥2075.67 | 48.9% |
| P.S.P. Specialties (SET:PSP) | THB7.70 | THB14.85 | 48.1% |
| PAL GROUP Holdings (TSE:2726) | ¥1479.00 | ¥2874.94 | 48.6% |
| Ichikoh Industries (TSE:7244) | ¥555.00 | ¥1073.40 | 48.3% |
| Dongwon Industries (KOSE:A006040) | ₩36200.00 | ₩70708.77 | 48.8% |
| Cosmo Energy Holdings (TSE:5021) | ¥4638.00 | ¥9270.04 | 50% |
| Cheil Worldwide (KOSE:A030000) | ₩17550.00 | ₩33983.59 | 48.4% |
| BuySell TechnologiesLtd (TSE:7685) | ¥2850.00 | ¥5580.47 | 48.9% |
| AK Medical Holdings (SEHK:1789) | HK$4.855 | HK$9.60 | 49.4% |
Here's a peek at a few of the choices from the screener.
Amoy Diagnostics (SZSE:300685)
Overview: Amoy Diagnostics Co., Ltd. specializes in the research, development, production, sale, and support services of tumor precision medical diagnostic products both in China and internationally, with a market cap of CN¥6.49 billion.
Operations: Amoy Diagnostics generates revenue through its research, development, production, sales, and support services of precision medical diagnostic products for tumors across domestic and international markets.
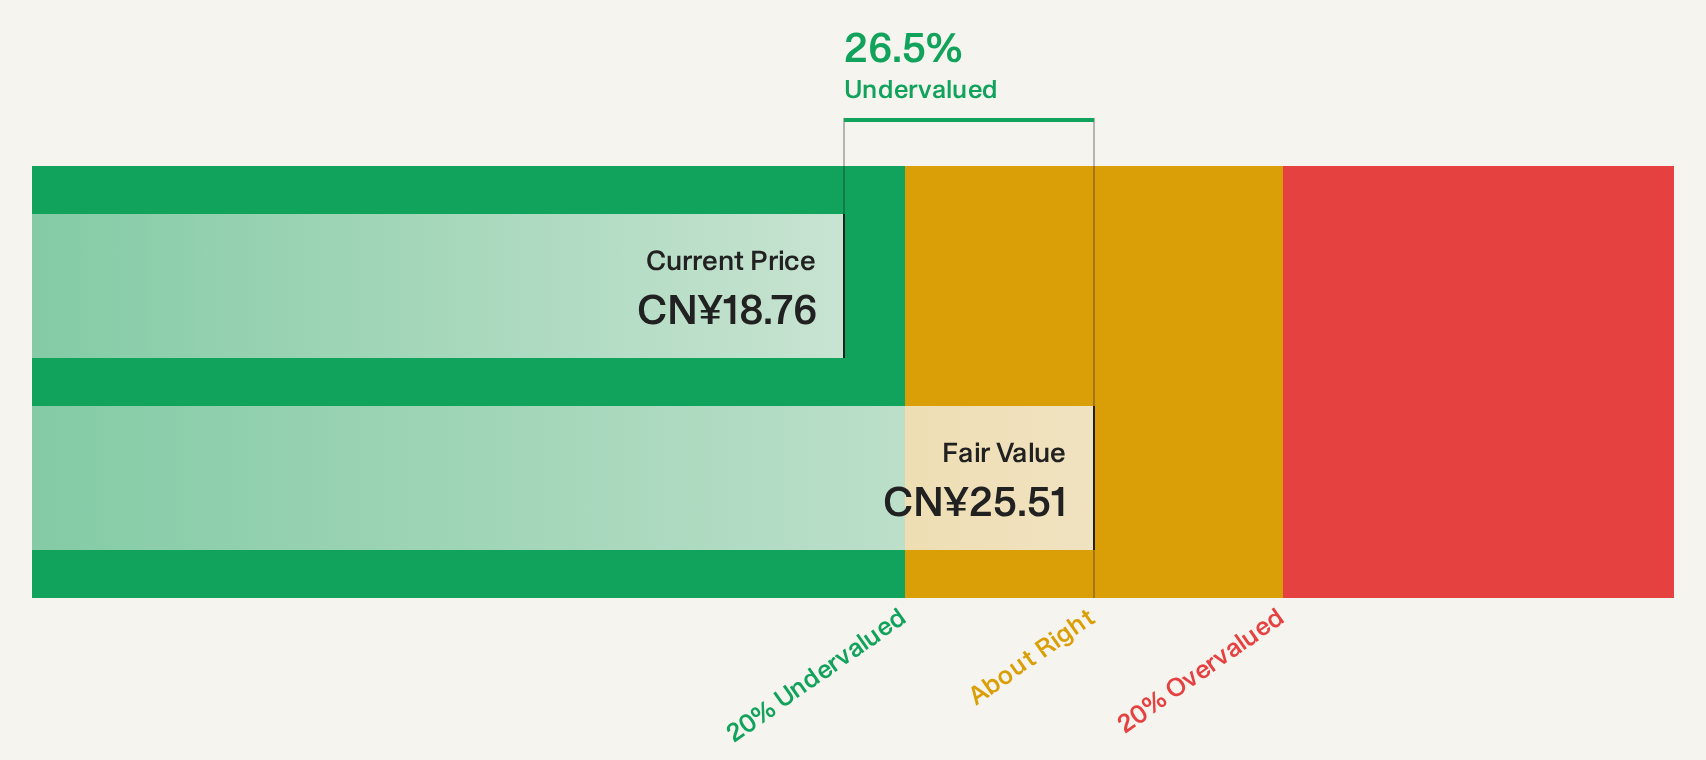
Estimated Discount To Fair Value: 33.5%
Amoy Diagnostics is trading at CN¥17.01, significantly below its estimated future cash flow value of CN¥25.59, indicating it is highly undervalued based on discounted cash flow analysis. Despite recent declines in revenue and net income for the half year ending June 2026, the company remains a good relative value compared to peers and industry averages. Analysts predict earnings growth of 16.71% annually, though this lags behind China's market expectations.
- Our growth report here indicates Amoy Diagnostics may be poised for an improving outlook.
- Navigate through the intricacies of Amoy Diagnostics with our comprehensive financial health report here.
Kitazato (TSE:368A)
Overview: Kitazato Corporation researches, develops, manufactures, and markets medical devices and reagents for fertility treatment with a market cap of ¥58 billion.
Operations: The company generates revenue primarily from its Medical Equipment Business, which accounts for ¥11.53 billion.
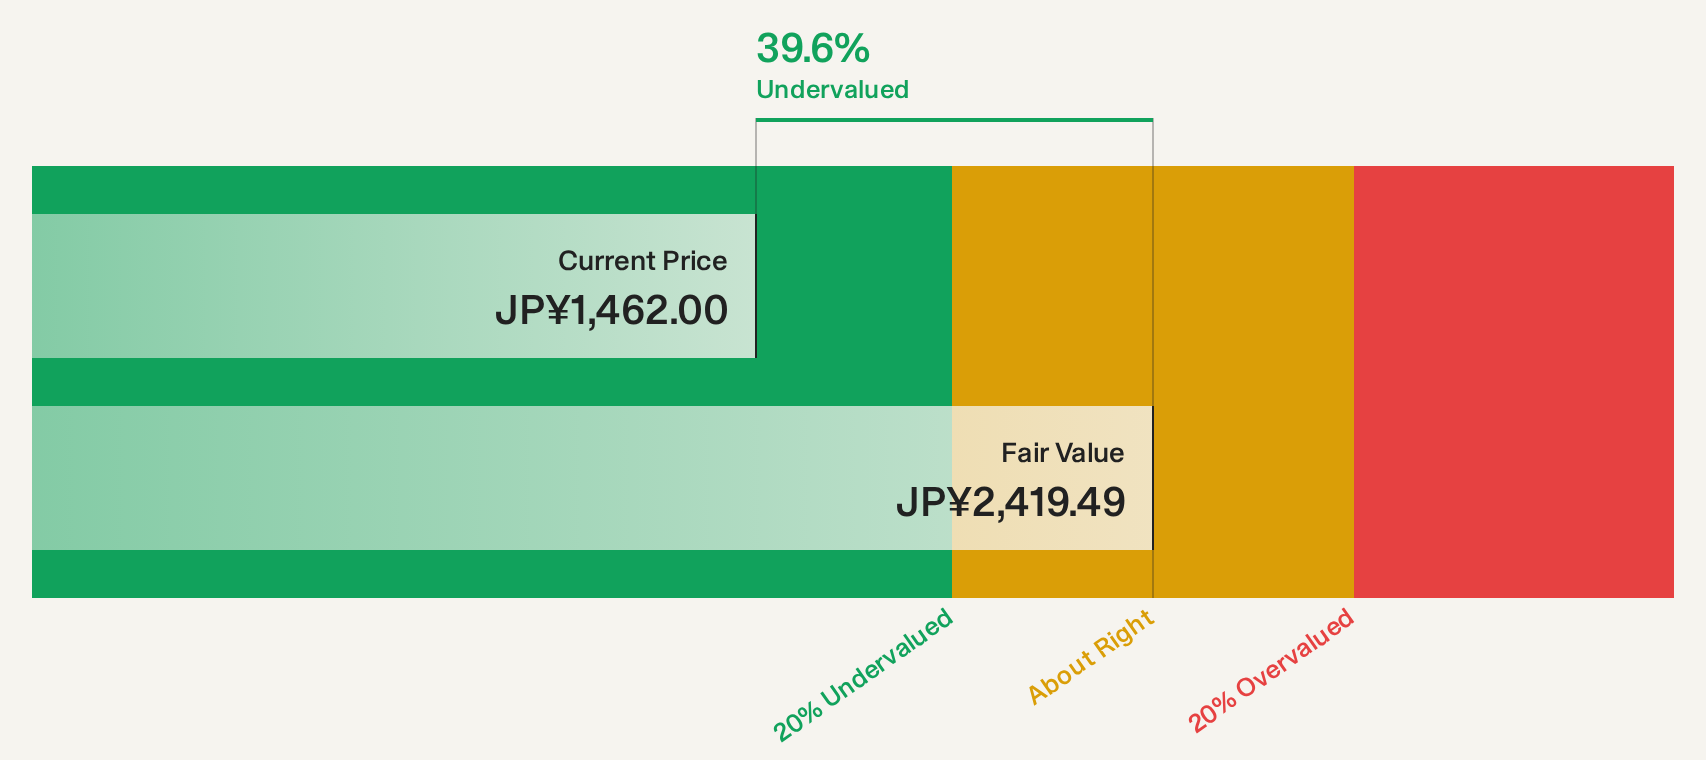
Estimated Discount To Fair Value: 40.3%
Kitazato, trading at ¥1,450, is significantly undervalued with a future cash flow value of ¥2,429.87. Despite slower projected earnings growth of 8% annually compared to the Japanese market's 8.8%, it offers good relative value within its industry and trades at 40.3% below its estimated fair value. Recent guidance forecasts net sales of ¥11.35 billion and operating profit of ¥6.12 billion for fiscal year ending March 2027, maintaining stable dividends per share at ¥41.
- The analysis detailed in our Kitazato growth report hints at robust future financial performance.
- Delve into the full analysis health report here for a deeper understanding of Kitazato.
Ichikoh Industries (TSE:7244)
Overview: Ichikoh Industries, Ltd. develops, manufactures, and sells lamps and other automotive parts for automobile manufacturers and parts suppliers both in Japan and internationally, with a market cap of ¥53.45 billion.
Operations: The company generates revenue primarily from its Automotive Parts segment, totaling ¥121.32 billion.
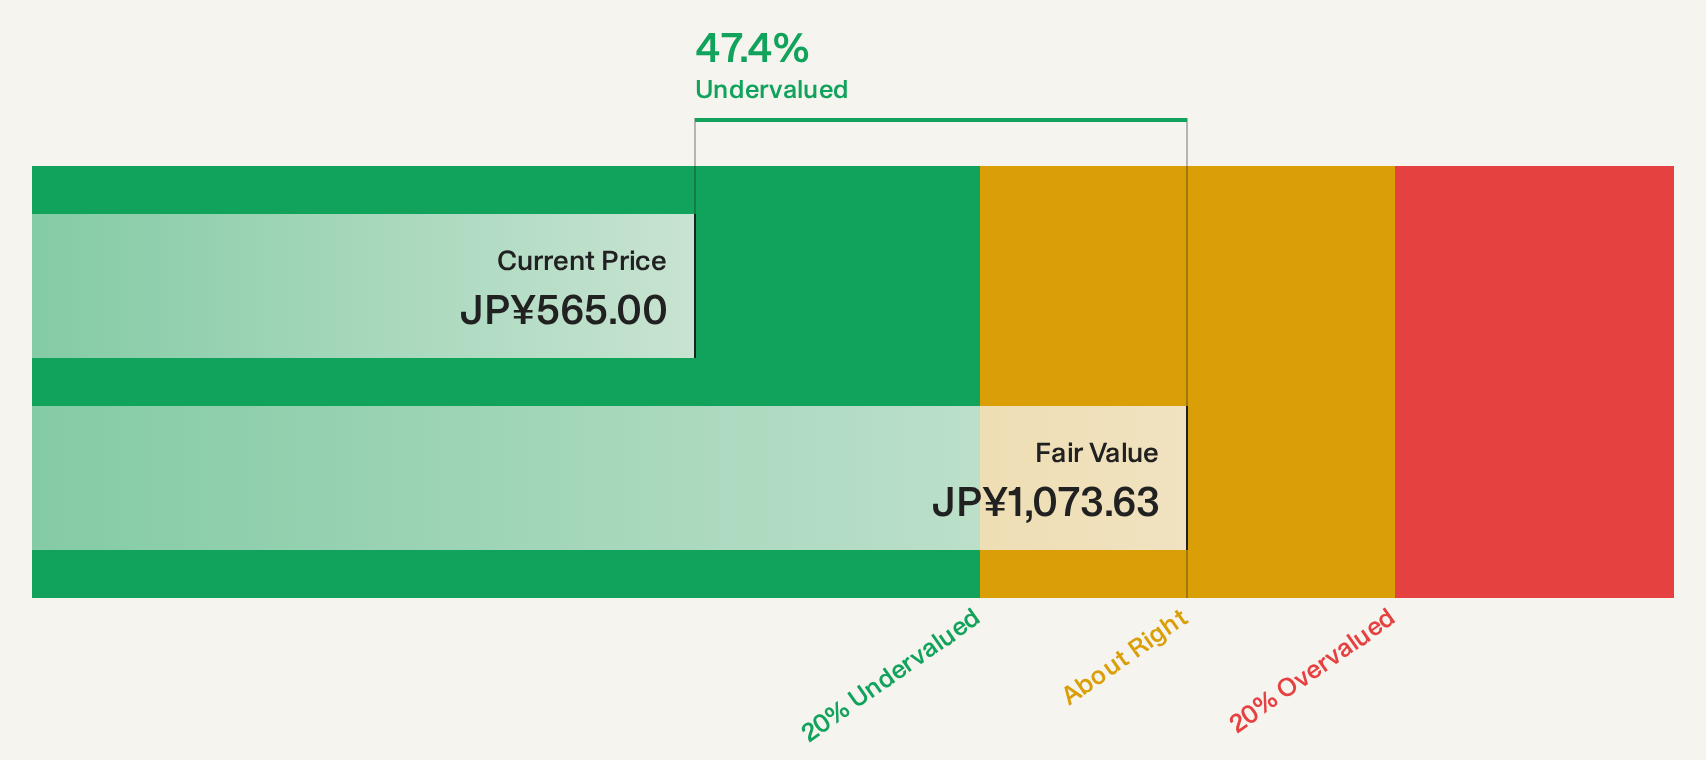
Estimated Discount To Fair Value: 48.3%
Ichikoh Industries is trading at ¥555, significantly below its estimated future cash flow value of ¥1,073.4, indicating substantial undervaluation. The company reported a strong increase in net income to ¥3.76 billion for the half year ended June 2026, up from ¥2.60 billion a year ago. However, earnings growth is forecasted at just 1.45% annually, slower than the Japanese market average of 8.8%. Despite an unstable dividend track record, recent dividends increased to ¥9 per share from retained earnings.
- Our comprehensive growth report raises the possibility that Ichikoh Industries is poised for substantial financial growth.
- Dive into the specifics of Ichikoh Industries here with our thorough financial health report.
Turning Ideas Into Actions
- Navigate through the entire inventory of 83 Undervalued Asian Stocks Based On Cash Flows here.
- Got skin in the game with these stocks? Elevate how you manage them by using Simply Wall St's portfolio, where intuitive tools await to help optimize your investment outcomes.
- Simply Wall St is a revolutionary app designed for long-term stock investors, it's free and covers every market in the world.
Curious About Other Options?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com