


Halozyme Therapeutics stock in focus after cluster of growth calls
Recent coverage flagging Halozyme Therapeutics (HALO) as a growth stock, backed by favorable analyst views, earnings estimate upgrades, and fresh partnership activity, has pulled the shares firmly onto investors’ radar.
Momentum around Halozyme Therapeutics has been building for a while, with a 90‑day share price return of 58.19% and a year to date share price gain of 54.23% at a last close of $108.44. A 3 year total shareholder return of 171.71% shows how the recent run sits on top of already strong longer term performance as investors respond to growth focused research coverage and a packed conference schedule.
Spot emerging momentum stories alongside Halozyme Therapeutics by scanning our hand picked list of 16 high quality undiscovered gems.Halozyme Therapeutics has already rewarded early believers, yet the latest surge and strong growth narrative leave a sharper question on the table. Is the meaningful upside still ahead, or has most of it already been priced in?
Most Popular Narrative: 25% Overvalued
On the most followed narrative, Halozyme Therapeutics screens as expensive, with a fair value of $86.89 against a last close of $108.44, which pulls the spotlight onto what needs to go right to justify that gap.
The company's expanding network of global partnerships and the ramp-up of recently launched subcutaneous biologics (e.g., OCREVUS ZUNOVO, Opdivo Qvantig, Tecentriq Hybreza, RYBREVANT SC) provide a robust set of new and diversified royalty streams that are still early in their adoption curve. As these launches mature and penetration increases, especially in emerging and international markets, significant sequential revenue and EBITDA growth is anticipated.
See why 64 investors see Halozyme Therapeutics as 25% overvalued.
Result: Fair Value of $86.89 (OVERVALUED)
Still, the Halozyme Therapeutics story can be knocked off course if patent challenges weaken ENHANZE protections or if a major partner reduces reliance on its platform.
Find out about the key risks to this Halozyme Therapeutics narrative.
Another View on Halozyme Therapeutics valuation
A different lens tells a very different story. Our DCF model points to a future cash flow value of $400.63 per share for Halozyme Therapeutics, compared with the current price of $108.44, which screens as significantly undervalued. If the market is this far off, what is it missing?
Look into how the SWS DCF model arrives at its fair value.
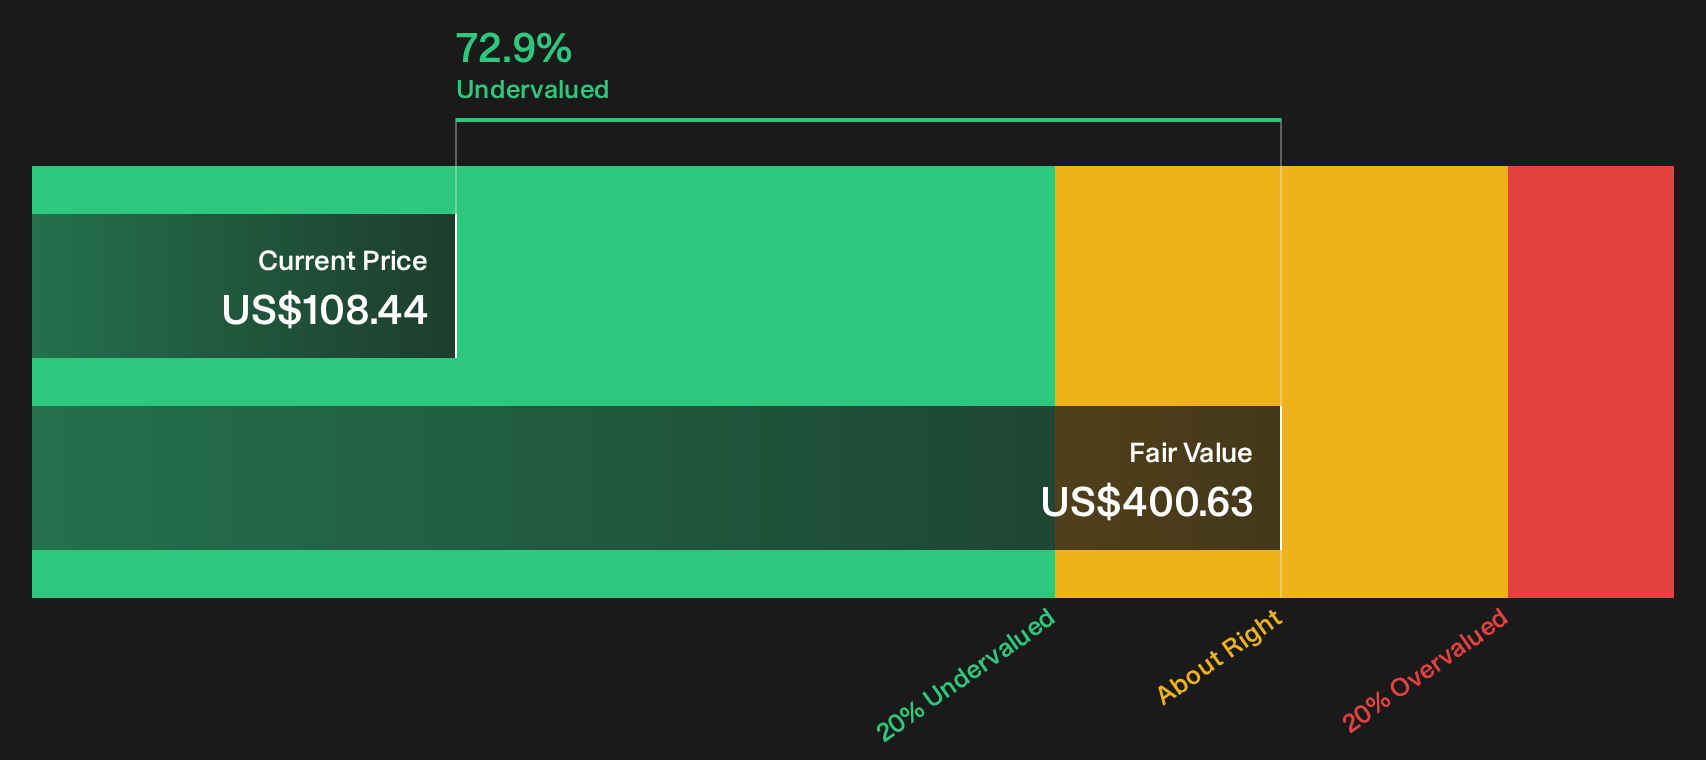
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Halozyme Therapeutics for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Halozyme Therapeutics valuation make this a stock you need to judge on your own terms. Move quickly, review the underlying data, and weigh both the upside drivers and the pressure points using our breakdown of 2 key rewards and 3 important warning signs.
Ready for more investment ideas beyond Halozyme Therapeutics?
If Halozyme Therapeutics has you thinking about what else might be compelling right now, use the Simply Wall St Screener to uncover other focused opportunities you could be missing.
- Target potential mispricings by scanning the market for 33 high quality undervalued stocks that pair solid fundamentals with prices that may not fully reflect their underlying business strength.
- Strengthen portfolio resilience by filtering for 11 resilient stocks with low risk scores that aim to keep volatility and red flags in check while still offering meaningful exposure.
- Hunt for overlooked opportunities by surfacing a curated mix of 16 high quality undiscovered gems that have strong underlying metrics but limited attention so far.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com