


Oil is back on centre stage as Chinese futures touch $129 a barrel, Brent spikes to $146 and supply routes face fresh security risks. Price shocks like this can punish some holdings yet open the door for others that are better positioned or more resilient. This article examines what that backdrop might mean for integrated producers and highlights 3 stocks from our Global Integrated Oil & Gas Producers screener that are currently tied into these headlines.
The three integrated giants below are just a sample, and the full screen surfaced 28 more large-cap producers with equally detailed stories that are not covered here. To identify which energy groups best fit your risk, income, and valuation preferences, head straight into the Global Integrated Oil & Gas Producers screener.
Naftna Industrija Srbije a.d (BELEX:NIIS)
Naftna Industrija Srbije a.d is a fully integrated Serbian oil and gas group that explores and produces hydrocarbons, refines crude, trades fuels and power, and runs a regional petrol station network across the Balkans. The business has a market cap of about RSD117.1b.
Naftna Industrija Srbije a.d fits this integrated producer screen because it is involved in crude production, product refining and fuel marketing at the same time that futures and spot prices are surging. Earnings are growing again, the dividend yield is high, and the key focus now is what happens when one pressure point on its cash generation meets this pricing backdrop.
That cash squeeze meeting surging prices is exactly what the 1 key reward and 3 important warning signs (1 is major!) to show where Naftna Industrija Srbije a.d might be mispriced or overlooked.

China Petroleum & Chemical (SEHK:386)
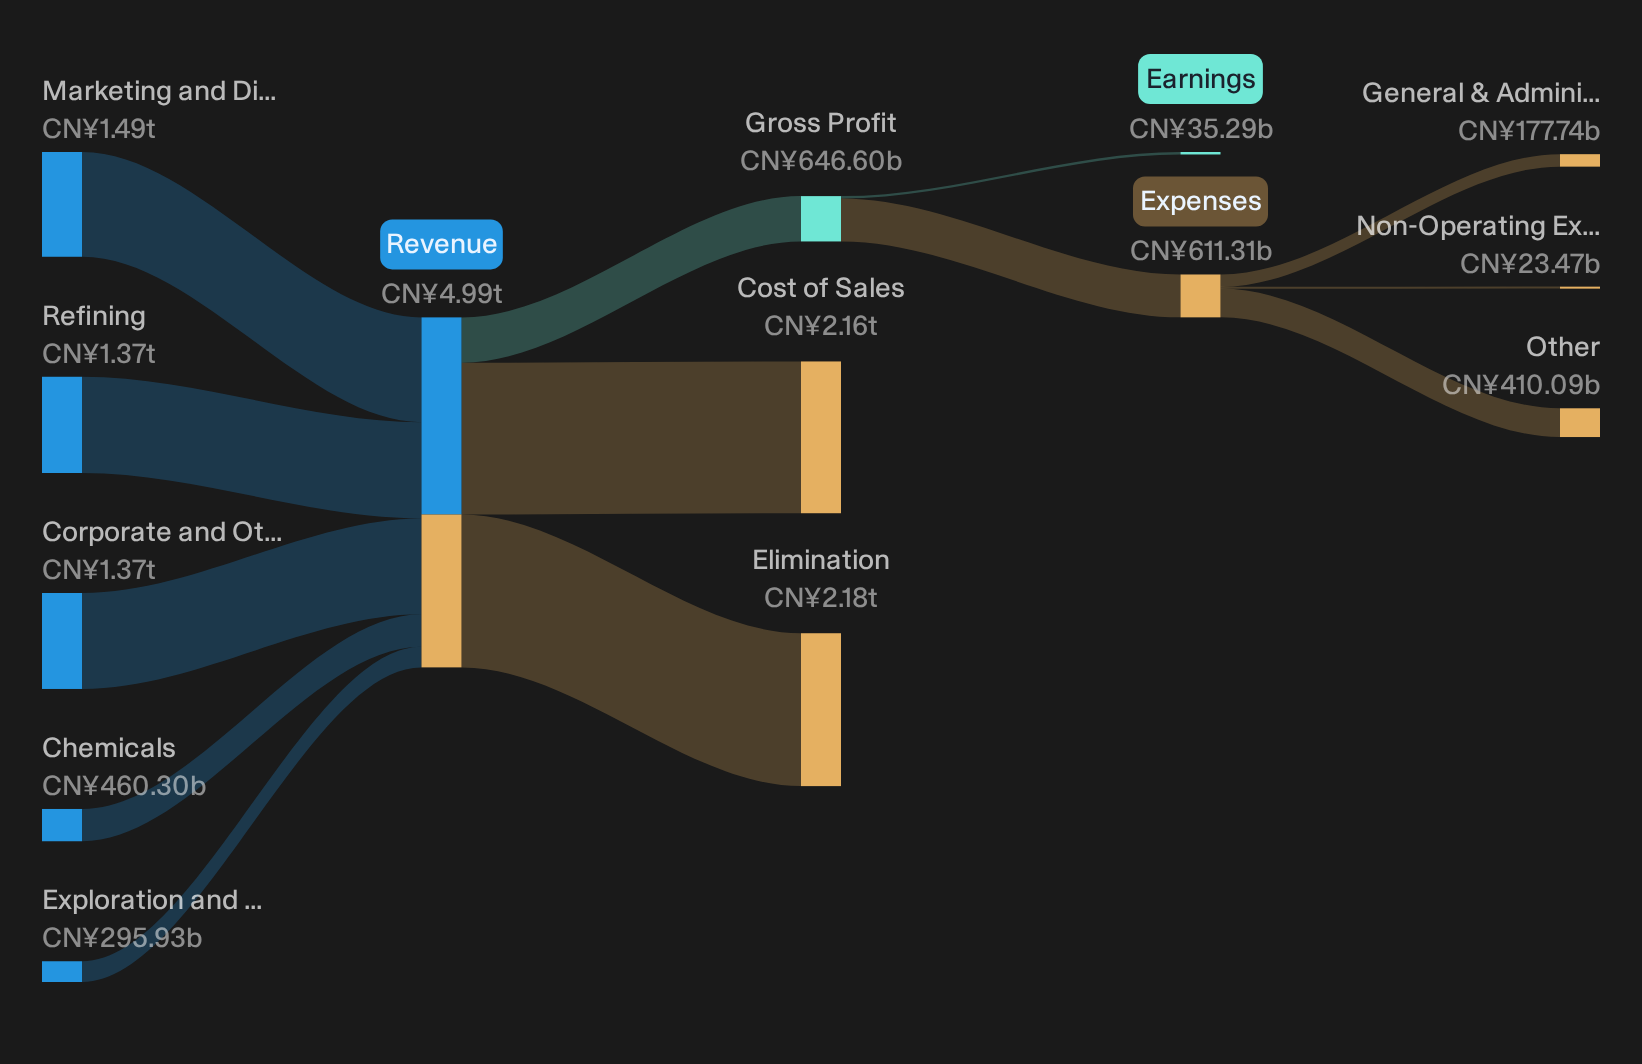
China Petroleum & Chemical is a large integrated energy and chemical group in this global oil and gas producer screen, running exploration, refining, marketing and petrochemicals at scale across Mainland China. Refining brings in about CN¥1.37t, marketing CN¥1.49t and chemicals CN¥460.3b, with corporate and other activities at CN¥1.37t. The stock has a market value of about HK$699.8b.
For an investor scanning this integrated oil and gas list, China Petroleum & Chemical offers large-scale exposure to crude and refined product pricing, backed by forecast earnings growth of 12.35% a year and a 5.08% dividend yield. However, the overall picture still depends on how thin profit margins interact with relatively high payout ambitions.
That tightrope between slim profitability and generous dividends is exactly what the 2 key rewards and 1 important warning sign to show where China Petroleum & Chemical might be misread by the market.
OMV Petrom (BVB:SNP)
OMV Petrom is part of the Global Integrated Oil & Gas Producers theme with meaningful upstream production alongside refining, fuel marketing and power generation. It earns most of its RON52.3b revenue from Refining and Marketing (about RON27.7b) and holds a market value near RON73.8b.
For investors focused on large integrated producers linked to global crude prices, OMV Petrom provides a mix of upstream exposure and regional energy security projects that could matter if today’s supply shocks persist. This context sets up the core narrative around its next phase of development.
Progress at the Neptun Deep Black Sea gas project remains on track and, once operational, is expected to significantly affect OMV Petrom's regional production and earnings. The project is positioned to benefit from both Eastern European gas demand and regional energy security priorities, which together could influence revenues and margins.
The key variable is how any future shift in regional gas pricing feeds through to cash generation and dividend capacity.
That cash question is where OMV Petrom gets interesting. The full narrative for OMV Petrom lays out how Neptun Deep could reshape capital returns, risk, and regional influence.

Seeking Alternatives Before The Crowd?
Fresh opportunities do not wait. Breakout trends can build momentum quickly, and slow movers may end up chasing stocks that are already soaring. Review these curated ideas while they are timely and consider your next steps.
- Identify cash-rich operators with sturdy balance sheets before they potentially re rate by running the list of solid balance sheet and fundamentals (194 results) for financially resilient candidates that may still be under the radar.
- Explore the next phase of the AI build out by checking 60 AI infrastructure stocks, which is focused on companies involved in data centers, networks and high intensity computing demand.
- Look for strong cash generators in precious metals by using the 36 elite gold producer stocks, which filters for established producers that may be sensitive to shifts in bullion sentiment.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com