


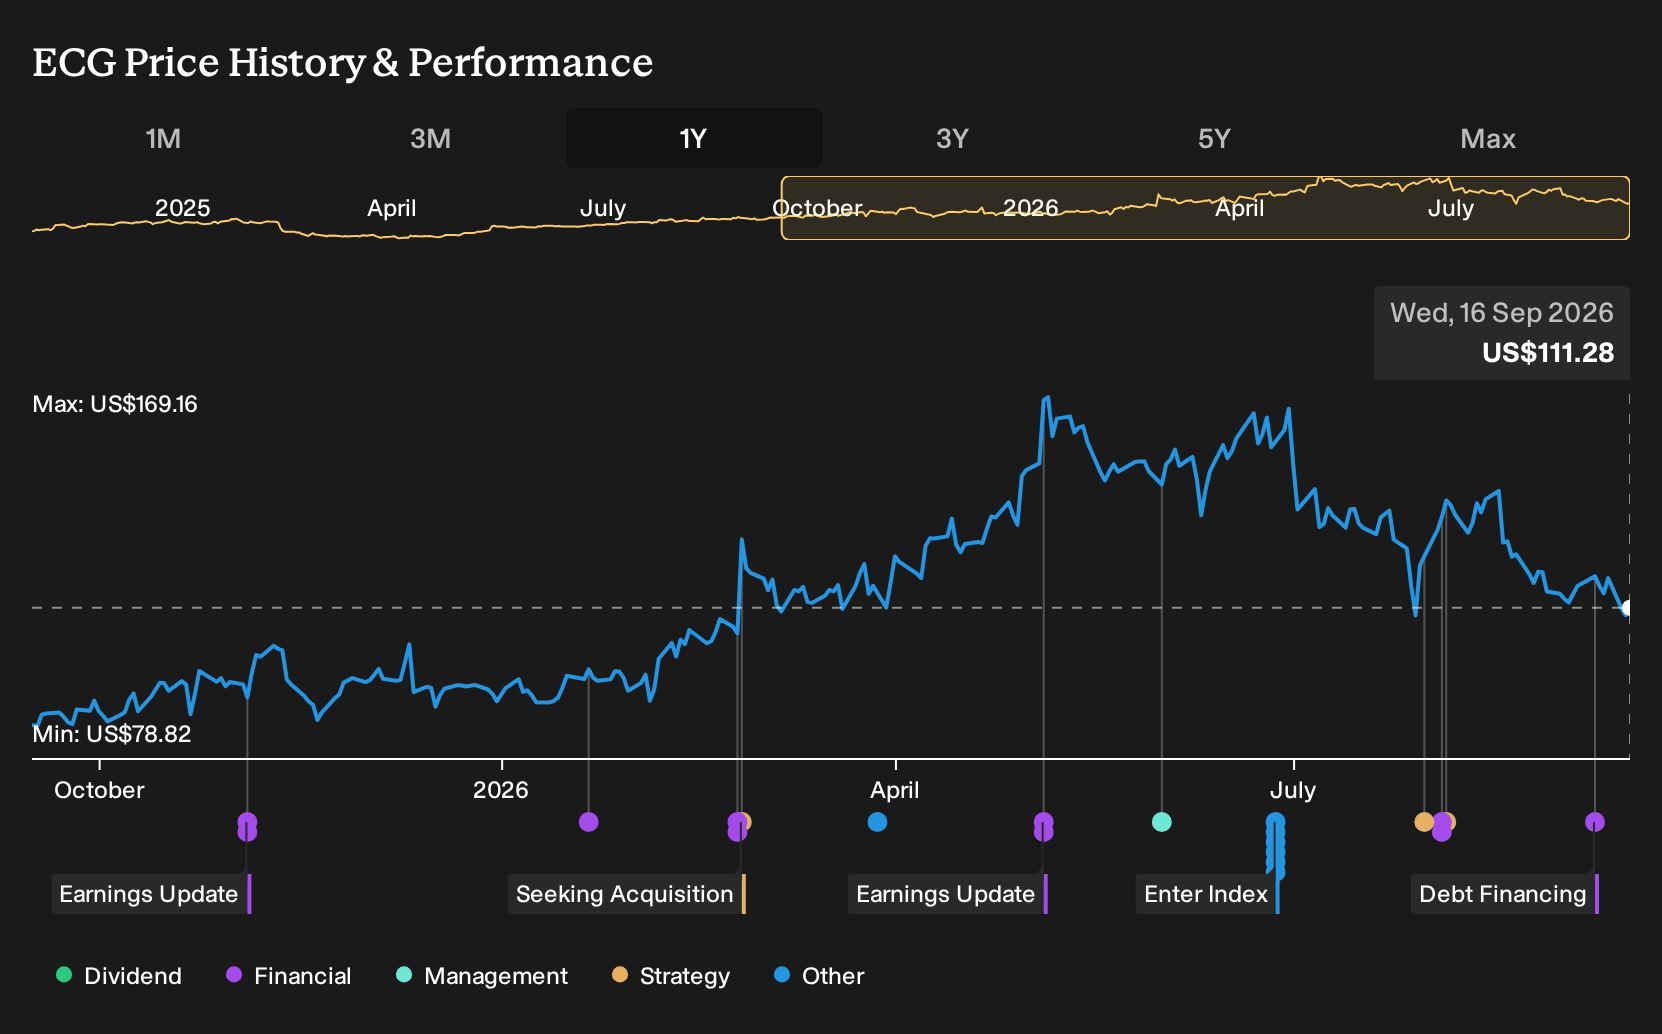
- Everus Construction Group amended its credit agreement with JPMorgan in September 2026, refinancing existing term and revolving loans while increasing term debt to $477.5 million and revolving commitments to $350 million on more favorable interest and fee terms.
- The expanded and repriced facilities give Everus Construction Group added financial flexibility to fund the Epsilon Industries acquisition, support working capital needs and pursue further investment without altering the core credit structure.
- This article examines how Everus Construction Group's improved credit terms and added liquidity influence the investment narrative that is built around its earnings strength.
Everus Construction Group Investment Narrative Recap
To own Everus Construction Group, you need to believe its exposure to complex electrical, mechanical and transmission projects tied to data centers, grid upgrades and industrial sites can keep feeding a healthy earnings engine. The short term swing factor is how quickly new high value work replaces lumpy backlog, especially if customers slow AI or cloud related builds.
The recent credit amendment mostly tweaks funding rather than the operating story. Cheaper and larger debt facilities can smooth working capital and acquisition spend, but they do not remove core risks. The biggest risk remains execution in a tight labor pool and on large, technically demanding projects without eroding margins.
The amended credit agreement with JPMorgan is the key update here. Everus Construction Group refinanced its term loans, lifted term debt to $477.5 million and expanded revolving commitments to $350 million on improved pricing. That gives the business more room to fund the Epsilon Industries purchase and everyday project cash needs.
This matters for catalysts because the enlarged facilities are earmarked to support the Epsilon deal, other acquisitions and general corporate uses. If management executes well, extra capacity could help Everus deepen its data center and power infrastructure footprint. The flip side is higher reliance on external borrowing, which raises the stakes on integration discipline and return on capital.
Everus Construction Group's current analyst narrative points to revenues of $5.8b and earnings of $351.1 million by 2029. This outlook is built on an assumed 10.6% yearly revenue growth rate and an earnings increase of about $96.6 million from $254.5 million today.
Uncover how Everus Construction Group's fair value indicates a 60% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Everus Construction Group's US$3.23b backlog as the key catalyst. They were already pencilling in revenue of about US$5.9b and earnings of US$337.8 million by 2029. You can now ask whether this richer credit capacity makes those upbeat views more or less realistic.
Explore 3 other Everus Construction Group fair value estimates, including one that suggests as much as 80% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Everus Construction Group research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Everus Construction Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Everus Construction Group's overall financial health at a glance.
Looking for more Everus Construction Group style ideas?
If the Everus Construction Group story has sharpened your focus on balance sheets, earnings power and funding flexibility, you can widen the lens with a few curated stock lists built using the Simply Wall St Screener.
- For investors who want potential upside with some downside resilience, consider companies that score well on financial strength and fundamentals by reviewing this list of solid balance sheet and fundamentals (22 results).
- If value is your priority and you like situations where quality meets a reasonable price, you may want to scan this 33 high quality undervalued stocks that fit those criteria.
- Income focused investors who care about cash flow support and yield stability can check out this 6 dividend fortresses that might suit a long term dividend plan.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com