


Rising US interest rates have pushed borrowing costs higher worldwide, which keeps pressure on speculative story stocks and rewards companies with cleaner finances. That backdrop makes Australian penny shares with strong balance sheets and low dilution especially interesting, because every extra dollar of interest matters more when cash is tight. This article walks through three of the most compelling ideas from this high quality small share pool.
The stocks highlighted below are just a small sample of this elite penny share pool, with the full screen surfacing 15 more businesses with equally compelling stories that are not covered here. To go straight to the full set, identify your own filters, and analyze the highest conviction ideas, head into the Elite Penny Stocks screener.
Ora Banda Mining (ASX:OBM)
Overview: Ora Banda Mining is an Australian gold producer and explorer, anchored by its 100% owned Davyhurst Gold Project plus nickel and copper prospects.
Operations: Ora Banda Mining generates A$807.5 million in revenue from gold production and exploration in Australia, with all reported income domestically.
Market Cap: A$2.8b
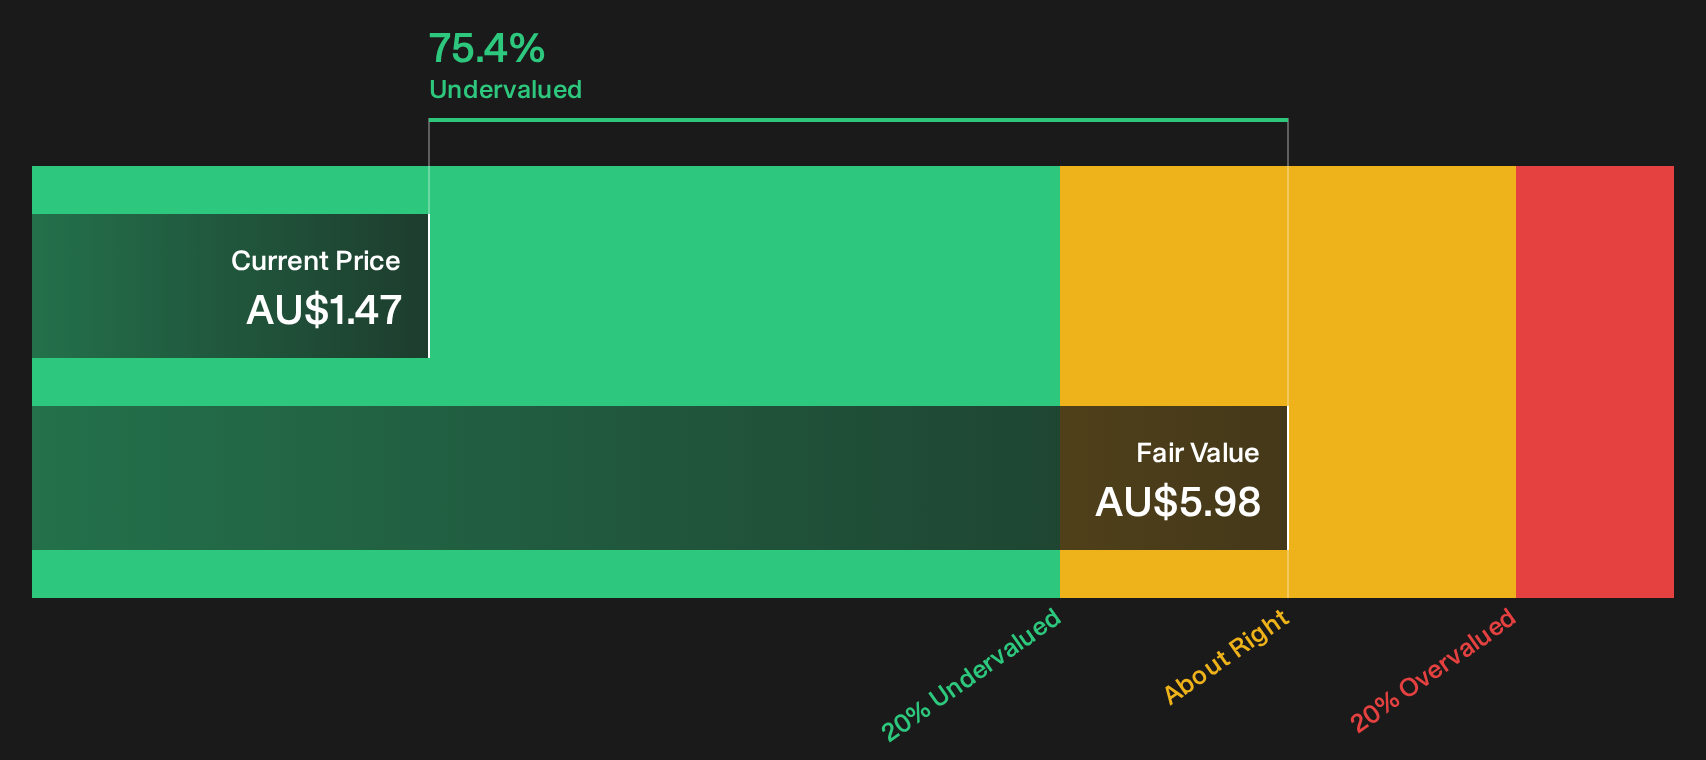
Ora Banda Mining lines up neatly with the Elite Penny Stocks theme, combining 24.8% forecast earnings growth, a 20.8% revenue outlook and a share price estimated to be 75.4% below fair value. That mix of forecast expansion, recent profitability and a deep Davyhurst resource base provides the basis for a constructive investment case, which will depend in part on how one unseen pressure on future margins develops.
That margin pressure question is exactly what the 4 key rewards and 1 important warning sign unpacks, highlighting how Ora Banda Mining’s growth ambitions may amplify either upside or strain.
Alkane Resources (ASX:ALK)
Overview: Alkane Resources is a multi-mine gold and antimony producer anchored by the Tomingley operation in New South Wales, with added copper and base-metal exploration plus stakes in junior miners.
Operations: Alkane Resources generates A$417.1 million from Tomingley, A$269.7 million from Costerfield and A$249.1 million from Bjorkdal, with all A$935.8 million in revenue earned in Australia.
Market Cap: A$2.6b
Alkane Resources fits the Elite Penny Stocks theme through that Tomingley-backed growth story, while its extra mines and metal exposure add both support and complexity to the investment case.
"The main risk is that Alkane is now a more complex business. Instead of one operation, investors must understand three mines, three jurisdictions, different cost structures, underground mining risk, antimony market volatility, and a large future capex project at Boda-Kaiser."
What matters now is how one future funding decision shapes the balance between that growth platform and shareholder returns.
That funding call is exactly where the story gets interesting, and the full narrative for Alkane Resources shows how Alkane Resources could turn that complexity into accelerating optionality for patient shareholders.

Ventia Services Group (ASX:VNT)
Overview: Ventia Services Group runs large-scale infrastructure services across Australia and New Zealand, with telecom network design and digital monitoring tying it directly into 5G, smart meter and IoT buildouts.
Operations: Ventia Services Group generates A$661.1 million from Transport, A$1.72b from Telecommunications, A$1.47b from Infrastructure Services and A$2.15b from Defence and Social Infrastructure.
Market Cap: A$4.7b
Ventia Services Group fits this Elite Penny Stocks screener because its telecom and digital infrastructure work links recurring long-term contracts to technology-led rollouts. This gives investors exposure to 5G and connected infrastructure without relying on a single narrow project cycle.
"A record $20.6 billion work in hand (up 19.4%) and a high contract renewal rate (95%) indicate a robust and growing multi-year pipeline, underpinned by new and renewed long-term government and infrastructure contracts."
The real swing factor is how one quiet shift in contract mix ultimately feeds through into margins, cash returns and growth resilience.
That quiet shift is exactly where the real story starts, and the full narrative for Ventia Services Group breaks down how Ventia Services Group’s contract mix could be masking higher quality, accelerating earnings power.

Seeking Alternatives Before The Crowd?
Fresh ideas move first. Breakout themes gain momentum while the best entry points quietly drop away. Scan what others have not caught yet, then act now.
- Spot income workhorses built on strong cash generation and reliable payouts using the 4 dividend fortresses before those yields get crowded out by latecomers.
- Track cutting edge infrastructure behind AI growth by scanning the 60 AI infrastructure stocks while these enablers are still flying under most radars.
- Hunt future facing materials suppliers with the 29 top copper producer stocks and position ahead of projects that need wiring, grids and electrification at scale.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com