


Interest rates are no longer background noise. The Federal Reserve has lifted its benchmark rate to roughly 3.9%, Treasury yields are pushing higher, and inflation pressure has not backed off as quickly as many hoped. That mix can hurt some assets while creating fresh income potential elsewhere. This article focuses on three U.S. financial stocks exposed to this rate story and explains why each could either reward or disappoint patient investors.
The three stocks in this article are just a sample of the idea, and the full screen surfaced 33 more financial companies with equally compelling rate stories and business narratives that are not covered below. To identify and analyze the highest-conviction candidates for your watchlist, head straight into the U.S. Interest-Rate Beneficiary Financials (Banks, Insurers & Cash Platforms) screener.
StoneX Group (SNEX)
StoneX Group plugs directly into the theme of higher short-term rates, since it runs a global trading, clearing, and payments network where client balances and margin cash can earn more when yields move up.
StoneX Group is a global financial services network that connects commercial clients, institutions, and self-directed traders to markets. It generates most of its revenue in the Commercial segment at about US$153.6b, alongside Institutional at US$1.7b, Self-Directed/Retail at US$369.9m, and Payments at US$225.3m, with an overall market value near US$8.1b.
"The R.J. O’Brien acquisition, completed in July 2025, made StoneX the largest non-bank futures commission merchant in the United States and strengthened its listed derivatives, clearing, and commodity brokerage franchise. That matters because StoneX’s model benefits when clients need to hedge, trade, finance inventory, access liquidity, or manage risk."
What really matters for investors now is how one quiet shift in client balances interacts with this higher rate backdrop to shape future earnings power.
That subtle shift in balances is exactly what the full narrative for StoneX Group unpacks, revealing how rate sensitive cash, derivatives depth, and acquisition integration could be quietly reshaping StoneX Group.

PayPal Holdings (PYPL)
PayPal Holdings brings the interest-rate story into the digital wallet on your phone, since it runs a large payments platform where customer balances and cash-like funds can earn more when short-term yields move higher. This directly ties its business model to the screener’s cash and rate theme.
PayPal operates a global digital payments platform connecting consumers and merchants across brands like PayPal, Venmo and Braintree. It reported US$34.1b from services to financial companies and carries a market value around US$46.0b.
"By applying for an Industrial Loan Company (ILC) charter to form "PayPal Bank," the company aimed to stop renting the regulatory rails from partners like WebBank and Synchrony and start owning them."
For PayPal investors, a key issue now is how a single pressure on funding costs and cash yields shapes the next leg of margin power.
That margin question is exactly where the full narrative for PayPal Holdings picks up, showing how higher cash yields, funding costs, and competition could be masking PayPal’s next earnings gear.
Stifel Financial (SF)
Stifel Financial ties the rate theme directly into wealth management and banking, since client cash and deposits can earn more as short-term yields rise, which matters when the Federal Reserve is leaning hawkish and investors want exposure to both fee income and interest revenue.
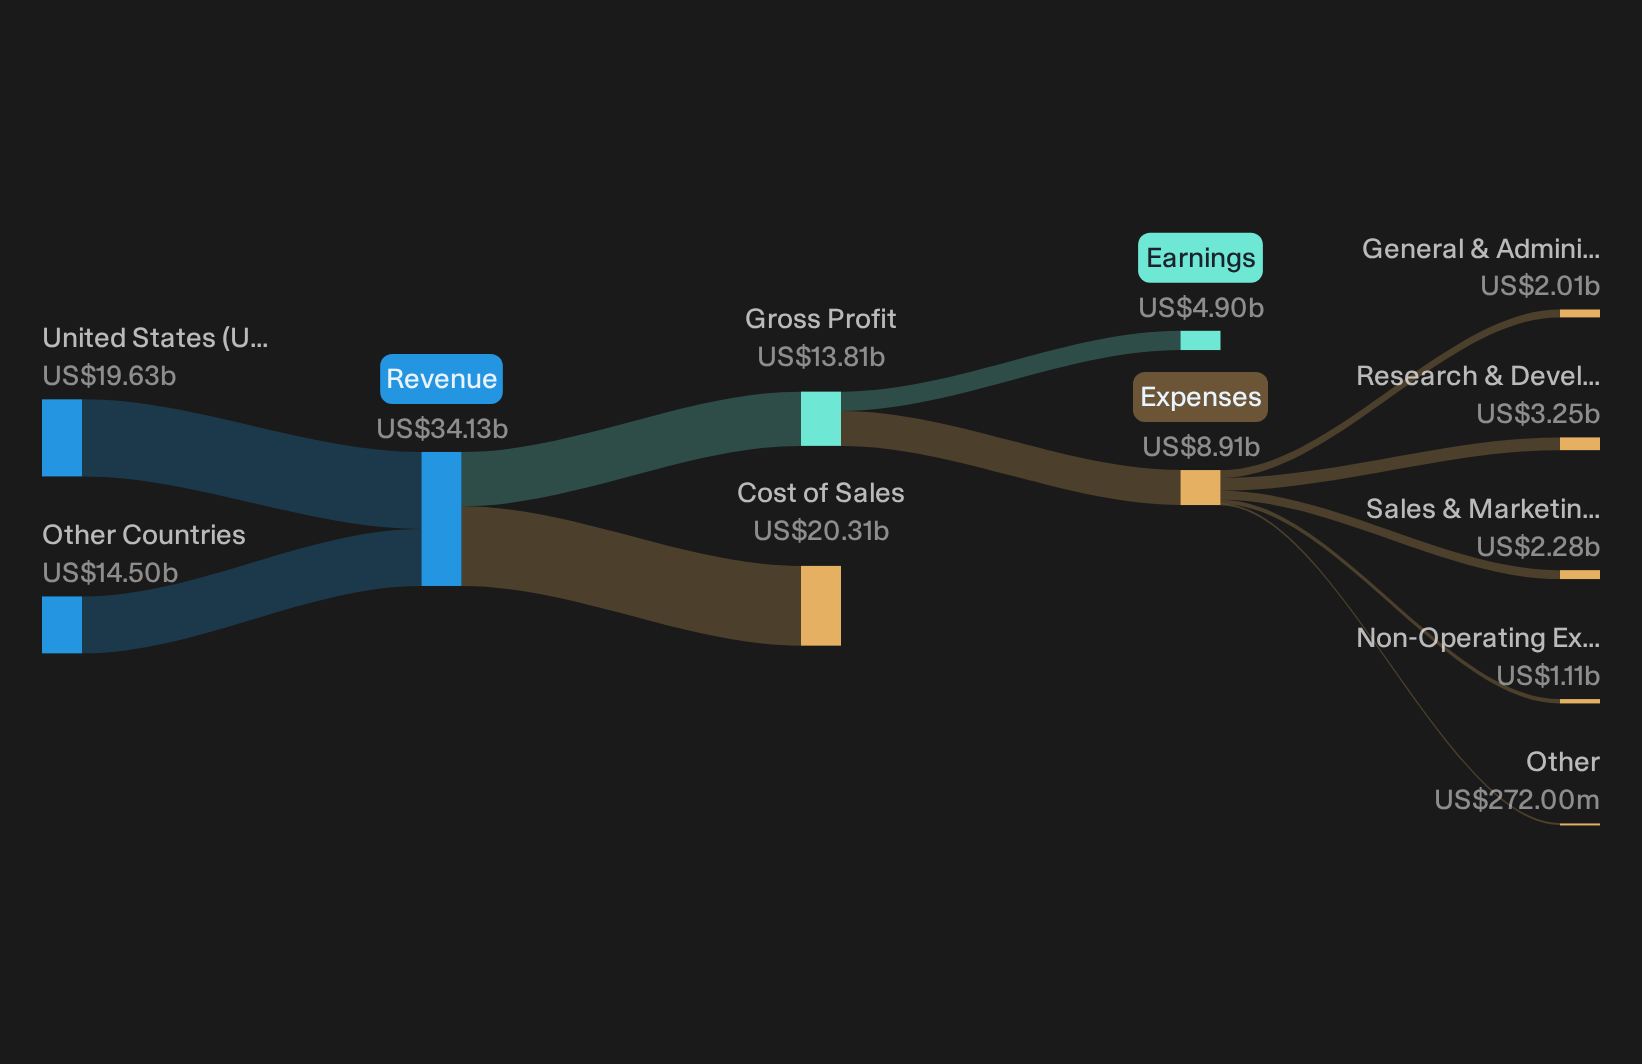
Stifel Financial runs a global wealth and investment banking platform, with Global Wealth Management generating about US$3.7b of revenue, the Institutional Group about US$2.1b, and Other roughly US$100m, and the stock carrying a market value near US$11.6b.
"Strategic recruitment and team additions are set to boost Stifel's Global Wealth Management revenue and enhance long-term productivity."
What happens to Stifel Financial’s earnings power if one quiet assumption about how long higher short-term rates persist proves wrong?
If that assumption proves too cautious, the full narrative for Stifel Financial shows how Stifel Financial’s earnings mix could be quietly decoupling from headline rate moves.

Seeking Alternatives Before Momentum Flies
Fresh breakout ideas do not wait. Momentum shifts, under the radar for now, can get caught once the crowd notices and liquidity thins. Move before prices start flying and get in early.
- Spot resilient cash generators early by scanning the curated list of solid balance sheet and fundamentals (22 results) before the crowd chases quality once weaker balance sheets start dropping.
- Track powerful income ideas by filtering for hand-picked 6 dividend fortresses while yields still compensate you for risk and before payout momentum attracts everyone else.
- Front run the next infrastructure buildout by reviewing curated 38 power grid technology and infrastructure stocks while these essential enablers remain under the radar for now.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com