


Johnson Controls International (NYSE:JCI) has drawn fresh attention after launching its Sabroe HitemHP industrial high temperature heat pumps in Europe, targeting process heat users seeking electrification and lower on site emissions.
Recent trading tells a mixed story for Johnson Controls International. The share price is up 14.85% year to date despite a 30 day share price return that declined 8.74%. Meanwhile, a 1 year total shareholder return of 32.47% signals that longer term momentum has been stronger than the latest pullback.
Scan beyond Johnson Controls International and size up other industrial and energy transition players with resilient balance sheets using our hand picked list of solid balance sheet and fundamentals (22 results).
After a strong 1 year run and a recent pullback, Johnson Controls International now sits closer to most estimates of fair value. Does that setup still reward new risk, or mostly pay investors already on board?
Most Popular Narrative: 26% Undervalued
Against a last close of $140.47, the most followed narrative pegs Johnson Controls International closer to $190 fair value, hinging largely on execution in higher margin building solutions and data center demand.
Johnson Controls' dominant position in high-performance cooling for data centers, coupled with deep, sticky global customer partnerships and unrivaled engineering expertise, creates the potential for a multi-year above-market CAGR in applied HVAC revenues as the AI and cloud infrastructure build-out accelerates, supporting sustained backlog and margin expansion.
See why 2 investors see Johnson Controls International as 26% undervalued.
Result: Fair Value of $190 (UNDERVALUED)
Still, that upbeat Johnson Controls International storyline can break if operational simplification drags on execution or if rising competition in digital building and data center solutions squeezes margins harder than bulls expect.
Find out about the key risks to this Johnson Controls International narrative.
Another Way To Look At Johnson Controls International
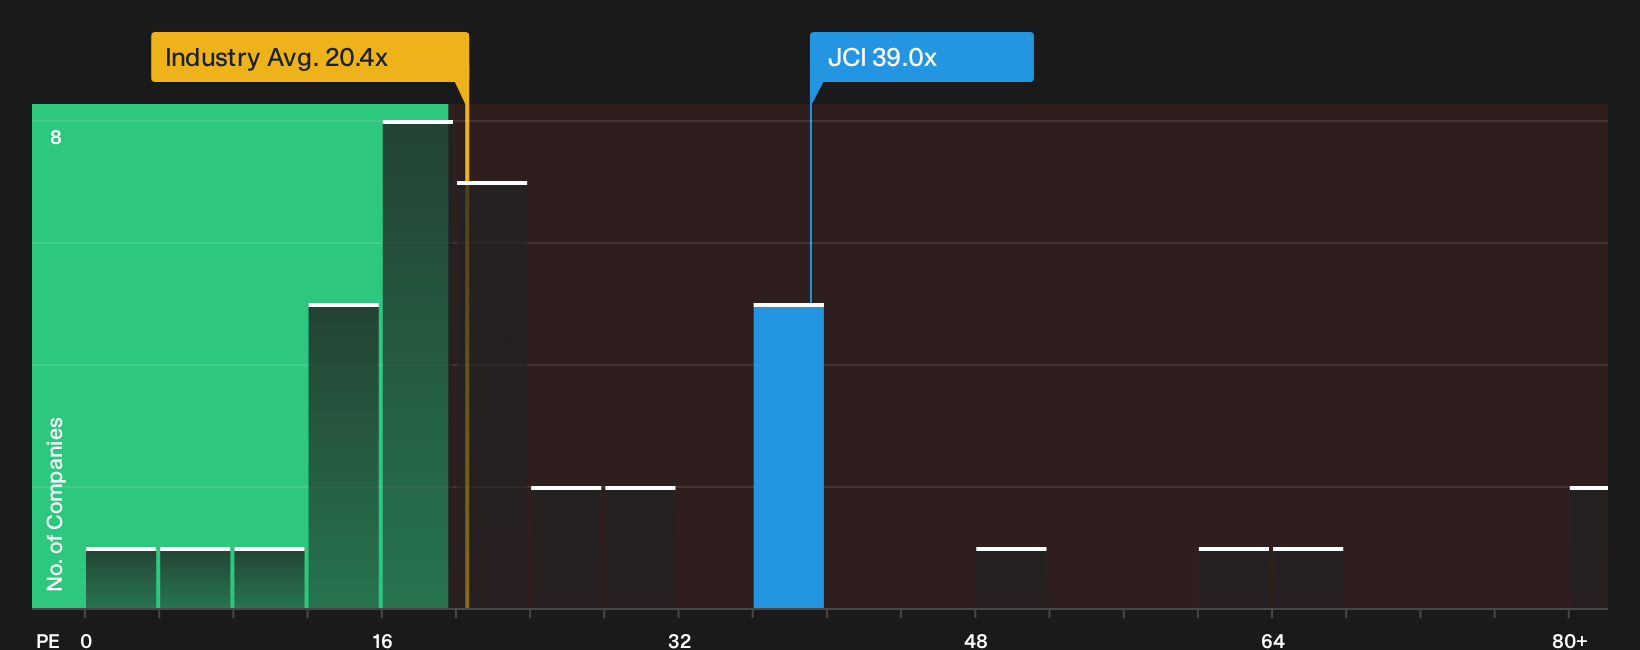
The bullish narrative leans on future earnings power, but the current P/E near 39x tells a tougher story. Johnson Controls International trades well above the US Building industry on 20.6x and above a fair ratio of 35.2x, which points to less margin for error if growth assumptions slip.
Investors weighing that premium can use the valuation breakdown as a cross check on their own expectations for the stock, and stress test what happens if sentiment cools toward the fair ratio path. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Johnson Controls International can easily pull you in one direction. Act while the data is fresh and weigh both sides of the story with 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Johnson Controls International?
If Johnson Controls International has sharpened your focus, do not stop here. Broaden your watchlist now or risk missing opportunities building quietly on the sidelines.
- Target value opportunities early by checking companies screened as quality and potentially mispriced through the 33 high quality undervalued stocks.
- Secure potential income streams by reviewing businesses with stronger yields and resilience using the 6 dividend fortresses.
- Prioritise sleep at night holdings by scanning financially steadier candidates with the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com