


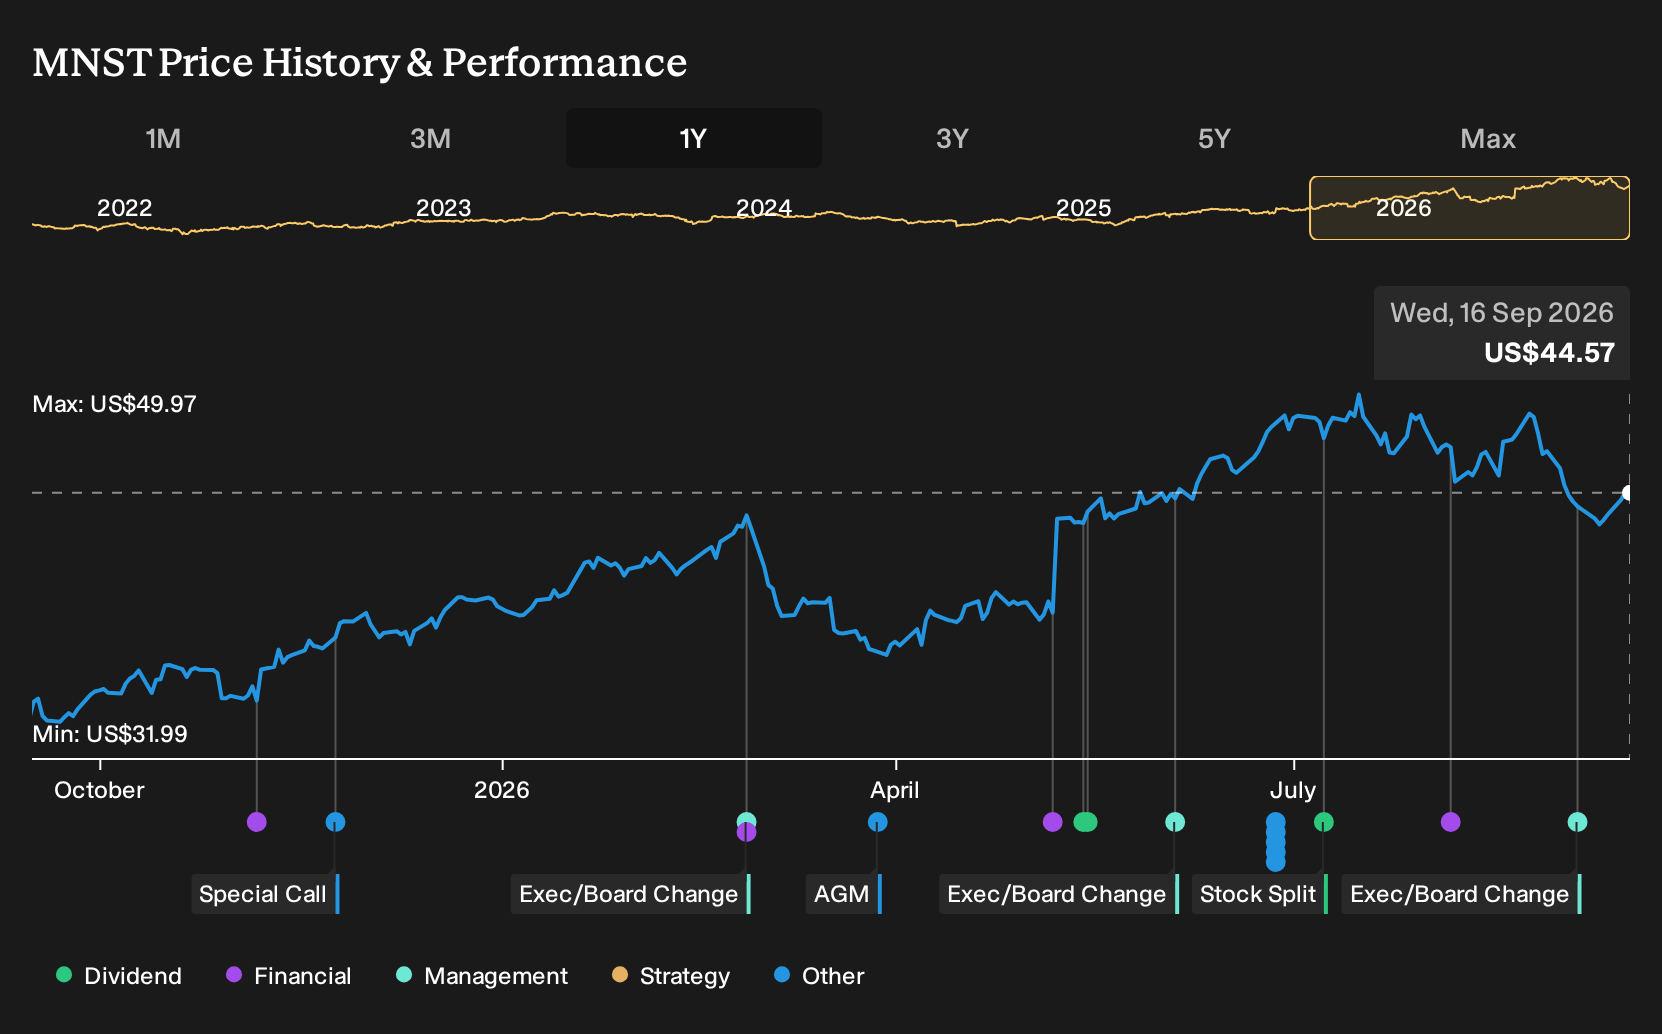
- Monster Beverage reported that its board elected long-time finance executive Matthew S. Burroughs as Chief Accounting Officer and Deputy Chief Financial Officer, formalizing oversight of global accounting, reporting, tax, treasury, and investor relations after almost two decades with the business.
- The expanded remit for Burroughs concentrates key finance functions under a leader with deep institutional knowledge, which can influence how Monster Beverage manages cost discipline, regulatory complexity, and capital allocation across its international footprint.
- This development provides a basis to examine how Monster Beverage's investment narrative is shaped by finance leadership consolidation around Matthew Burroughs in core control functions.
Monster Beverage Investment Narrative Recap
To own Monster Beverage, you need to believe its energy drink portfolio, low and zero sugar push, and international rollout can keep translating into solid earnings and free cash generation despite rising complexity. The biggest short term swing factor is whether mix and pricing can hold margins as lower priced brands and emerging markets contribute more to sales.
The most acute risk right now is pressure on profitability from input costs, tariffs, foreign exchange, and higher litigation and regulatory expenses. The new finance leadership structure around Matthew Burroughs looks incremental for operations. It supports execution but does not materially change these near term business drivers.
The recent emphasis on Monster Beverage's cash generation and a DCF view that the current price roughly tracks intrinsic value is the most relevant backdrop for this leadership change. With a P/E around 41x and the stock trading modestly above one DCF estimate, execution on earnings and cash flow matters more than multiple expansion.
In that context, putting global accounting, tax, treasury, and investor relations under an experienced insider ties directly into those catalysts. Cleaner reporting, tighter cost visibility, and disciplined capital allocation can help Monster Beverage manage margin risks, support its asset light model, and keep the cash story intact if category growth or input costs become more challenging.
Monster Beverage's current analyst narrative points to US$12.0b in revenue and US$2.9b in earnings by 2029, built on forecasts for 9.1% yearly revenue growth and an earnings increase of about US$0.8b from US$2.1b today.
Uncover how Monster Beverage's fair value indicates a 12% potential upside to its current price before the market closes the gap.
Exploring Other Perspectives
One alternate view leans into international expansion as a bigger upside catalyst than the baseline narrative suggests. In that more optimistic camp, analysts were penciling in revenue of about US$13.0b and earnings of roughly US$3.1b by 2029 before this Monster Beverage finance reshuffle. Those expectations could shift as the new oversight structure beds in.
Explore 3 other Monster Beverage fair value estimates, including one that suggests up to 13% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Monster Beverage research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Monster Beverage. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Monster Beverage's overall financial health at a glance.
Looking For More Investment Ideas Beyond Monster Beverage?
If the Monster Beverage story has sharpened your thinking on risk, cash flow, and valuation, it can be useful to benchmark it against other opportunities with different profiles. Use the Simply Wall St screener to line up a wider watchlist that actually fits how you like to invest.
- If you want income resilience at the portfolio level, start with companies that offer robust payouts by scanning through 6 dividend fortresses.
- For investors who care most about quality at a reasonable price, compare Monster Beverage to a focused 33 high quality undervalued stocks to see which businesses combine strong fundamentals with pricing that still looks reasonable.
- When capital preservation and sleep at night risk levels matter most, round out your research with a list of solid balance sheet and fundamentals (22 results) so you can weigh Monster Beverage against peers with sturdy financial foundations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com