


Over the last 7 days, the United States market has experienced a 1.1% decline, yet it remains up by 12% over the past year with earnings projected to grow by 17% annually. In such dynamic conditions, identifying small-cap stocks that are perceived as undervalued and exhibit insider buying can be a strategic approach for investors seeking potential opportunities.
Top 10 Undervalued Small Caps With Insider Buying In The United States
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Regional Management | 6.3x | 0.5x | 36.58% | ★★★★★★ |
| Enovis | NA | 0.5x | 43.14% | ★★★★★☆ |
| Bank of Marin Bancorp | NA | 7.4x | 29.39% | ★★★★☆☆ |
| Union Bankshares | 9.6x | 2.0x | 45.79% | ★★★★☆☆ |
| Shore Bancshares | 11.7x | 3.4x | 36.36% | ★★★★☆☆ |
| Franklin Financial Services | 11.6x | 3.1x | -41.20% | ★★★☆☆☆ |
| Citizens Community Bancorp | 16.2x | 3.6x | 9.94% | ★★★☆☆☆ |
| New Peoples Bankshares | 9.3x | 2.5x | 12.38% | ★★★☆☆☆ |
| Hanover Bancorp | 20.2x | 2.8x | 36.00% | ★★★☆☆☆ |
| Orion Group Holdings | 102.5x | 0.4x | 45.59% | ★★★☆☆☆ |
Let's take a closer look at a couple of our picks from the screened companies.
Lantronix (LTRX)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Lantronix is a company focused on the development, marketing, and sale of industrial and enterprise IoT products and services with a market cap of approximately $0.17 billion.
Operations: Lantronix's revenue primarily comes from the development, marketing, and sale of industrial and enterprise IoT products and services. The company's gross profit margin has fluctuated over time, with a recent figure of 43.79%. Operating expenses include significant allocations to R&D and general & administrative costs.
PE: -60.5x
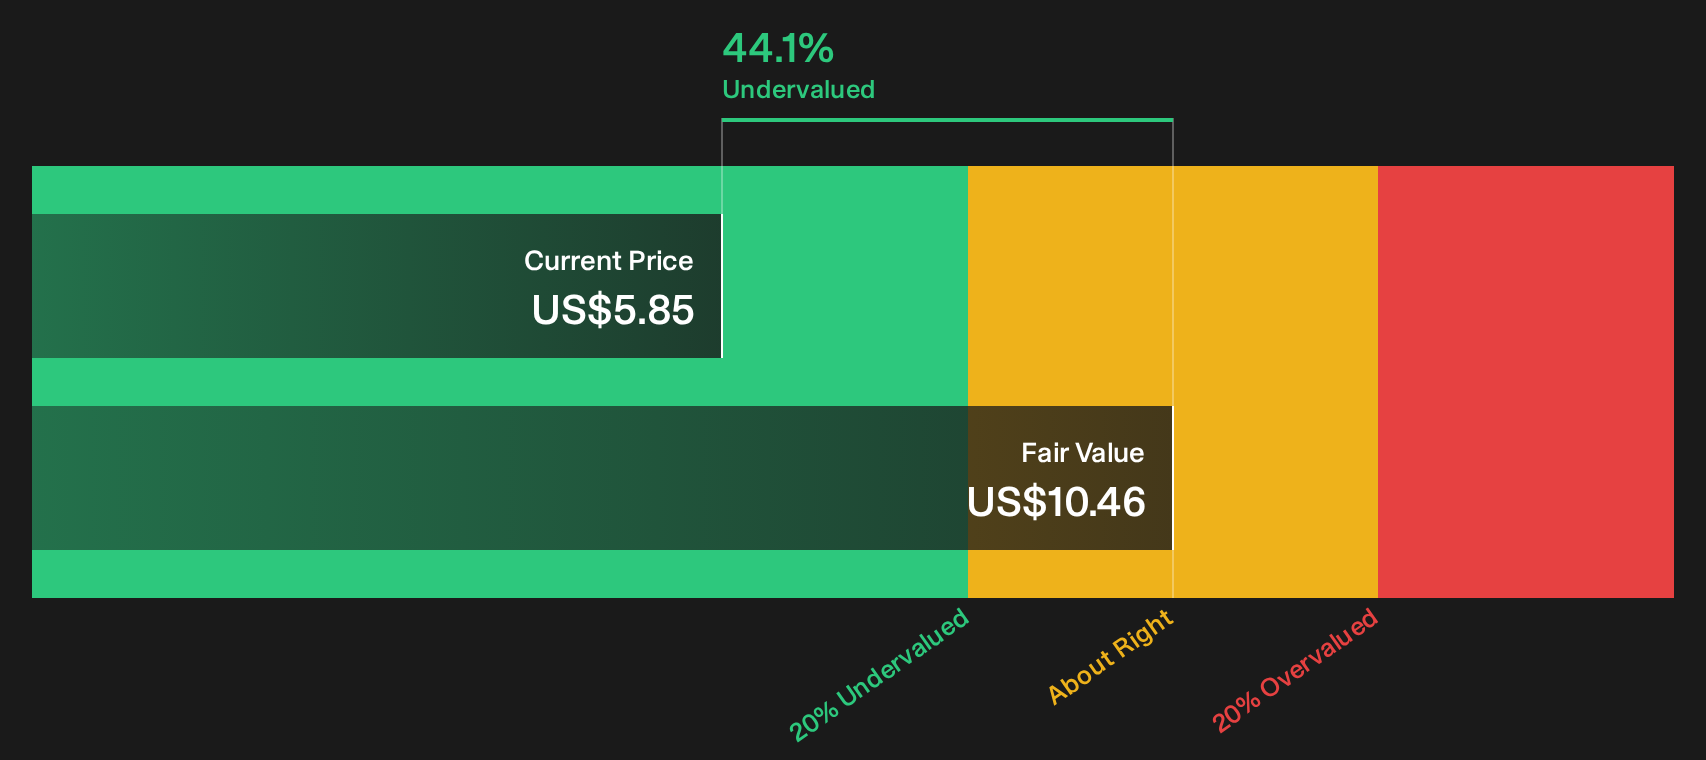
Lantronix, a small company navigating the tech landscape, recently reported improved financials with a net loss reduction from US$11.37 million to US$4.18 million annually. Despite relying heavily on external borrowing, they are making strategic moves in defense technology through collaborations with Swarmer and DoD Solution. Insider confidence is notable as insiders have been purchasing shares throughout 2026. With earnings projected to grow significantly next year, Lantronix's innovative partnerships and technological advancements position them well for future growth opportunities in the defense sector.
- Dive into the specifics of Lantronix here with our thorough valuation report.
Assess Lantronix's past performance with our detailed historical performance reports.
G-III Apparel Group (GIII)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: G-III Apparel Group is a company engaged in the design, manufacturing, and distribution of apparel and accessories, with a market capitalization of approximately $1.15 billion.
Operations: The company generates revenue primarily through wholesale operations, contributing $2.76 billion, and retail activities. Over recent periods, the gross profit margin has shown an upward trend, reaching 43.49% in April 2026. Operating expenses include significant allocations to general and administrative costs and sales & marketing expenses.
PE: 8.9x
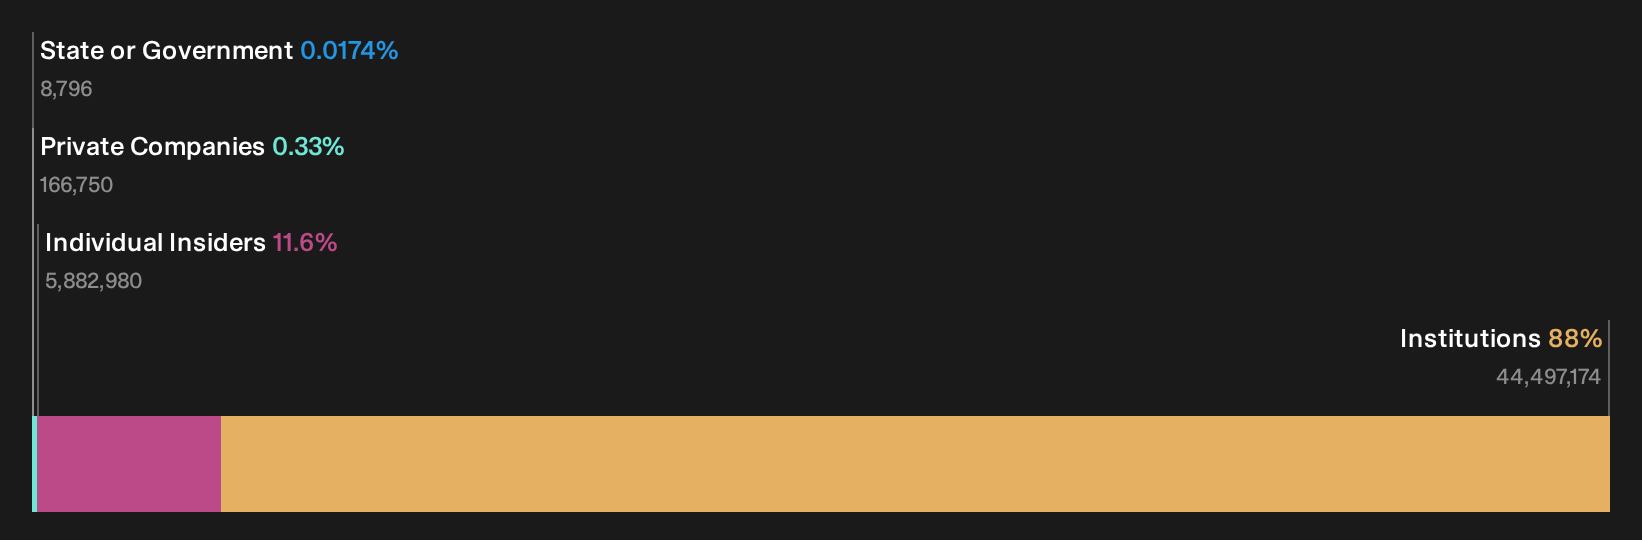
G-III Apparel Group, a small-cap company in the apparel industry, recently updated its buyback program, completing the repurchase of 10.7 million shares for US$250.79 million since 2011. Insider confidence is evident with share purchases indicating belief in future potential. Despite recent guidance forecasting lower net income and sales for Q3 compared to last year, G-III raised its annual earnings outlook to between US$181 million and US$185 million. The firm’s reliance on external borrowing presents higher risk but hasn't deterred growth prospects as evidenced by improved second-quarter profits of US$20.21 million from continuing operations compared to last year's figures.
Grocery Outlet Holding (GO)
Simply Wall St Value Rating: ★★★★★☆
Overview: Grocery Outlet Holding operates a chain of grocery stores focusing on offering discounted products and has a market capitalization of approximately $2.51 billion.
Operations: The company generates revenue primarily through its retail grocery stores, with a recent figure of $4.74 billion. Its cost structure includes significant expenses related to the cost of goods sold (COGS), which was approximately $3.32 billion in the latest period. The gross profit margin has shown fluctuations, recently recorded at 29.99%. Operating expenses also play a substantial role in financial performance, amounting to around $1.35 billion recently.
PE: -3.0x
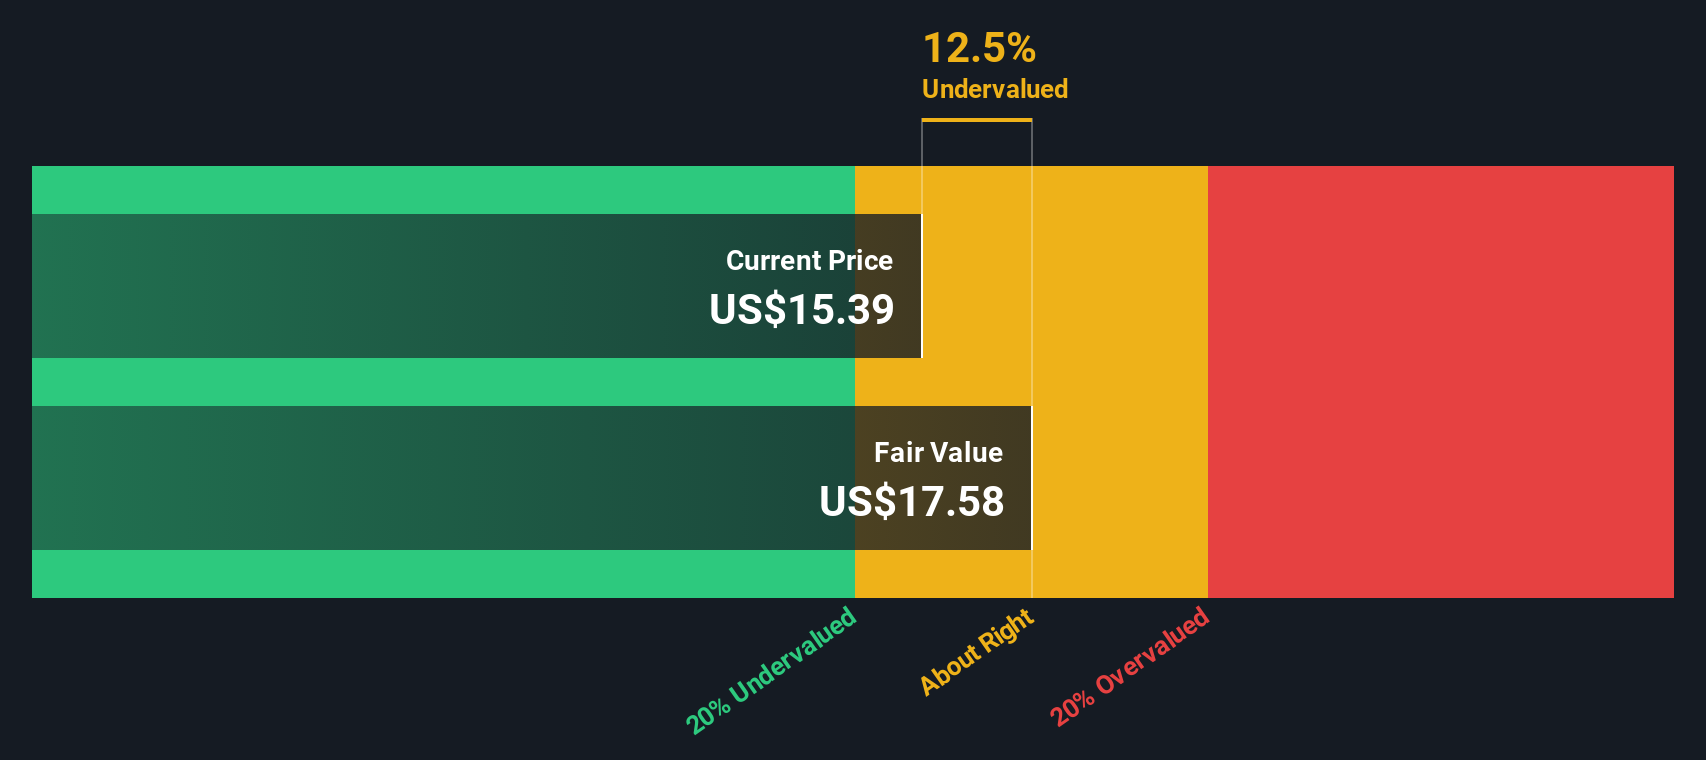
Grocery Outlet Holding, known for its budget-friendly retail model, has seen insider confidence with President Jason Potter acquiring 286,097 shares valued at US$1.69 million, reflecting a strong belief in the company's potential. Despite being dropped from key indices like Russell 2000 Defensive and Value-Defensive Indexes in June 2026, Grocery Outlet raised its fiscal year sales guidance to US$4.70 billion-US$4.72 billion. However, challenges remain as interest payments aren't well covered by earnings and liabilities are solely funded through external borrowing.
Next Steps
- Navigate through the entire inventory of 64 Undervalued US Small Caps With Insider Buying here.
- Shareholder in one or more of these companies? Ensure you're never caught off-guard by adding your portfolio in Simply Wall St for timely alerts on significant stock developments.
- Enhance your investing ability with the Simply Wall St app and enjoy free access to essential market intelligence spanning every continent.
Looking For Alternative Opportunities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com