


National Beverage (FIZZ) just opened its new fiscal year with first quarter results that kept sales roughly flat at US$330.66 million, while net income declined to US$47 million, putting earnings trends under closer investor scrutiny.
The latest earnings release landed alongside a 1-day share price return of 2.58% and a 7-day share price return of 4.11%. In contrast, the 90-day share price return has fallen 11.33% and the 1-year total shareholder return declined 7.7%. This mix of short-term strength and weaker multi-year total shareholder returns suggests traders are reacting to nearer term expectations for National Beverage rather than to its longer record.
Scan beyond National Beverage and see how other consumer-focused stocks with solid fundamentals are trading with our curated 16 high quality undiscovered gems.
Bulls point to steady annual sales and recent share price gains, while bears focus on softer quarterly earnings. For National Beverage right now, which side does the current valuation appear to support?
Price-to-Earnings of 17.2x: Is it justified?
National Beverage closed at $32.18, and on a P/E of 17.2x it screens cheaper than its direct peers on this metric, even though the share price has declined over the past year while the broader US market and beverage sector delivered positive returns.
The P/E ratio compares what you pay today for each dollar of current earnings. For a branded beverage producer with steady annual revenue growth of 2.4% and forecast earnings growth of 4.62% per year, this lens highlights how much of those earnings investors are currently willing to pay for.
FIZZ trades on 17.2x earnings, while the estimated fair P/E is 15x and the global beverage industry sits at 16.8x. That means the stock is cheaper than its peer average described at 58.1x, yet still carries a richer tag than both the sector benchmark and the level the market could move towards if sentiment softened.
Explore the SWS fair ratio for National Beverage.
Result: Price-to-Earnings of 17.2x (OVERVALUED)
Still, National Beverage faces pressure if quarterly earnings soften further or if its longer term share price weakness keeps value focused investors on the sidelines.
Find out about the key risks to this National Beverage narrative.
Another View on National Beverage’s Value
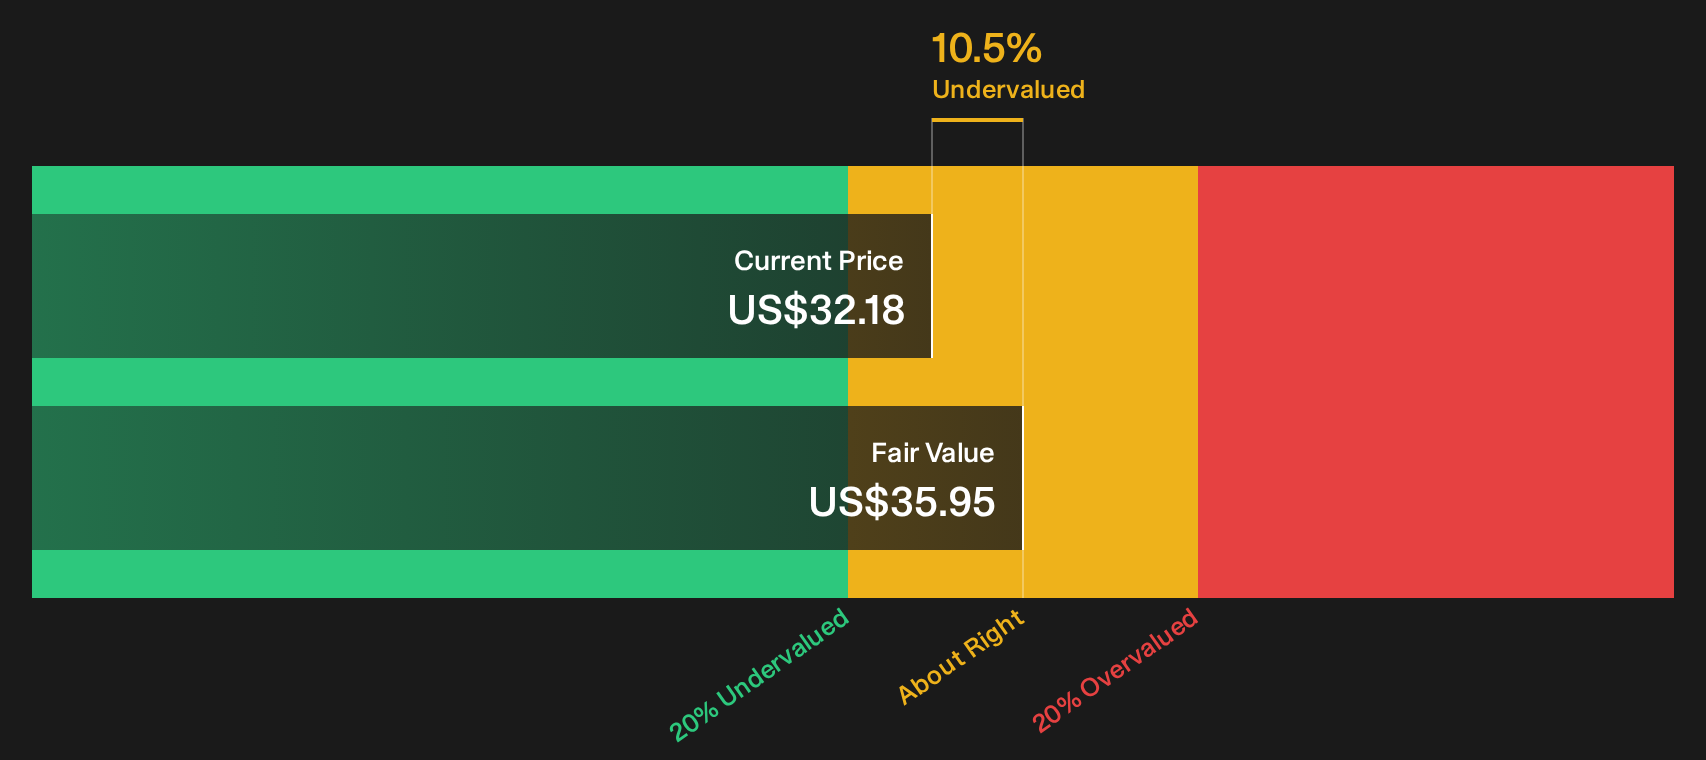
The P/E screen presents National Beverage as slightly expensive relative to both its own fair ratio and the global beverage group. A different lens suggests something else. Our DCF model indicates a fair value of about $35.95 per share, which is around 10.5% above the current $32.18 price, so on this measure the stock appears undervalued. Which signal should be treated as more important: the earnings multiple, or the cash flow path implied in those forecasts?
For a closer look at how this cash flow view is built and what assumptions drive it, take a moment to review the Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out National Beverage for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on National Beverage can make the story feel murky, so it pays to move quickly, stress test the numbers, and reach your own judgment using the 2 key rewards.
Looking for more investment ideas beyond National Beverage?
Do not stop your research with National Beverage. Fresh ideas from different corners of the market can sharpen your judgment and reveal better fits for your goals.
- Target dependable cash generators and see which companies show up among 33 high quality undervalued stocks.
- Prioritize resilience by scanning the 11 resilient stocks with low risk scores for businesses with steadier profiles and lower overall risk scores.
- Strengthen your shortlist with financially robust operators featured in the list of solid balance sheet and fundamentals (22 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com