


ScanSource shares closed at US$56.72 after a strong multi year climb, which puts the focus squarely on whether that price can be supported by the cash the business is expected to generate. With a Discounted Cash Flow (DCF) view available, the key issue is how the stock’s recent run lines up with the intrinsic value implied by those cash flows.
- The share price has gained 88.2% over the past 3 years, which puts a lot of weight on whether the cash flow outlook now fully reflects that rise.
- The company’s ability to convert its distribution driven revenue into dependable free cash flow, helped by its scale and technology focus, can influence how much headroom investors see above the cash that flows back to the business.
- Prefer to judge ScanSource on earnings? See what ScanSource's 14.5x P/E says about the price.
The stock’s next move may depend on whether ScanSource’s current share price is aligned with the intrinsic value suggested by its cash flows.
If you want to explore the same cash flow question that surrounds ScanSource across a broader set of companies, consider comparing it with firms included in the 33 high quality undervalued stocks
Is ScanSource Still Cheap on Cash Flow?
The Discounted Cash Flow (DCF) approach here asks whether ScanSource’s current cash generation can justify the share price of US$56.72. The model uses last twelve month free cash flow of about US$114.3 million and then assumes that future cash generation eases back from that level rather than climbing aggressively.
ScanSource’s projections show free cash flow that remains solid and relatively stable over the next decade, instead of leaning on rapid expansion. That steadier profile means most of the intrinsic value comes from the ongoing cash the business is expected to produce, not from a distant surge in profits. On those assumptions, the DCF output places ScanSource’s estimated intrinsic value modestly above the current share price, so the market is not pricing in especially fast progress beyond the existing cash flow base. Find out what ScanSource could be worth using our Discounted Cash Flow (DCF) estimate.
The ScanSource Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for ScanSource pick up where the valuation puzzle leaves off and explain what would need to happen to future growth, profitability and earnings for the shares to trade meaningfully higher or lower than today’s price. They are available on the platform’s Community page. Each narrative ties a fair value estimate to a clear scenario for ScanSource's potential catalysts and key risks so you can track which version of events starts to match real outcomes over time.
One of the top community narratives on ScanSource: 27% undervalued
"Operational transformation via automation of distribution centers and expanded use of data analytics will significantly reduce operating costs and unlock new revenue per customer opportunities…"
Discover why this Narrative puts ScanSource at 27% undervalued.
One more ScanSource check that belongs beside the cash flow math
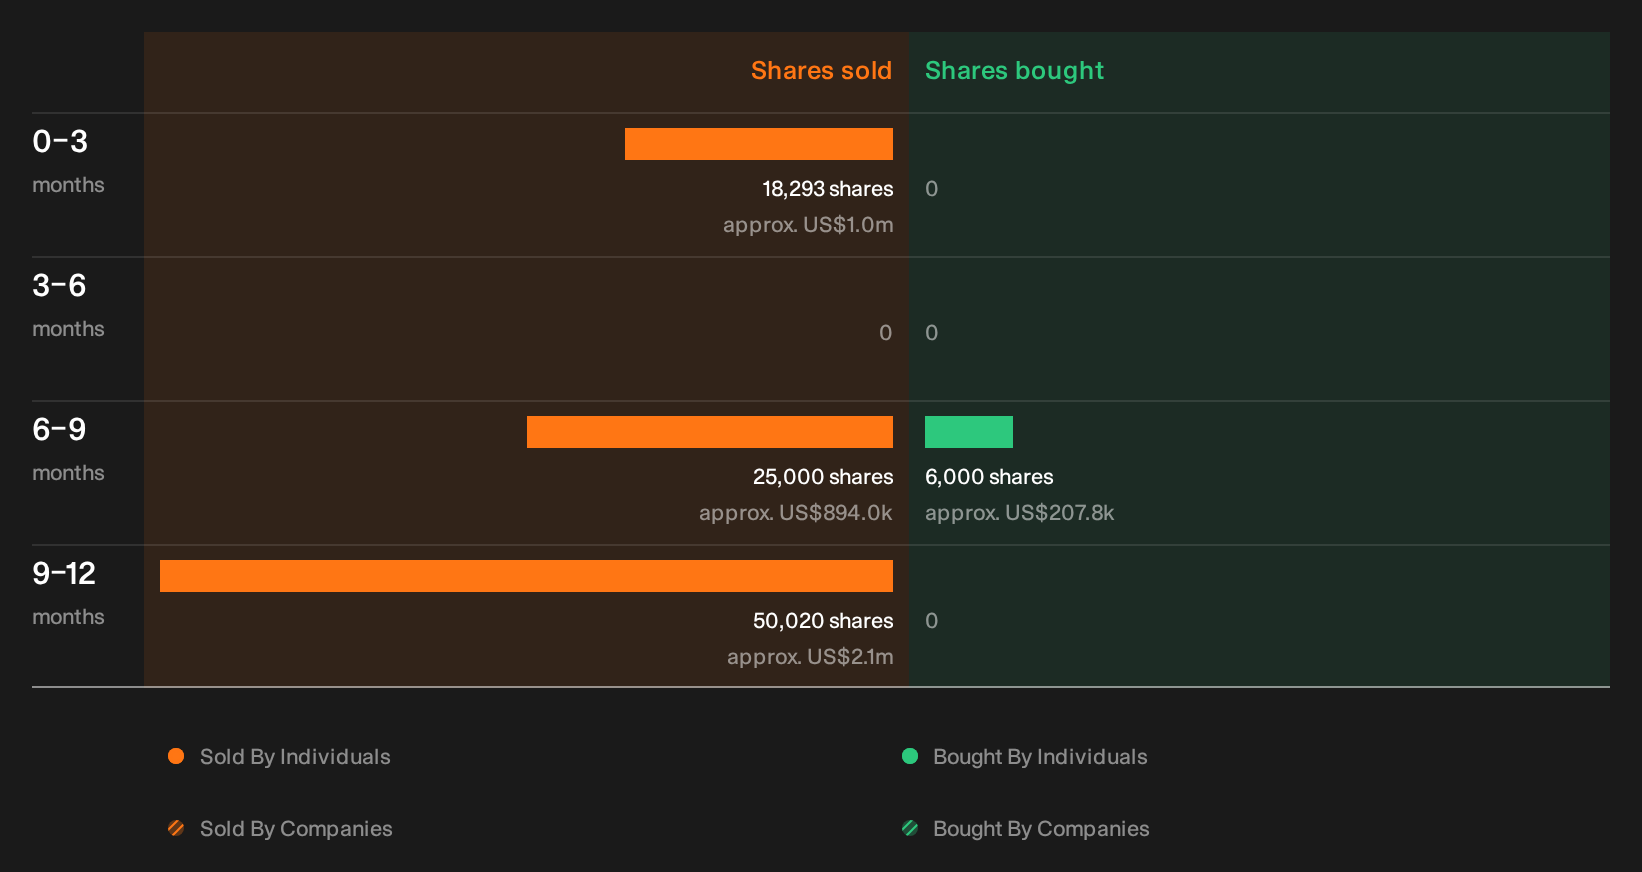
Price and cash generation tell only part of the ScanSource story, because recent insider share sales flagged by our checks raise fresh questions about who sold, how much, and what it might signal next. See the recent insider selling flagged for ScanSource.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com