


Kaiser Aluminum (KALU) just caught fresh attention after an upgrade to a top Zacks rating, tied to more constructive earnings expectations and a more confident read on the company’s underlying performance.
Despite the Zacks upgrade, Kaiser Aluminum’s recent share price action has been choppy, with the stock down 17.85% on a 30-day share price return and 16.62% on a 90-day share price return, even as the year-to-date share price return of 26.67% and a 1-year total shareholder return of 102.85% point to momentum that has been strong over a longer stretch.
Scan for other materials stocks showing analyst upgrades and price dislocations similar to Kaiser Aluminum within the curated 33 high quality undervalued stocks.
Kaiser Aluminum now sits in that awkward zone where the rating just improved, but the price has already sprinted higher and then pulled back hard. Do you lean into the reset here, or hold out for an even cheaper entry before the valuation work lines up for you?
Most Popular Narrative: 10% Undervalued
Kaiser Aluminum is trading at $152.38, while the most widely followed narrative anchors fair value at $169.25. The current pullback sits against a higher long run estimate built on detailed assumptions about margins, capex and cash flow.
The completion of the Trentwood Phase 7 plate expansion positions Kaiser to capture rising commercial aircraft and defense build rates, which may lift aerospace conversion revenue and support a return to mid to high 20 percent EBITDA margins as volumes normalize.
Ramp up of the fourth coated line at Warrick and the strategic mix shift away from bare products into higher value coated packaging may expand conversion revenue per pound and structurally improve net margins as start up costs taper off through 2026.
See why 5 investors see Kaiser Aluminum as 10% undervalued.
The narrative uses a 9.68% discount rate and assumes revenue of about $4.4b and earnings of $202.2m by 2029, with Kaiser Aluminum trading on a P/E of 18.5x at that point. Those inputs, together with a forecast profit margin of roughly 4.6% and modest share count growth, are what underpin the $169.25 fair value figure and the conclusion that the stock screens as about 10% undervalued at the last close.
Result: Fair Value of $169.25 (UNDERVALUED)
Still, the narrative can break if aluminum pricing weakens further or if Kaiser Aluminum fails to hit the assumed 18.5x P/E and 4.6% margin profile.
Find out about the key risks to this Kaiser Aluminum narrative.
Another View on Kaiser Aluminum’s Valuation
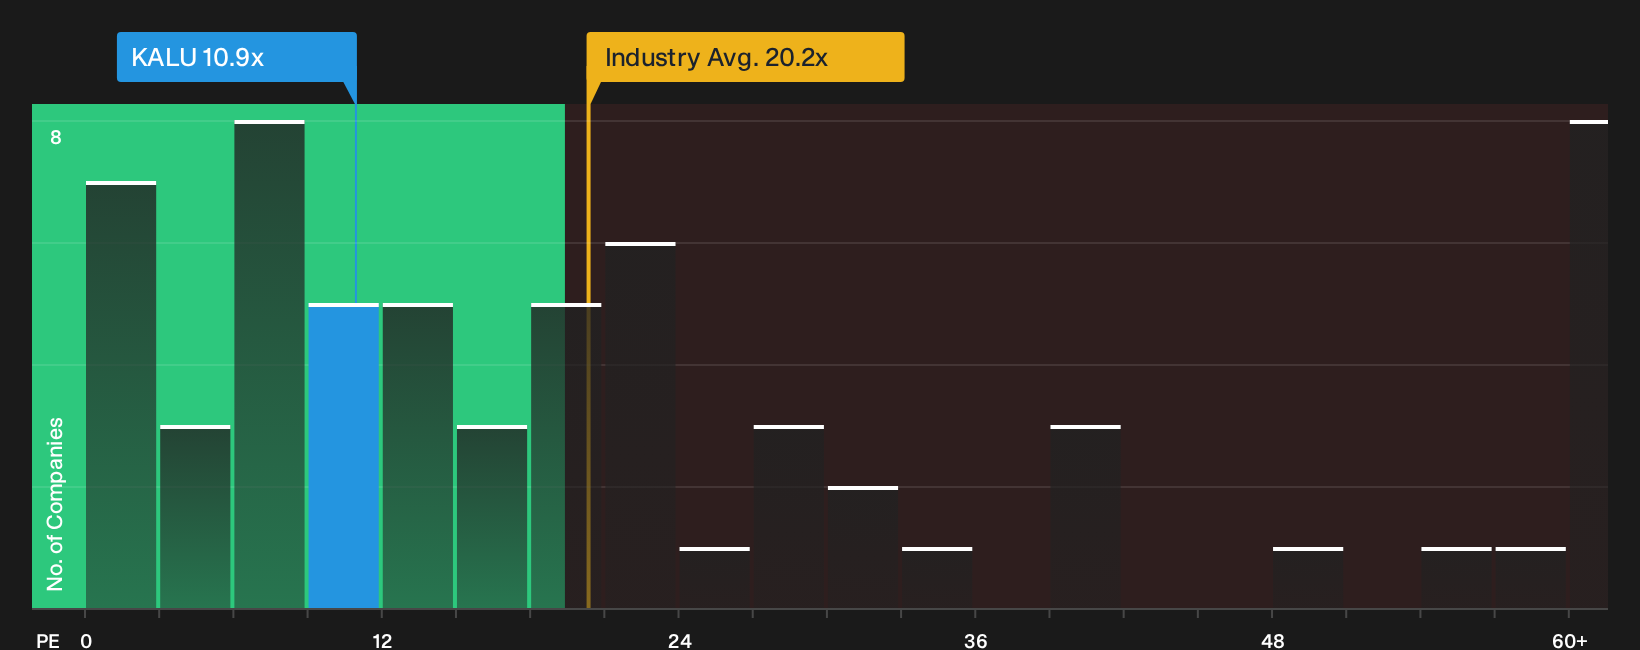
The narrative fair value for Kaiser Aluminum points to roughly 10% upside, but the market’s own yardstick tells a slightly different story. At a P/E of 10.9x, the stock trades well below the US Metals and Mining average of 20.4x and under the 14.6x fair ratio estimate. That gap suggests the market is either building in real earnings risk or leaving room for a valuation catch up. Which side of that trade do you think you are on?
For a closer look at how this P/E gap might evolve and what it could mean in practice for valuation risk or opportunity, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Kaiser Aluminum’s recent move can be confusing, so consider acting while sentiment is still resetting and weigh both sides. To see how the full picture of concerns and potential upside stacks up, review the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Kaiser Aluminum?
If Kaiser Aluminum has your attention, do not stop there. Use the Simply Wall Street Screener to surface fresh opportunities before the crowd catches on.
- Target resilience first and hunt for companies with robust finances through the list of solid balance sheet and fundamentals (22 results).
- Spot potential mispricing early by scanning the curated 16 high quality undiscovered gems.
- Prioritize sleep-at-night holdings and focus on stability with the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com