


IDP Education (ASX:IEL) is back on investor radar after reshaping its board, with experienced directors Anne Brennan and Tracey Ah Hee joining as independent non executive directors while Ariane Barker and Andrew Barkla prepare to retire.
Investors have noticed the board refresh at IDP Education following a very difficult stretch, with the share price down 72.87% year to date and the 5 year total shareholder return declining 94.71%. The recent 1 day and 7 day share price returns show only a modest short term lift, which does little to offset the sharp 30 day and 90 day share price declines of 27.78% and 39.06%.
Scan how IDP Education compares with other beaten down but fundamentally screened opportunities by running the hand picked 5 high quality undervalued stocks.
After a fall this steep and a modest recent bounce, the key tension for IDP Education holders is simple: Does the current price still compensate you for the risk on the table as valuation comes under the microscope next?
Most Popular Narrative: 66% Undervalued
IDP Education last closed at A$1.56, while the most followed narrative pegs fair value closer to A$4.65. This frames the valuation gap that keeps contrarian investors interested.
The asymmetry, in one line
At recent prices you pay the no-growth, no-recovery price, and get the IELTS franchise, the demonstrated pricing power, structural market growth and any volume normalisation for free. Downside is anchored at the no-growth EPV (≈ the current price) as long as trough EBIT holds above ~A$113m, and upside needs only a multiple re-rate, not a heroic forecast.
See why 4 investors see IDP Education as 66% undervalued.
According to ANTONI0, the central narrative rests on IDP Education earning power stabilising rather than structurally collapsing, with an Earnings Power Value estimate that clusters around A$4.65 per share. That view leans heavily on pricing resilience in IELTS and student placements, the cash generation profile and the idea that current policy settings in key destination countries are cyclical rather than permanent.
The same narrative also highlights that the share price decline has moved much faster than the underlying business metrics, with A$795.4m of revenue and A$12.3m of net income in the most recent year, alongside an estimated fair value that sits well above today’s market capitalisation of about A$433.5m. For readers weighing that gap, the question is less whether IDP Education has had a difficult period and more whether those issues are already more than reflected in a stock that screens as heavily discounted on a discounted cash flow basis.
Result: Fair Value of A$4.65 (UNDERVALUED)
Still, the IDP Education story unravels quickly if policy tightening proves permanent or if IELTS loses ground in visa recognition to cheaper rivals.
Find out about the key risks to this IDP Education narrative.
Another View On IDP Education’s Valuation
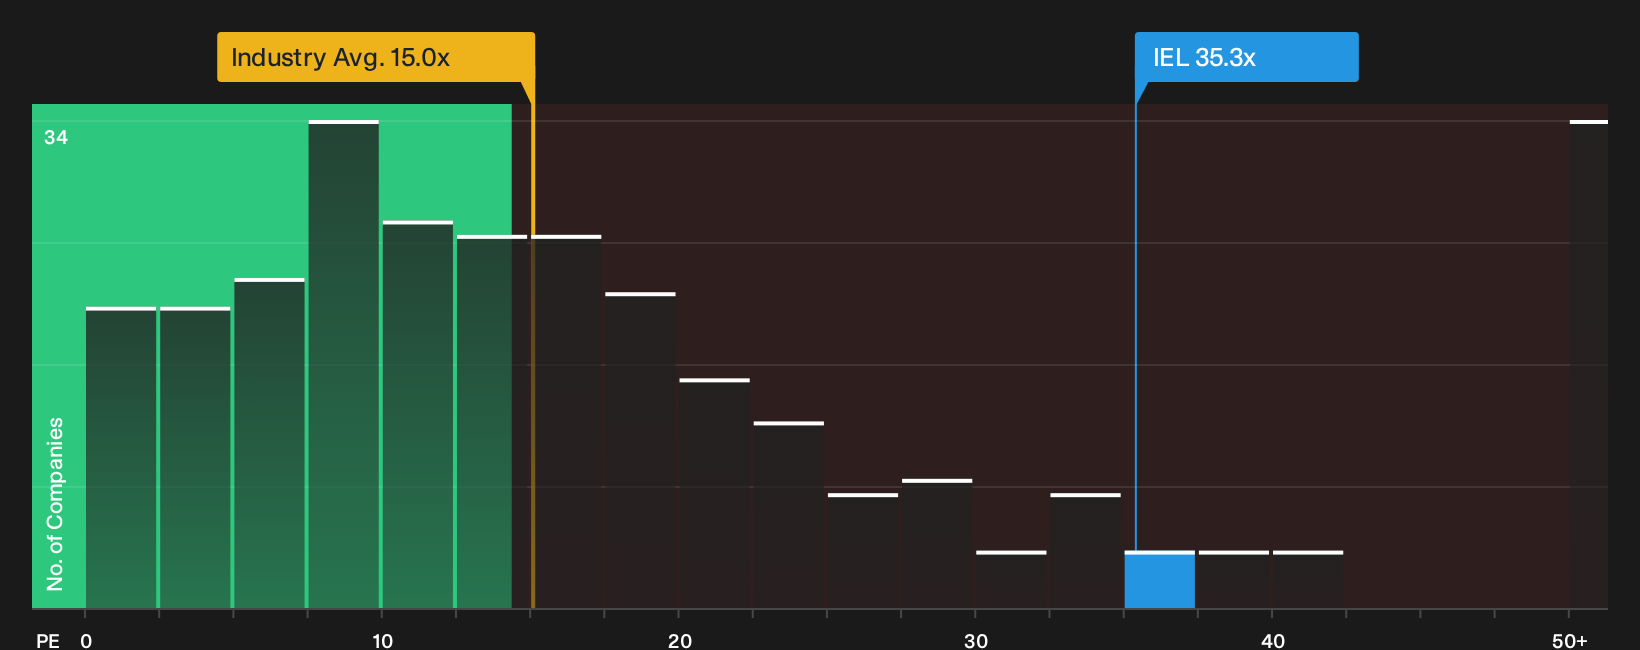
On earnings multiples, IDP Education looks far less generous. The stock trades on a P/E of 35.3x, while the global Consumer Services peer group sits closer to 15x and the fair ratio for the business is estimated at 32.9x. That gap points to valuation risk, even where a discounted cash flow model flags a large upside. For investors, the real question is which yardstick will matter most if sentiment keeps shifting?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around IDP Education is clearly split, so do not wait for consensus to form before checking the data yourself and stress testing your own thesis. To weigh up both the possible upside and the clear concerns, start with the 2 key rewards and 3 important warning signs.
Ready for more investment ideas beyond IDP Education?
If IDP Education has you reassessing risk and reward, do not stop there. Use the same disciplined approach to size up fresh opportunities across the market today.
- Target potential mispricings by scanning a curated pool of beaten down but fundamentally screened opportunities through the 5 high quality undervalued stocks.
- Prioritise resilience first and hunt for companies with robust finances by running the list of solid balance sheet and fundamentals (12 results).
- Seek out under-the-radar prospects with strong foundations and growth potential using the 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com