


Higher U.S. interest rates are keeping borrowing costs elevated worldwide, which can pressure weaker companies and leave investors paying up for fashionable stories. Japanese quality stocks with strong cash generation and sturdy balance sheets can look appealing when money is no longer cheap. This article highlights three high quality Japanese businesses that our value screen flags as undervalued, and explains why they may deserve a closer look now.
The three stocks covered next are just a snapshot of the idea, and the full screen surfaced 14 more Japanese quality companies with equally compelling stories that are not included here. To go straight to the source and identify your own high conviction opportunities, head into the High Quality Undervalued Stocks screener.
NEXTAGE (TSE:3186)
Overview: NEXTAGE is a Japanese dealer focused on buying and selling new and used cars, with in-house services that support recurring cash flow.
Operations: NEXTAGE generates all of its ¥734.3b revenue in Japan from automobile sales and associated services, including maintenance and inspections.
Market Cap: ¥228.7b
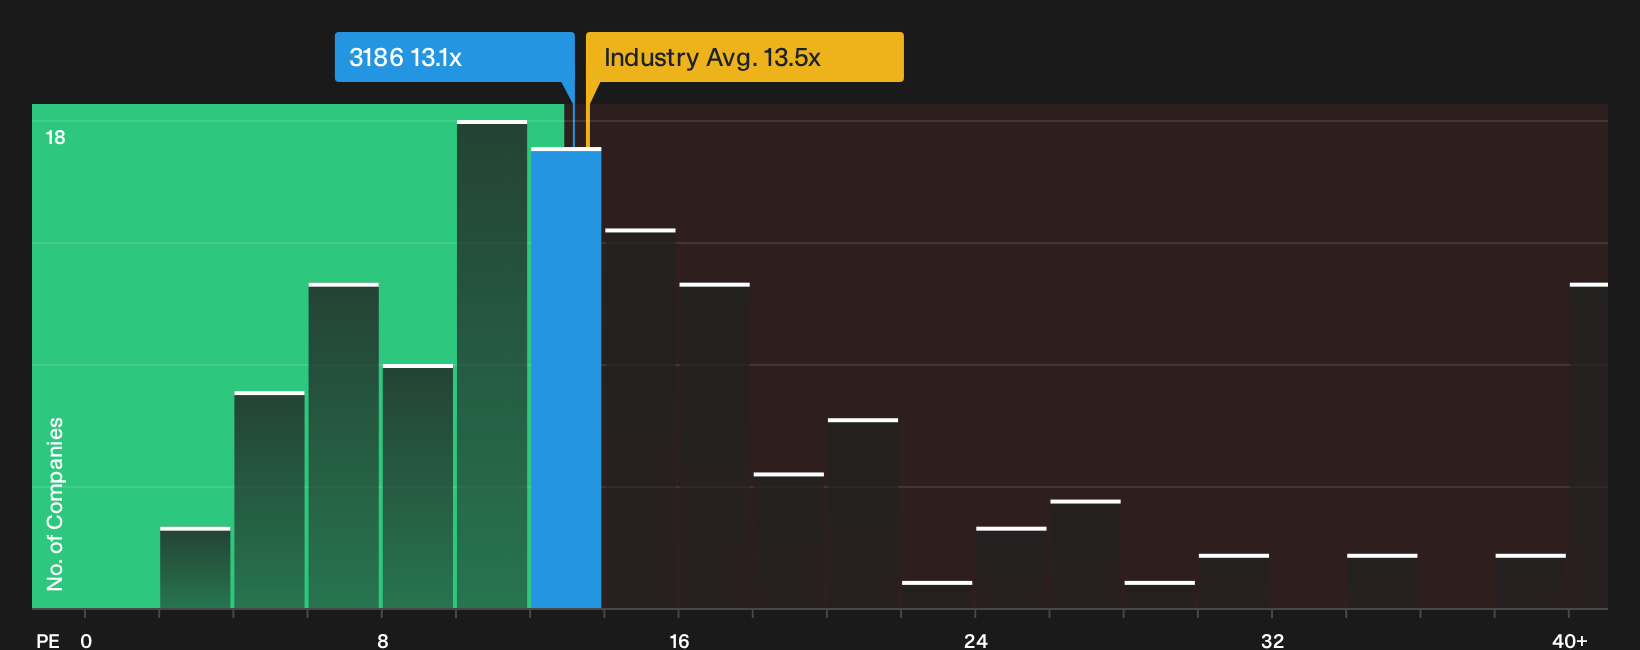
NEXTAGE sits in this high quality undervalued screen because its core car trading operation generates steady cash flow that is reinforced by maintenance, inspection and insurance services. However, the stock trades on about 13.1x earnings while showing rising margins and strong guidance. The real test for this valuation gap will come down to how one pressure on its balance sheet plays out.
That balance sheet question is exactly what sits at the heart of the 3 key rewards and 1 important major warning sign, where rising earnings guidance meets the key pressure point investors are debating.
BuySell TechnologiesLtd (TSE:7685)
Overview: BuySell Technologies Ltd runs an asset light reuse business in Japan, buying and reselling kimonos and branded goods that support strong cash conversion.
Operations: The group generates all ¥124,962 million revenue in Japan from its reuse business for kimonos and branded products across multiple channels.
Market Cap: ¥180.2b
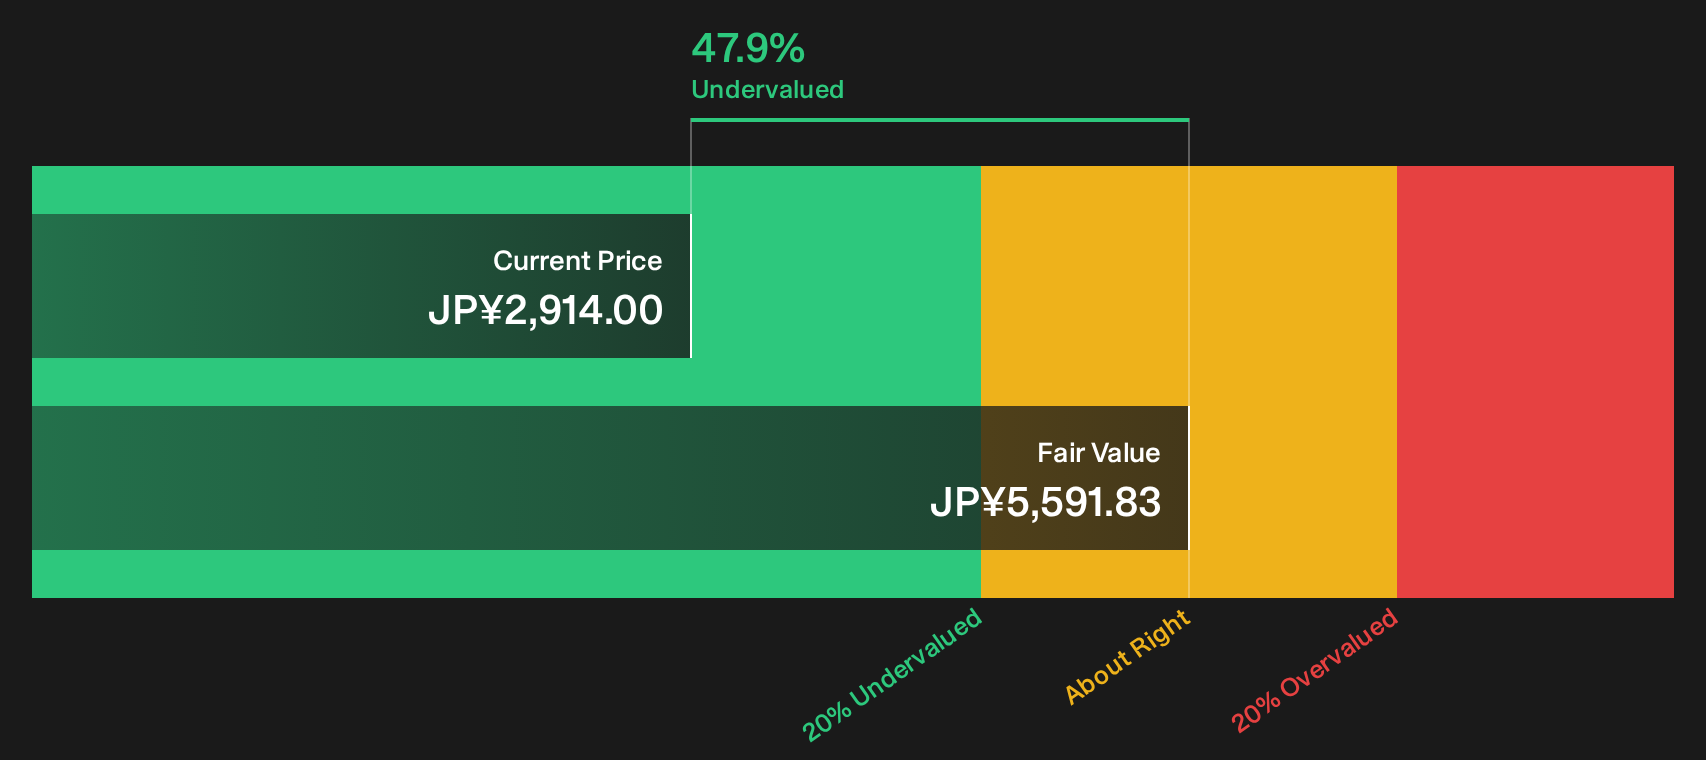
BuySell Technologies Ltd ties neatly into this high quality undervalued screen because its reuse model converts branded goods and kimonos into recurring cash. Our value work flags the shares trading well below estimated fair value despite strong earnings growth and high forecast ROE. One key funding pressure remains the factor that could decide how sustainable those margins are if conditions change.
That funding question is exactly what the 4 key rewards and 1 important warning sign unpacks, separating healthy cash conversion from the pressure points that could quietly reshape the margin story at BuySell Technologies Ltd.
ANYCOLOR (TSE:5032)
Overview: ANYCOLOR is an entertainment group that runs the NIJISANJI VTuber project, managing virtual talent, content, and events that monetize recurring digital IP.
Operations: ANYCOLOR generates ¥56,533 million from its Video Content Related Business, centered on NIJISANJI VTuber activities and associated media.
Market Cap: ¥198.7 billion
ANYCOLOR fits this high quality undervalued screen because its NIJISANJI VTuber ecosystem generates recurring cash flows from digital content, licensing, and merchandise, supported by a balance sheet that enables reinvestment rather than relying on fragile funding.
"Refocusing on the Japanese and Asian markets have produced significant results, cut costs and as a result shareholders have rewarded Nijisanji’s efforts with strong market backing which propelled their share price past all-time highs."
What happens to margins and valuation from here depends on how the pressure around future monetization choices is ultimately resolved.
That monetization tension is exactly what the full narrative for ANYCOLOR unpacks, revealing how ANYCOLOR could balance fan engagement, pricing power and VTuber expansion without stalling momentum.

Seeking Alternatives Before The Crowd
Fresh ideas move first. Stocks gaining quiet momentum often get re-rated fast once attention arrives, and that window can shrink quickly. Scan under-the-radar candidates and get in early.
- Target resilient compounding potential by reviewing the 12 resilient stocks with low risk scores that have been filtered for stability so you are not just chasing whatever is flying this week.
- Ride structural shifts in computing by scanning the 25 quantum computing stocks curated for companies positioned before quantum adoption moves from under the radar for now to front-page momentum.
- Spot early inflection stories by tracking the 74 high quality undiscovered gems that may be quietly building fundamental strength before the crowd catches on and bidding starts driving prices higher.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com