


- ACI Worldwide recently expanded its ACI Connetic platform with a cloud-native financial messaging capability that helps banks manage real-time payments, ISO 20022 migration, and complex domestic and cross-border payment networks.
- The new messaging layer lets institutions decouple communication from core payment engines, which can reduce operational friction while creating cleaner data for analytics and AI-driven payment services.
- This development provides additional context for understanding how ACI Worldwide's investment narrative intersects with the cloud-native financial messaging rollout inside ACI Connetic.
Scan beyond ACI Worldwide and line up other payment and AI infrastructure plays using our hand picked 60 AI infrastructure stocks for your next round of research.
ACI Worldwide Investment Narrative Recap
To own ACI Worldwide, you need to believe in a long transition toward real time, data rich payments where banks pay for modern plumbing rather than just transaction throughput. The expanded ACI Connetic messaging layer fits that story because it sits directly on the rail modernisation trend and supports ISO 20022 complexity for large institutions.
The near term swing factor is execution on Connetic adoption and converting the reported $7b backlog and ARR momentum into steadier Payment Software results. The biggest risk remains the cost and intensity of this product overhaul, especially with high debt and heavy competition, which could keep margins and cash flexibility under pressure if deals slip.
The Connetic financial messaging launch is the clearest current proof point behind that thesis. It deepens ACI Worldwide’s role in core infrastructure instead of only running payment engines. By handling translation, routing and data enrichment centrally, the product ties directly to cross selling opportunities across banks and billers already on the broader platform.
This same announcement also intersects with the AI commerce research ACI Worldwide released, which highlighted low current trust in autonomous purchasing. The more consistent, structured data ACI can generate through Connetic, the better positioned the company is to support merchants and banks that want real time risk controls on AI driven payments, a practical catalyst for future contracts.
ACI Worldwide's current analyst narrative points to revenues of US$2.2b and earnings of US$377.8m by 2029, based on 7.9% yearly revenue growth and an earnings increase of about US$171.7m from US$206.1m today.
Discover why ACI Worldwide's fair value indicates a 32% potential upside to its current price that could close sooner than many investors expect.
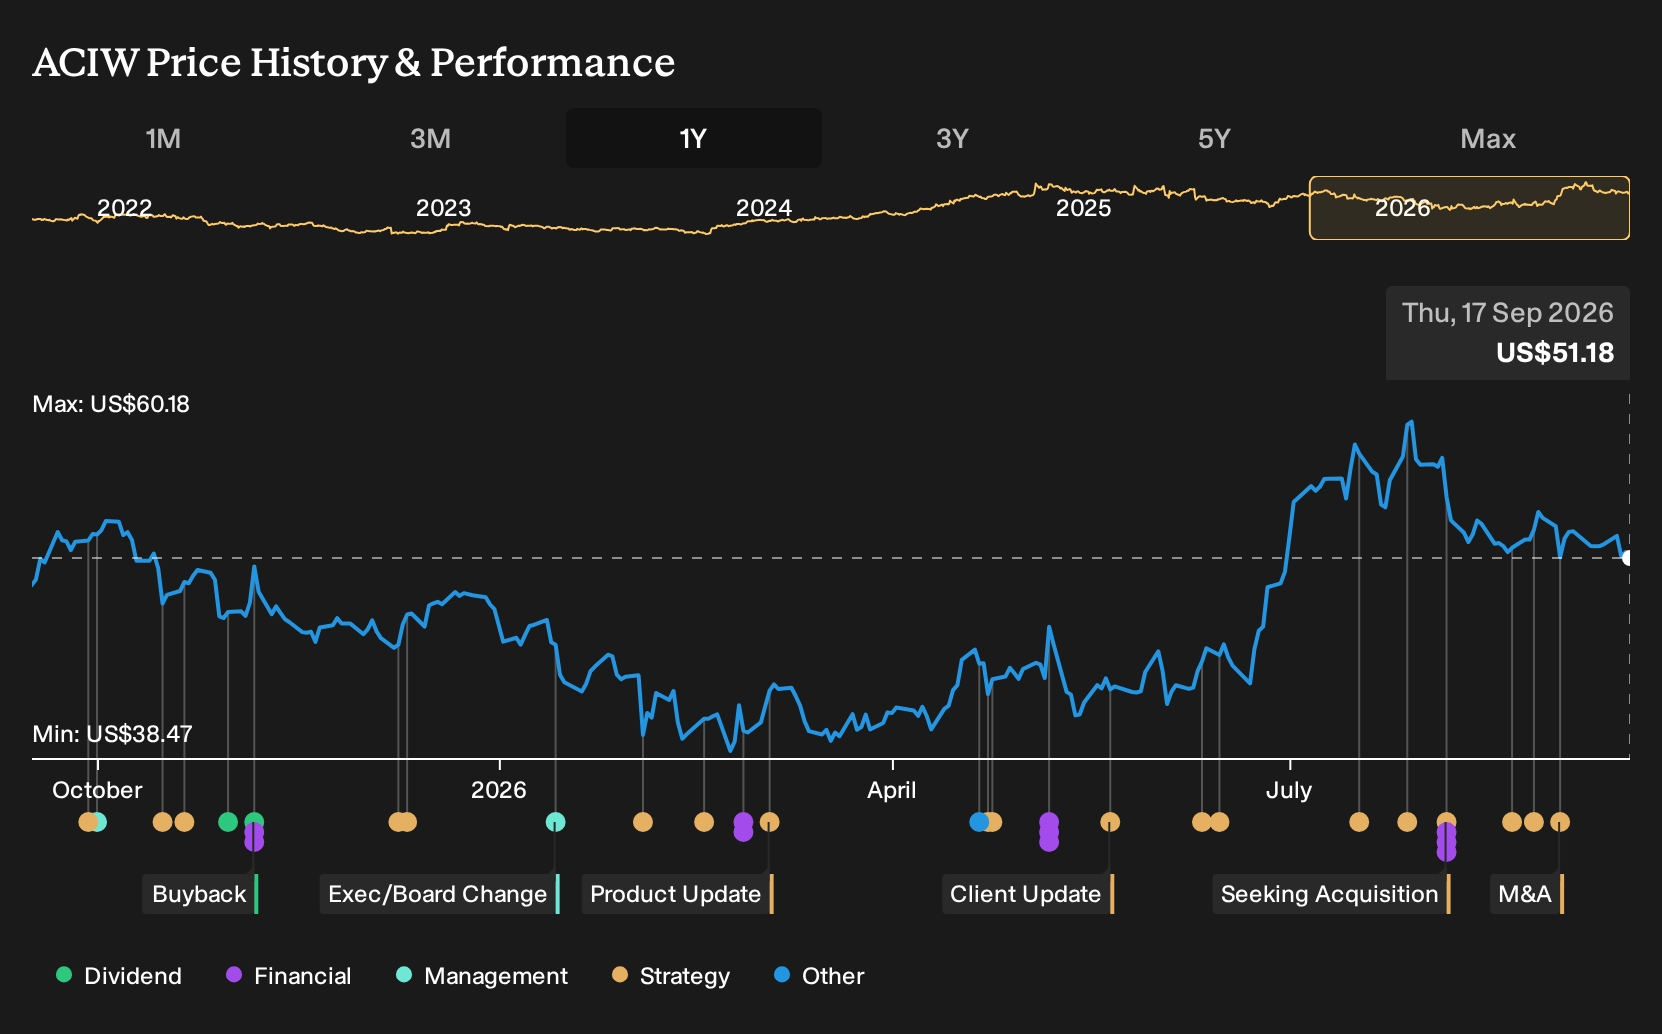
Exploring Other Perspectives
Some of the most optimistic analysts frame this Connetic messaging launch against a different catalyst. They were already expecting organizational changes and cloud offers to push revenue to about US$2.3b and earnings to roughly US$408.1m by 2029. You can now ask whether this new ACI Worldwide product push nudges those bullish views even further or forces a rethink.
Explore 4 other ACI Worldwide fair value estimates, including one that suggests as much as 44% above the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your ACI Worldwide research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ACI Worldwide. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ACI Worldwide's overall financial health at a glance.
Looking For More Investment Ideas Beyond ACI Worldwide?
Once you have a view on ACI Worldwide, it can help to line it up against other opportunities that fit different risk and income profiles. The Simply Wall St Screener lets you compare businesses quickly, so you can build a watchlist that actually matches how you want to invest rather than relying on headlines.
- If you care most about balance sheet strength and financial resilience, start with this list of solid balance sheet and fundamentals (22 results) that filters for companies with sturdier fundamentals.
- If lower volatility and resilience are higher on your priority list, narrow the field using a 11 resilient stocks with low risk scores that focuses on businesses with more measured risk scores.
- If you want to hunt for less crowded ideas with stronger fundamentals, scan through a 16 high quality undiscovered gems that highlights quality companies the market may not be focusing on yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com